Mondelez Beats On Cocoa-Driven Margin Recovery And Broadening Volume, But A Held Outlook Leaves A Heavy Q4 Burden
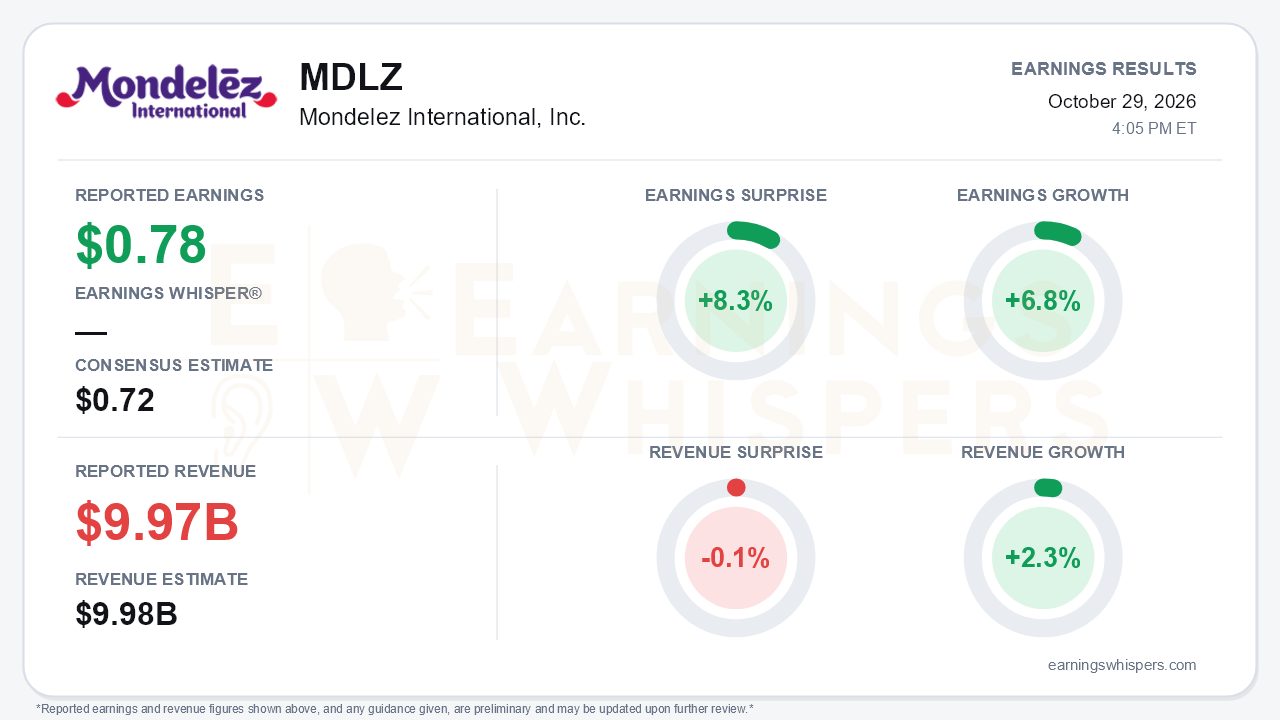
Mondelez International delivered the earnings beat it needed, though not quite the quarter bulls were hoping for. Adjusted EPS of $0.78 topped the $0.72 consensus by 8.3% and grew 6.8% year over year (5.5% in constant currency). That is a sharp turn from a year-to-date adjusted EPS decline of 0.9%, so Q3 marks a clear acceleration in profit growth. Revenue of $9.967 billion rose 2.3% but came in fractionally below the $9.98 billion consensus, a 0.1% miss. The central tension is that margins and volumes improved meaningfully, yet management only reaffirmed full-year guidance. Investors are left to decide whether this was a turning point or simply a catch-up quarter.
The quality of the beat holds up better than the GAAP headline. Diluted EPS jumped 78.9% to $1.02, but $0.34 of that came from a $543 million favorable mark-to-market swing on commodity and currency derivatives, so the GAAP figure overstates the improvement. The adjusted numbers are the real story. Adjusted gross margin expanded 380 basis points to 34.2%, and adjusted operating margin rose 190 basis points to 13.9%. Both gains came mainly from lower raw material costs and manufacturing productivity, with help from volume/mix and pricing. Below the operating line, the picture was less flattering. The adjusted tax rate climbed to 27.0% from 19.5%, and interest expense rose. A 17% gain in constant-currency adjusted operating income therefore shrank to mid-single-digit EPS growth, with a lower share count providing some support.
The composition of revenue shifted in a way that matters more than the headline growth rate. Organic growth of 2.1% was slightly below the 2.4% year-to-date pace, and reported growth slowed from 4.9% year to date. However, volume/mix drove 1.8 points of the gain, versus just 0.6 points year to date, while pricing contributed only 0.3 points. Europe was the swing factor. Volume/mix there turned positive at +1.6 points, even though management estimated unseasonably hot weather cost about a point. That delivered the second-half inflection promised on the prior call. Europe's adjusted operating income rose 53%, although organic revenue still fell 2.1% on 3.7 points of negative pricing as lower cocoa costs flowed through. Emerging markets remained the engine. AMEA grew 7.7% organically with 5.5 points of volume/mix, and India outlet additions reached roughly 130,000 year to date, up from about 100,000 at the Q2 call. North America is the weak spot in the margin story. Management cited share gains in Ritz, candy, and Zbar after reworking promotional depth, but segment adjusted operating income fell 6.4% and margin slipped 150 basis points to 18.0% as advertising and consumer spending rose.
The forward picture is where bears have legitimate ammunition. Mondelez reaffirmed organic growth of at least 2% and constant-currency adjusted EPS growth of flat to 5%, after raising the revenue floor in Q2. Constant-currency adjusted EPS is still down 4.1% through nine months, so even the low end implies a strong fourth quarter. Free cash flow of $1.66 billion year to date leaves about $1.3 billion to generate to reach the roughly $3 billion target. Share repurchases have slowed to $845 million from $1.89 billion a year ago, and short-term borrowings have risen. Management reiterated strong EPS growth for 2027 but added new caution about several pressures:
- freight and other commodity inflation next year;
- continued absorption of Middle East conflict costs;
- a soft North American consumer that is not expected to improve soon;
- inflation weighing on consumers in India;
- continued softness in China.
Technical difficulties truncated the call, which limited the detail investors could extract. On the positive side, phase one of the ERP rollout was completed in North America and Latin America, and the Undercover Snacks deal extends the company's push into permissible indulgence.
Investor sentiment entering the report was negative and deteriorated modestly, slipping from -0.24 to -0.30. Shares closed at $61.87 ahead of the release, 3.0% below the open following the July report. The stock has given back much of the spike that produced a 52-week high of $66.65 the day after that report. It rebounded about 7.9% from an early-October low of $57.32 and sits 2.6% above its 200-day moving average. Price and momentum readings have turned positive, while the AVWAP trend remains negative, consistent with a stock that has recovered but not reclaimed its post-July footing.
The bottom line is that Mondelez produced a genuinely better quarter, with expanding margins, broadening volume, and a Europe recovery that arrived on schedule. Even so, management chose to hold the line rather than raise it. With a demanding Q4 implied by guidance, 2027 cost inflation already flagged, and skeptical sentiment, the beat improves the setup without resolving the debate. The next leg depends on proving that volume-led growth can survive a softer consumer and returning cost pressure.
Read our earnings preview for Mondelez International, Inc.: https://www.earningswhispers.com/article/MDLZ/21213
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 |
