American Coastal Misses As Soft-Market Pricing Erodes Earnings, But Retention And The E&S Build-Out Point To 2027 Growth
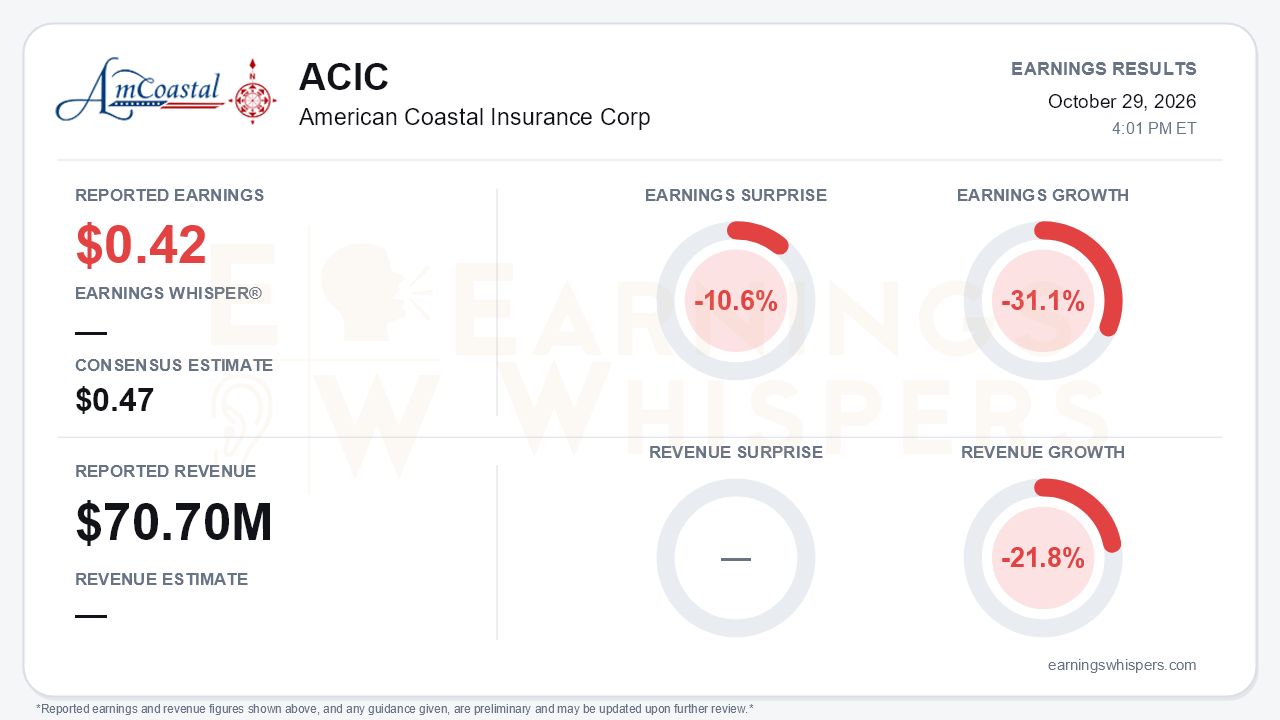
American Coastal Insurance (NASDAQ: ACIC) reported third-quarter core earnings of $0.42 per share, missing the $0.47 consensus estimate by 10.6% and falling 31.1% from a year ago. Revenue fell 21.8% to $70.7 million. GAAP earnings were $0.40 per diluted share, down from $0.65, as net income dropped to $19.4 million from $32.5 million. Those figures show what a softening Florida commercial residential market is doing to the earnings base. Management, however, used the call to argue that the business has stopped shrinking and is building new revenue channels. The central tension is whether those growth initiatives can scale before pricing compresses margins further.
The quality of the quarter deserves scrutiny. The reported 64.7% combined ratio looks excellent and improved sharply from 74.3% in the second quarter, but it was helped by 8.4 points of favorable prior-year reserve development. That benefit more than offset 4.7 points of catastrophe losses. On an underlying basis, the combined ratio was 68.4%, compared with 57.8% a year ago, a 10.6-point deterioration. CEO Brad Martz emphasized that the underlying figure is consistent with the first half of the year, and the nine-month underlying ratio of 68.6% supports that. Still, the year-over-year trend is clearly worse. The expense ratio rose 7.0 points to 52.5% because costs did not fall as quickly as net premiums earned, which declined 19.0%. The ceding ratio also rose to 52.8% from 50.3% as the company bought more catastrophe reinsurance to raise its exhaustion point. Net pricing fell 25.6% year over year according to the release. The call cited rate declines of roughly 20%, so the precise figure depends on the measure, but the direction is unambiguous.
Beneath that pressure, the operating metrics moved in a better direction. Gross premiums written rose 3.2%, the first year-over-year growth since early 2025. That compares with roughly -5% in the second quarter and -19% in the fourth quarter of 2025. Account retention improved to about 90% from about 85% in the second quarter, and policies in force are up about 7% year to date. The headline growth needs context, though. Excluding $8.6 million of assumed E&S premium, the underlying book was down about 9%. In other words, the return to growth is being purchased through new channels while the core Florida franchise is still contracting in dollar terms.
Those new channels are the heart of the bull argument. The AmRisc partnership has been made permanent, and participation in AmRisc's nationwide E&S commercial property portfolio has contributed $37.3 million of premium this year. ACES Specialty received its certificate of authority. Skyway has already quoted E&S submissions, with first binds expected around December through third-party fronting carriers. A potential Lloyd's syndicate partnership could generate MGA fee income starting in 2027. Management said 2027 revenue growth across gross written premium, net premiums earned, and total revenue is achievable even with a double-digit rate decrease. It also said the pace of rate declines is moderating.
Bears have legitimate ammunition. Management described some competitors as "reckless" and expects another double-digit rate cut in 2027. Fronting fees will raise E&S acquisition costs. The Lloyd's deal is still in negotiation, and calendar-2026 E&S premium was already cut to about $50 million from $70 million in the second quarter. Full-year revenue guidance of $300-$320 million, lowered last quarter, was not updated, and 2027 guidance is deferred to January. The company also repurchased no shares in the third quarter after buying about 1.8 million shares in the first half. However, management indicated a special dividend is likely later this year absent major fourth-quarter catastrophe losses, and it described Hurricane Isaias as having only a minor fourth-quarter impact. Book value per share reached $7.52, up 15.5% since year-end, and underlying book value was $7.79.
The market setup is more complicated than the miss implies. Shares fell to a 52-week low of $9.01 on September 30, then rallied about 21% to $10.87 heading into the report. That leaves them 5.3% below the October 22 inter-earnings high of $11.48 and 1.8% above the 200-day moving average of $10.68. The stock is still down 3.3% since the opening after the August report. Investor sentiment slipped modestly from 0.167 to 0.147, remaining mildly positive. The trend readings are mixed, with momentum negative and AVWAP positive.
The bottom line is that American Coastal missed because softer pricing is steadily eroding earned premium, and reserve releases flattered the headline combined ratio. Underlying profitability is weaker than a year ago, though it has been stable for three quarters. What changed is the forward narrative: retention, unit growth, and a now-licensed E&S platform give management a credible path to 2027 revenue growth. Investors should wait for the January guidance before concluding that the growth story can outrun the soft market.
Read our earnings preview for American Coastal Insurance Corp: https://www.earningswhispers.com/article/ACIC/21160
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-15 | |
| Oct-08 | |
| Oct-06 | |
| Sep-14 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jun-29 | |
| May-05 |
