Rocket Companies Matches Estimates And Widens Margins, But A Weak Q4 Revenue Guide Shows The Rate Shock Catching Up
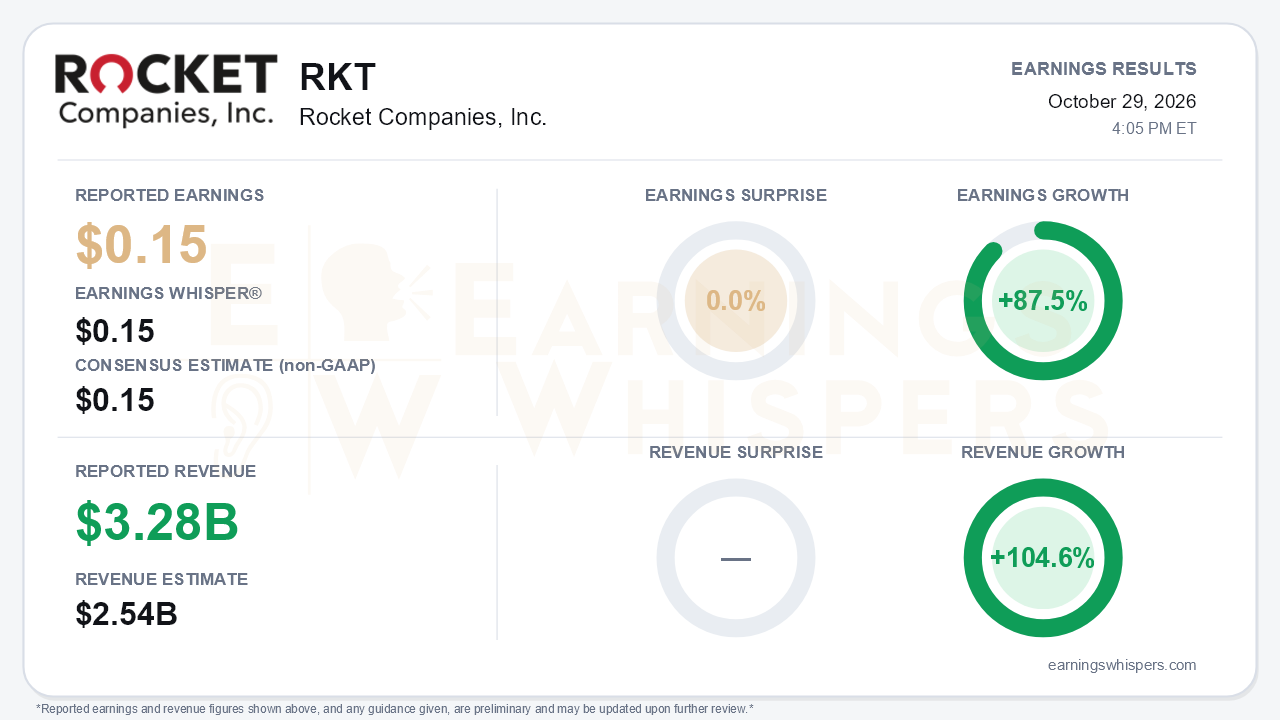
Rocket Companies delivered adjusted earnings of $0.15 per share for the third quarter, matching both the consensus estimate and the Earnings Whisper number. Earnings grew 87.5% from a year ago. Reported revenue of $3.284 billion beat the $2.54 billion consensus by 29.3% and rose 104.6% year over year. The headline numbers flatter the trajectory, though. That is the central tension: Rocket is running the most profitable version of its business in nearly five years just as the mortgage market beneath it is shrinking fast, and the fourth-quarter outlook makes that plain.
The quality of the revenue beat deserves scrutiny. Total revenue includes a $710 million favorable change in the fair value of mortgage servicing rights, net of hedges, which management excludes from its own measures. Adjusted revenue was $2.57 billion, much closer to the consensus figure and within the $2.5 to $2.7 billion range management guided for the quarter. The same mark explains GAAP net income of $709 million, or $0.25 per share, a sharp swing from a $124 million loss a year earlier. The year-over-year growth rates also reflect the Mr. Cooper and Redfin acquisitions more than organic momentum. Servicing fee income rose to $1.03 billion from $413 million, and the diluted share count grew to 2.85 billion from 2.11 billion. One line that did not inflate: gain on sale excluding originated MSRs fell to $302 million from $641 million.
Sequentially, the picture is one of decelerating volume and expanding profitability:
- **Volume:** Adjusted revenue slipped from $2.82 billion in Q1 to $2.8 billion in Q2 and $2.6 billion in Q3. Net rate locks fell to $40.4 billion from $47 billion in Q2 and $49 billion in Q1. Adjusted EBITDA dipped to $748 million from $766 million, and adjusted EPS eased to $0.15 from $0.16.
- **Margin:** Adjusted EBITDA margin rose to 29%, the fourth straight expansion (23% in Q4'25, 26% in Q1, 28% in Q2). Gain on sale excluding correspondent improved to 333 basis points from 311. Direct to Consumer reached 431 basis points, lifted by record home equity volume.
- **Share:** Purchase share climbed to roughly 6.5% from 6.2%, and refinance share to 15.5% from 14.3%.
CEO Varun Krishna's claim that Rocket "changed the economics" of the business has support in these figures. Share gains and margin expansion in a 7.3% rate environment are not trivial.
The forward-looking evidence is where bears have legitimate ammunition. Q4 adjusted revenue guidance of $2.1 to $2.3 billion implies roughly a 15% sequential decline at the midpoint and came in below estimates. Management's market outlook was bleak:
- Refinance volume is expected to fall by almost half from Q3 to Q4, with industry refi applications already down more than 50% year over year and purchase applications down about 20%.
- The fourth quarter could rank among the lowest-volume mortgage quarters in three decades.
- The 2027 origination market may come in below $2 trillion.
That is a marked reversal from the growth-market framing of a year ago. Margin support now leans on home equity and cash-out mix and on rational competitor pricing. Management also said it is reviewing its more than $300 billion of origination capacity, with an update promised next quarter. That reads as a signal that further cost action is possible.
The offsets are tangible:
- **Synergies:** Mr. Cooper expense synergies reached $300 million, with the full $400 million due in Q4 and another $100 million slated for the first half of 2027.
- **Expenses:** Q4 core expenses are guided to $1.85 billion, down $165 million.
- **Recapture:** Legacy Cooper recapture hit a record 60%, against a 65% target for end-2027.
- **Distribution:** Rocket Pro added about 200 broker partners, representing roughly $12 billion of potential annual volume. Compass-linked locks topped $3 billion, and exclusive listings grew to about 40,000 from 25,000.
- **Balance sheet:** Liquidity reached a record $11.4 billion, giving Rocket room to absorb a downturn.
The market had already priced in much of the macro deterioration before the report. Shares closed at $11.57 the day before earnings, down 18.7% from the $14.23 open after the August report. They sit 22.2% below the 200-day moving average and well beneath the inter-earnings high of $15.18. The stock hit a 52-week low of $10.18 on October 14 and has since rebounded about 13.7%. The Earnings Whispers trend signals lean negative, with price and AVWAP trends negative and sequential growth and momentum neutral. Investor sentiment edged up from 0.055 to 0.070, a slight improvement that leaves expectations only modestly positive rather than enthusiastic.
The bottom line is that Rocket executed well on what it controls: margins, market share, synergies and liquidity. The in-line EPS and the mark-driven revenue beat say little about where the business is heading. The more important signals are the guided Q4 revenue drop, the halving of refinance demand and a possible sub-$2 trillion 2027 market. Rocket appears structurally more profitable per loan than it was a year ago, but with shares near their lows, investors still face a shrinking volume base that efficiency gains can cushion but not fully offset.
Read our earnings preview for Rocket Companies, Inc.: https://www.earningswhispers.com/article/RKT/21326
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 4 hours | |
| 5 hours | |
| 13 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 |
