Illumina Raises Guidance Again, But A Whisper Miss And Slowing Instrument Growth Test A 42% Rally
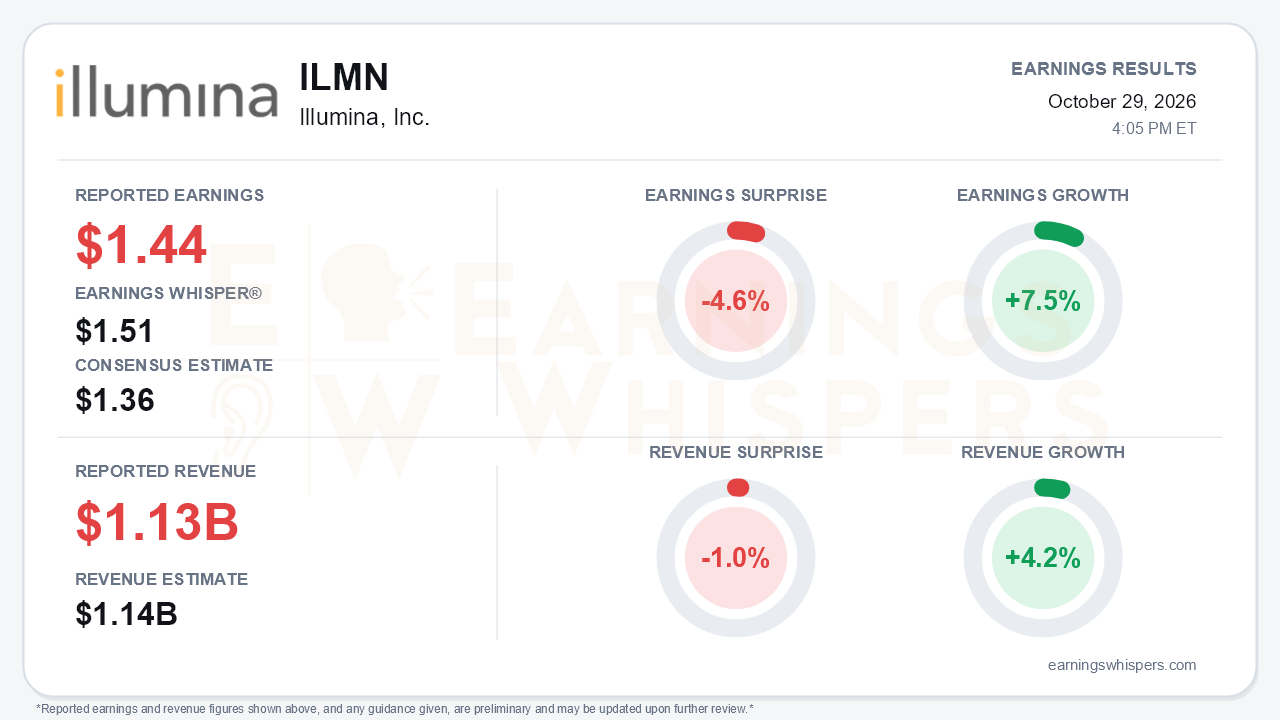
Illumina (NASDAQ: ILMN) delivered its third straight raise of full-year guidance. The headline scorecard, though, is less tidy than the guidance suggests. Non-GAAP EPS, excluding tariff refunds, was $1.44. That cleared the $1.36 consensus but fell 4.6% short of the $1.51 Earnings Whisper number, the bar that matters for a stock that had rallied hard into the print. Revenue of $1.129 billion missed the $1.14 billion consensus by 1.0%. Earnings grew 7.5% year over year and revenue grew 4.2%. That is the central tension: management keeps lifting the annual outlook while quarterly growth is cooling from a strong second quarter.
The quality of the quarter deserves scrutiny because tariff refunds under the International Emergency Economic Powers Act distort nearly every reported line. Illumina booked a $79 million benefit to cost of revenue. It also took a $37 million reduction to revenue for refunds it expects to pass to customers. That revenue reduction helps explain the top-line miss, since revenue excluding refunds was $1.17 billion. With the refunds included, non-GAAP EPS was $1.62 and non-GAAP gross margin was 75.3%, but neither figure reflects the run rate. Stripping out the refunds gives a cleaner view:
- Non-GAAP gross margin was 69.4%, essentially flat with 69.2% a year ago and up from roughly 68.2% in each of the first two quarters.
- Non-GAAP operating margin was 25.0%, ahead of the roughly 24% guide.
- GAAP EPS was $1.43. The refund gain was partly offset by a $0.19 per-share loss on strategic investments.
Cash generation was a genuine positive. Free cash flow was $378 million, up from $253 million a year earlier and $162 million in Q2.
Beneath the headline, growth normalized meaningfully:
- **Overall growth:** Rest-of-world organic growth slowed to 4.7% from 8.1% in Q2, and management guided Q4 to about 4.5%.
- **Instruments:** Revenue fell 2% organically after rising 31% in Q2, which management attributed to weak EMEA and Latin America.
- **NovaSeq X placements:** These eased to 80+ from 95+. The trailing four-quarter total of roughly 360 still exceeds the launch year.
- **Clinical:** Consumables growth held at 14-15%, down from about 20% in late 2025 and early 2026. Clinical conversion to the X platform stalled at 78%, with customers keeping on-market assays on the older 6K.
- **Research:** Research and applied consumables still declined 6%, but they have grown sequentially for two quarters. Research X conversion is now largely complete, so pricing headwinds should ease in 2027.
The guidance carries the bullish argument:
- Full-year revenue guidance moved to $4.64-$4.66 billion, up from $4.50-$4.60 billion at the start of the year.
- Non-GAAP EPS guidance rose to $5.40-$5.45 from $5.05-$5.20.
- Operating margin guidance settled at about 23.6%, the top of the prior range.
Organic growth targets of above 4%, and above 5% for rest of world, were left unchanged. The dollar raises therefore reflect execution and mix more than an acceleration in underlying demand.
On catalysts, management reaffirmed its high-single-digit 2027 growth framework and said there is "definitely upside" to it. Other positives included:
- China returned to year-over-year growth.
- GSK joined the Billion Cell Atlas, which is now more than halfway complete.
- The BioInsight data platform launched.
- Customer interest in reagent rental and operating lease arrangements is rising.
Bears have legitimate ammunition as well:
- Rivals are offering genome pricing of roughly $50, and management acknowledged possible concessions on large-volume deals.
- Cost inflation persists in memory, electronic components, freight and tariffs.
- Management flagged a new China geopolitical development late in the call with uncertain impact.
- Clinical growth is expected to slow to low double digits in Q4 against a tough comparison.
The market setup is more complicated than a beat-and-raise implies. Shares closed at $288.79 the day before the report, up 42.1% from the open after the July release. That left the stock 65.2% above its 200-day moving average and 6.6% below the $309.35 52-week high set on October 6. Investor sentiment improved from -0.19 to +0.09, a solid shift from mildly negative to modestly positive rather than outright enthusiasm. The Earnings Whispers trend signals are mostly positive, but sequential growth is only neutral, consistent with a business still growing at a slower rate than last quarter. A stock priced for momentum faces a harder test from a whisper miss and decelerating instrument sales than one still in the penalty box.
The bottom line is that Illumina's fundamentals are improving in the ways long-term holders care about: margins, cash flow, a stabilizing research business and a credible 2027 growth story. Even so, this quarter showed that the Q2 surge was a peak, not a new baseline. After a 42% run, investors will need evidence that clinical conversion resumes and instrument placements recover before the steady guidance raises can carry the stock much further.
Read our earnings preview for Illumina, Inc.: https://www.earningswhispers.com/article/ILMN/21205
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 5 hours | |
| 5 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-14 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 |
