Floor & Decor's Q3 Beat Is Overshadowed By An October Relapse, Lower Guidance, And Slower 2027 Store Growth
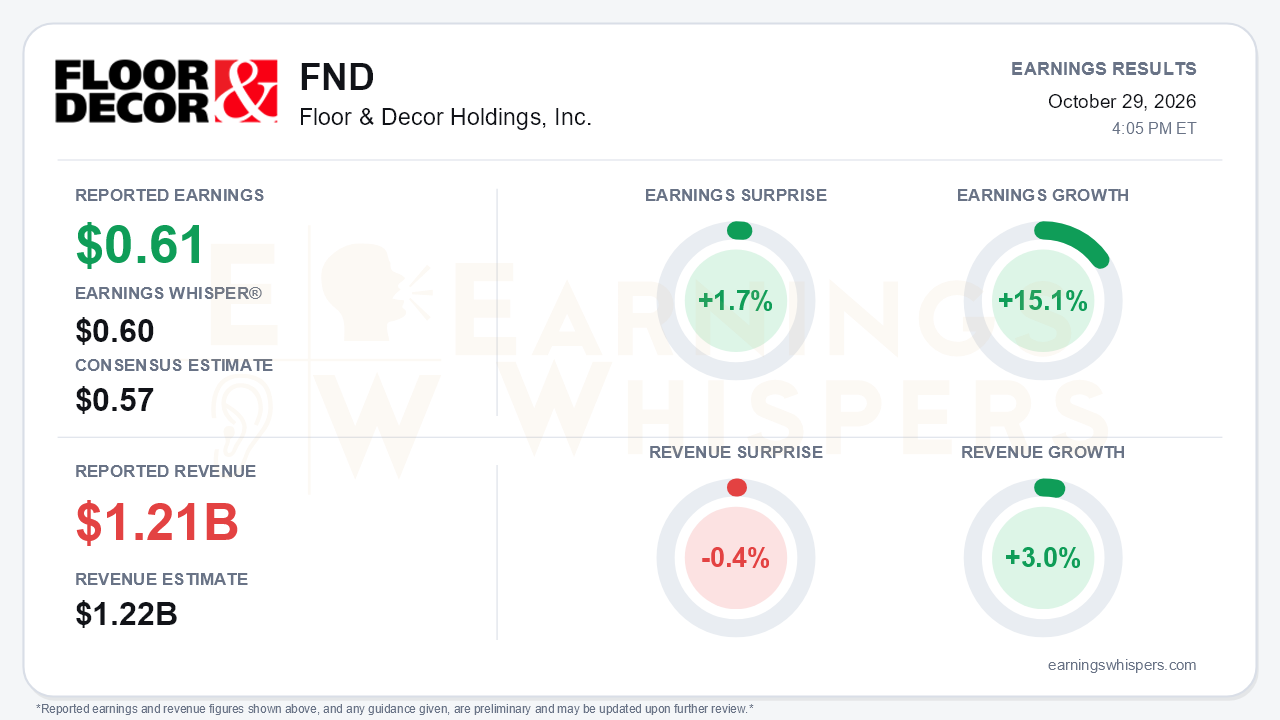
Floor & Decor delivered the cleanest earnings quarter it has posted in 2026, then told investors it may not last. Diluted EPS of $0.61 rose 15.1% from a year ago. That topped the $0.57 consensus and edged past the $0.60 Earnings Whisper number, for a +1.7% surprise. Revenue of $1.215 billion grew 3.0% but slipped 0.4% short of consensus. The central tension is timing. Third-quarter comps improved for a third straight quarter, and September turned positive at +0.4%, the first positive month since January. Yet quarter-to-date comps in October have fallen back to roughly -3.8%. Management responded by trimming full-year guidance, moderating 2027 unit growth, and flagging mounting margin pressure. The quarter looked like the start of a recovery; the call argued the recovery has not arrived.
The quality of the beat holds up reasonably well. Unlike the first half, no tariff-refund benefit sits in the third quarter, so GAAP and adjusted EPS were identical. Year-to-date adjusted EPS is still down 0.6%, which means the third quarter is the first period this year to show genuine adjusted earnings growth. Sales growth also improved from the 1.8% year-to-date pace. Operating income rose 8.3%, and operating margin widened 30 basis points to 6.4%. Gross margin expanded 30 basis points to 43.7% despite roughly 100 basis points of diesel-driven supply chain headwind, while SG&A held flat at 37.3% of sales. Still, a lower tax expense and a smaller share count did some of the work. Management put EPS growth at about 11% excluding tax effects. Cash generation was the standout: year-to-date operating cash flow reached $485 million versus $258 million a year earlier, helped by a large swing in payables. That funded a stepped-up buyback of $91.4 million in the quarter, up from $65.7 million in Q2.
Beneath the headline, the operating story is genuinely mixed. On the positive side:
- Comp ticket improved to +1.6% from +0.8% in Q2.
- Pro penetration reached 55%, versus about 50% a year ago, and Pro sales grew 9% in September.
- Installation materials rose 10% and tile rose 5%.
- Laminate and vinyl declines narrowed to -3% from -10.4% in Q1.
- Twelve of 16 districts posted positive comps excluding cannibalization, up from eight in Q2.
But transactions still fell 2.9%, and the transaction outlook was lowered to down mid-single digits. With 30-year mortgage rates back above 7%, management would not call a bottom in big-ticket demand.
The guidance revisions carry the weight of the report. Full-year sales were narrowed to $4.765 billion to $4.835 billion, from $4.77 billion to $4.99 billion. Comps moved to -3.5% to -2.0%, from flat to -4%. Adjusted EBITDA fell to $535 million to $550 million, the latest in a series of reductions from the original $560 million to $590 million. Adjusted EPS of $1.88 to $1.98 lost its top end even with a lower tax rate. That range also includes about $0.08 from the 53rd week. Gross margin is now pinned at the low end, about 43.6%, and SG&A deleverage widened to about 38.5% of sales.
The 2027 setup is arguably more concerning. Store openings drop to 10 to 15 from 20, which management framed as temporary pacing while reaffirming its 500-store target. The 2025 and 2026 store classes are tracking below the 2024 class, and mature store volumes have slipped to about $20 million from roughly $21 million. Management also declined to rule out a 2027 gross margin decline as tariff refunds roll off and the Pro Loyalty program ramps. The national Pro Loyalty launch in Q1 2027 remains the key catalyst, alongside planned assortment expansion in installation materials and outdoor.
Investor sentiment barely moved, edging from -0.316 to -0.303. Expectations remained negative but improved only marginally heading into the report. The stock reflects that skepticism. At $47.55, shares are down 18.7% since the open following the July report and sit 13.6% below the $55 200-day moving average. They are roughly 25% under the August 7 high of $63.25, though they have recovered 11% off the October 14 low of $42.85. Earnings Whispers trend readings lean cautious, with both price and AVWAP trends negative. That pre-report rebound suggests some investors were betting September's improvement would carry forward, an assumption October's numbers directly challenge.
The bottom line is that Floor & Decor executed well in a hostile market, gaining Pro share, protecting gross margin, and converting more profit into cash, but the forward signals deteriorated. A relapse in October trends, a fourth consecutive EBITDA guide reduction, slower 2027 store growth, and weaker new-store productivity outweigh a modest beat. The cash flow and buyback provide a floor of support for the story. However, bulls now need housing turnover and Pro Loyalty to do the heavy lifting in 2027, and management offered little assurance on either front.
Read our earnings preview for Floor & Decor Holdings, Inc.: https://www.earningswhispers.com/article/FND/21195
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-01 |
