DXC Beats On A One-Time Insurance Boost, But A Bookings Slump And Broad Guidance Cut Undercut A Stock Riding Sale Speculation
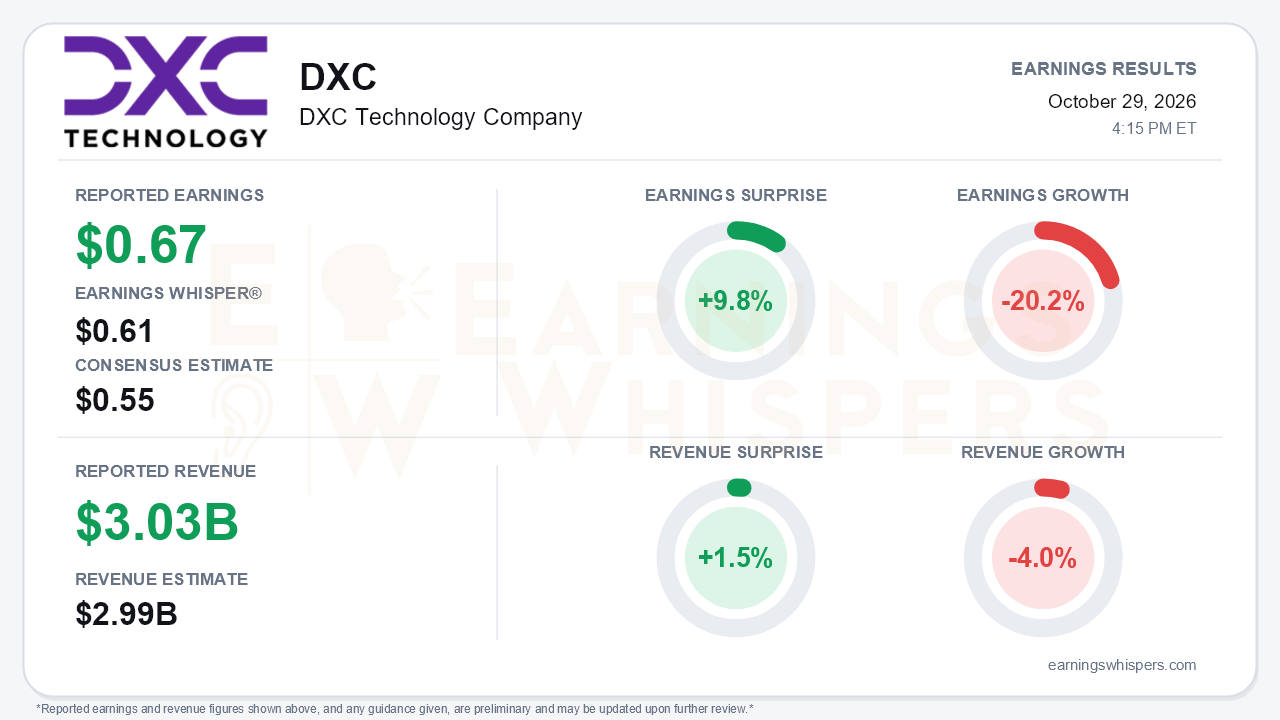
DXC Technology cleared the bar on paper. Fiscal second-quarter non-GAAP EPS of $0.67 topped the $0.55 consensus by 9.8% and beat the $0.61 Earnings Whisper number. Revenue of $3.034 billion was 1.5% above the $2.99 billion estimate. Underneath the beat, earnings still fell 20.2% year over year and revenue declined 4.0%. Management also used the call to cut full-year guidance on revenue, margin, EPS and free cash flow. That is the central tension: a headline beat that was largely manufactured by a single contract event, attached to a forward outlook that got meaningfully worse.
The quality of the beat deserves scrutiny. Insurance revenue jumped 23.1% organically and segment profit rose 60.7%, but the release notes that growth included a favorable contract modification signed during the quarter. The call acknowledged that, excluding this item, results were only roughly in line. The core businesses deteriorated:
- **GIS:** revenue fell 10.0%, segment profit dropped 45.9%, and margin compressed to 4.6% from 7.7%.
- **CES:** revenue slipped 3.3%, and margin fell to 10.3% from 11.6%.
- **Consolidated:** adjusted EBIT declined 26.4% to $187 million, and margin contracted 180 basis points to 6.2%.
On a GAAP basis the picture is thinner still. EBIT fell 52.2% to $66 million, and diluted EPS was just $0.15, down from $0.20. Per-share results also had help from a roughly 10% lower diluted share count. Quarterly free cash flow fell to $91 million from $240 million, although first-half free cash flow of $405 million ran ahead of last year's $337 million.
The more damaging disclosure was bookings. Q2 bookings fell 10% to $2.4 billion, and book-to-bill dropped to 0.80x. That compares with 0.99 in Q1 and 1.07 in Q4 FY26. CES bookings fell 17% and GIS bookings 13%. Management cited lower win rates and stiffer competition in the Americas, slipped UK and Ireland public-sector deals, and clients shortening contract terms from five years to two. Customers are also adding agentic-versus-traditional evaluations to decision cycles. Management said it is "not satisfied" and called some losses "self-made." That is a sharp change from Q1, when management described more opportunity than risk in the guide and touted six-week AI sales cycles. The company now assumes weak pipeline conversion persists through the second half.
The guidance cuts reflect that shift:
- **Organic revenue:** now a 5.0%–5.5% decline, versus the 3%–5% decline reaffirmed in each of the prior two quarters.
- **Segments:** CES moved to a mid-single-digit decline, reversing Q1's upgrade, and GIS moved to a high-single-digit decline.
- **Adjusted EBIT margin:** narrowed to 5.75%–6.25% from 6%–7%.
- **Non-GAAP EPS:** reset to $2.25–$2.50 from $2.40–$2.90.
- **Free cash flow:** about $600 million versus roughly $685 million previously.
- **Q3:** about $0.55 in EPS on a roughly 6% organic revenue decline, implying further year-over-year erosion.
Management is responding with an expanded cost-takeout plan and is evaluating deeper FY28 actions.
The bull case rests on catalysts rather than the core trajectory. DXC confirmed ongoing discussions about a possible sale of its insurance business. On the call, the Guidewire/hyperexponential deal at roughly 20 times revenue was cited as a valuation reference. On AI, the company pointed to several early wins:
- its first large GrowthX modernization-as-a-service win with a global bank, built on Anthropic's Claude, with seven to eight follow-on projects referenced;
- OASIS utilization up sixfold sequentially;
- the launch of Frontier Code Assurance and a LangChain partnership;
- more than 5,700 AI-certified employees.
These are credible early signals, but they remain small against a $12 billion revenue base shrinking mid-single digits.
The market setup is more complicated than the surprise implies. Shares closed at $16.09 the day before the report, up 43.8% from the open after the July release and 39% above the 200-day moving average of $11.58. The stock entered earnings just 1.8% below a 52-week high of $16.38 set on October 26. The run was compressed into a short window: the inter-earnings low of $10.13 came only on September 29. Investor sentiment remained negative but improved meaningfully, from -0.36 to -0.11. Price and AVWAP trend readings are positive while sequential growth is negative, which matches a stock rallying on event potential while the operating trend worsens. Much of that rerating appears tied to the insurance-sale story rather than to the core business that just lowered its outlook.
The bottom line is that DXC's beat was flattered by a one-time insurance gain and did little to offset a weak bookings quarter, three consecutive guidance-direction reversals capped by a broad cut, and a more chastened management tone. Bears have legitimate ammunition in the 0.80x book-to-bill and the GIS margin collapse. Bulls are leaning on a potential insurance divestiture and nascent AI traction. With the stock near its high and well above trend, the outcome of the insurance-sale talks now matters more to the near-term setup than the quarter's headline beat.
Read our earnings preview for DXC Technology Company: https://www.earningswhispers.com/article/DXC/21184
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Sep-28 | |
| Sep-25 | |
| Sep-22 |
