Digital Realty Beats And Raises Again On Record Leasing, But A Flat Sequential Quarter And Rising Funding Needs Keep The Setup Complicated
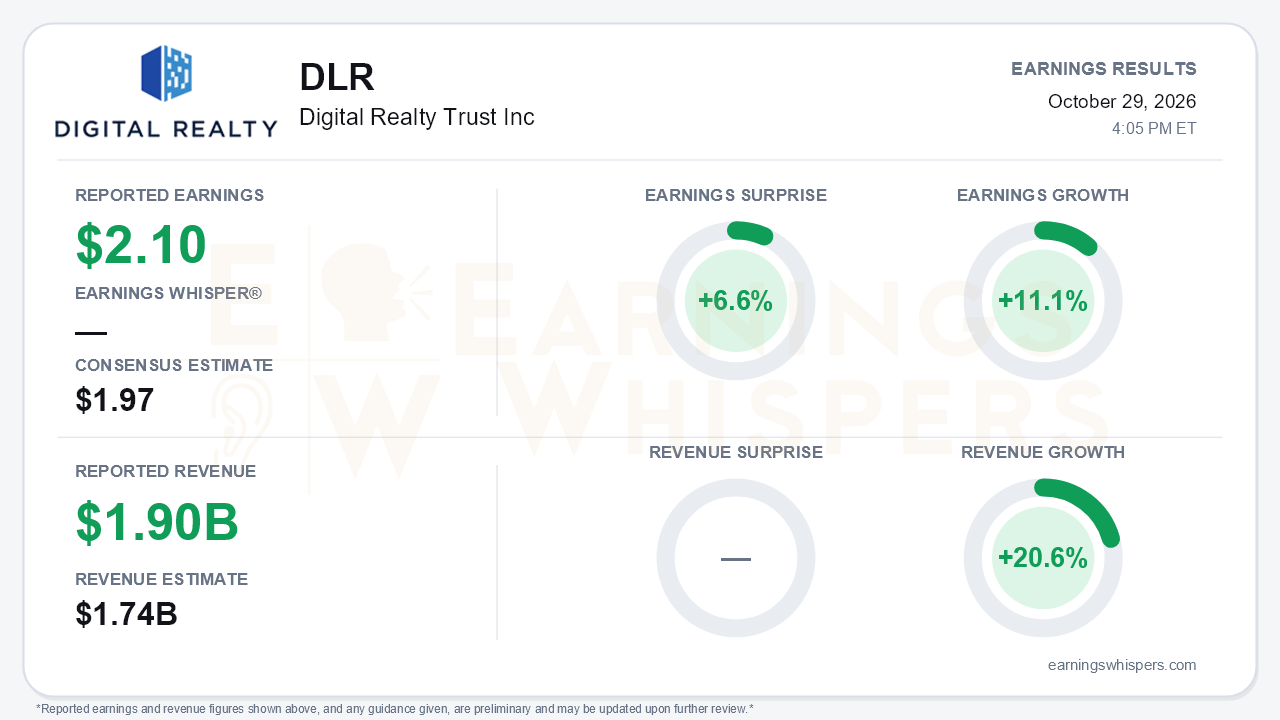
Digital Realty delivered a clean beat on both lines and the most forward-looking evidence of demand it has produced this year. Core FFO (excluding net promote) of $2.10 per share topped the $1.97 consensus by 6.6% and grew 11.1% year over year. Revenue of $1.902 billion beat the $1.74 billion estimate by 9.3% and rose 20.6%. The bigger story sits in leasing. Total bookings reached a record $855 million of annualized GAAP rent at 100% share ($627 million at Digital Realty's share), and the signed-but-not-commenced backlog climbed to $2.5 billion from $1.9 billion last quarter. Management also raised 2026 guidance for the third straight time. The central tension is that the forward pipeline is accelerating while the current quarter's per-share earnings actually stalled sequentially.
The quality of the beat deserves some scrutiny. Core FFO per share slipped to $2.10 from $2.13 in the second quarter, although the call noted that Q2 included roughly $0.07 of insurance proceeds. Year-over-year growth also slowed to about 11% from 14%. Adjusted EBITDA of $978 million was flat with Q2.
Revenue growth was flattered by pass-through items. Utility reimbursements jumped to $424 million from $353 million, against a matching $81 million increase in utility expense.
GAAP interest expense fell to $93 million from $114 million, but that drop is less impressive than it looks. Capitalized interest nearly doubled to $71 million as construction in progress swelled to $10.6 billion. That shift helps reported FFO without reducing the actual cost of carrying the development book.
Dilution is the other drag on per-share results. Diluted Core FFO share count rose about 9% year over year as the company sold $2.9 billion of ATM equity year to date, including $450 million in Q3.
On GAAP results, net income per share rose to $0.48 from $0.15 a year ago.
The call preserved a credible, and strengthening, growth story. Bookings in the 0-1 MW plus interconnection category hit a fourth consecutive record at $152 million, up roughly 40% from Q2. Management said 44% of 0-1 MW bookings were AI-related, versus about 20% in the prior two quarters, which suggests inference workloads are now reaching the enterprise colocation business, not just hyperscale. Hyperscale signings also set a record, and Asia Pacific bookings came in more than 600% above the region's prior record. Other operating metrics improved as well:
- Stabilized occupancy rose 90 basis points to 93.4%.
- Churn hit a record-low 0.7%.
- The development pipeline expanded to 1.5 GW and $22 billion at an 11.6% expected yield, up from 769 MW at year-end.
Guidance moved up across the board. The Core FFO outlook rose to $8.30-$8.35, implying roughly 13% growth versus the 8% initially guided. Same-capital cash NOI growth guidance went to 5.25%-5.75%, and cash renewal spread guidance to 10%-12%. Management also signaled double-digit FFO growth into 2027. One caveat applies to the raise: it moved the outlook closer to where the Street already sat rather than far beyond it. Subtracting the $6.27 earned through nine months from the new range implies fourth-quarter Core FFO of roughly $2.03-$2.08, below Q3's $2.10.
The forward catalysts are substantial:
- a $1.4 billion initial close for a perpetual capital vehicle targeting stabilized North American hyperscale assets, which supports the higher $1.5-$2.0 billion capital-recycling target;
- a Moody's upgrade to Baa1;
- roughly $1.7 billion of October euro and Swiss franc debt at about a 4% blended coupon;
- new land for more than a gigawatt near Indianapolis and up to 600 MW in Charlotte.
Bears still have legitimate ammunition. Net debt to adjusted EBITDA rose to 5.2x from 4.7x (4.9x pro forma), and cash fell to $803 million. The Teraco stake increase is being paid largely in stock. Commencements were flat at about $207 million, and the 17-month lag between signing and commencement means much of the record leasing will not reach earnings until 2027-2028. Management also spent more time on community and regulatory scrutiny of power and water use, construction delays, and cost inflation. Cash renewal spreads normalized to 11.8% from Q2's outlier 25%-plus.
Investor sentiment improved meaningfully into the report, rising from 0.30 to 0.50. The tape has not followed. Shares closed at $179.77 ahead of the release, down 5.4% from the $190 open after the July report. The stock has given back the entire post-report spike to $207.47 and sits 1.8% below its 200-day moving average, about 7.5% above the October 15 low of $167.17. Price and AVWAP trend readings remain negative even as sequential growth and momentum readings are positive, consistent with fundamentals improving faster than the stock.
The bottom line is that Digital Realty's leasing, backlog and guidance now describe a business with accelerating demand and multi-year earnings visibility, led increasingly by AI inference. The near-term per-share story is less tidy. Sequential Core FFO is flat to down, capitalized interest is supporting results, and record growth is being funded with equity, asset recycling and higher leverage. Investors are growing more constructive while the shares remain below trend, so the question is whether the expanding backlog converts into per-share growth fast enough to outpace that dilution.
Read our earnings preview for Digital Realty Trust Inc: https://www.earningswhispers.com/article/DLR/21182
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Oct-22 | |
| Oct-21 | |
| Oct-16 | |
| Oct-14 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 |
