Columbia Sportswear's Q3 Beat Shows Its First Real U.S. Turn, But Timing And Tariff Refunds Muddy The Read
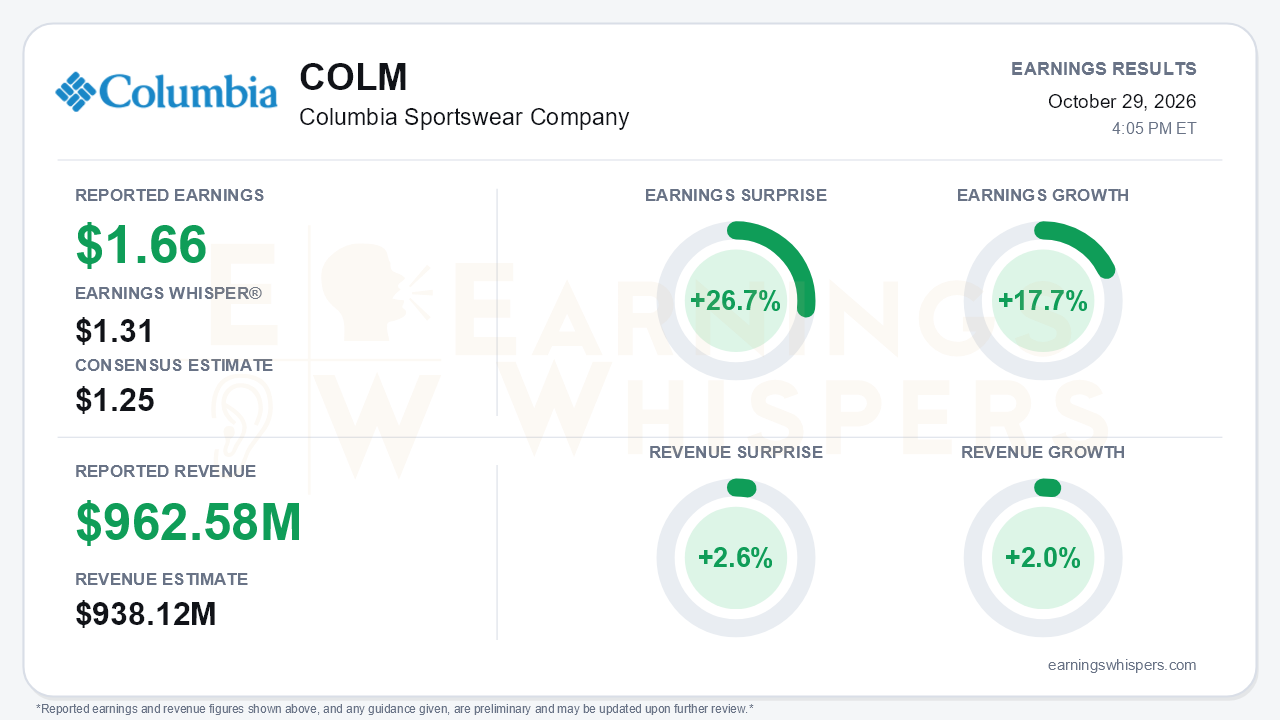
Columbia Sportswear delivered its cleanest quarter in some time. Third-quarter EPS of $1.66 topped the $1.25 consensus and the $1.31 Earnings Whisper number by 26.7%. Revenue of $962.58 million beat the $938.12 million estimate by 2.6%. Earnings grew 17.7% year over year on 2.0% revenue growth. The result also cleared management's own $1.15-$1.35 guide by a wide margin, and sales landed about $25 million above a range that called for a decline of 1.5% to flat. The central tension is how much of the upside reflects real demand improvement and how much reflects shipment timing, tariff refunds and a shrinking share count. The honest answer is some of each, and the U.S. evidence is more encouraging than the headline alone suggests.
The quality of the beat deserves scrutiny. By management's account, roughly $20 million of the sales upside came from delayed Fall '26 wholesale orders shipping earlier than expected. That is revenue borrowed from the fourth quarter, not new demand. Reported gross margin slipped 20 basis points to 49.8%, as accommodations to factory partners outweighed the IEEPA tariff refund benefit. The call put underlying gross margin up 30 basis points. Operating leverage was more convincing: SG&A fell to $375.6 million from $380.9 million, and operating margin reached 11.4%. Below the line, EPS got extra help from two sources. The tax rate fell to 24.0% from 26.7%, and diluted shares dropped to roughly 50.9 million from 54.6 million after $200 million of buybacks this year. For context, the year-ago quarter's GAAP EPS of $0.95 included a $0.46 impairment hit.
The more meaningful change sits beneath the totals. U.S. sales fell just 1%, compared with declines of 4% in the second quarter and 10% in the first. Management described U.S. e-commerce as having inflected to mid-single-digit growth, with the Columbia brand up high single digits on reduced promotions. Columbia U.S. e-commerce had been down low single digits a quarter earlier. New-consumer growth was the strongest since 2023. DTC rose 5% while wholesale was flat. Internationally, Latin America/Asia Pacific grew 11% and EMEA grew 7%, with China accelerating to low-teens growth from mid-single digits. That is the first tangible evidence that the ACCELERATE brand repositioning is reaching younger consumers rather than merely costing money. The weak spots remain the smaller brands. Mountain Hardwear fell 17%, a reversal from 6% growth in the second quarter, and prAna slipped 1% after a 14% gain.
The outlook keeps the story moving but also explains why the reaction may be less straightforward than the surprise implies. Full-year EPS guidance moved to $4.65-$4.90, the fourth straight increase from a $3.20-$3.65 starting point, and sales guidance narrowed to growth of 2% to 3%. However, the high end did not move despite a Q3 result roughly $0.40 above the midpoint of guidance. That implies part of the beat was pulled from Q4. Fourth-quarter EPS guidance of $1.85-$2.10 appears to sit below Street expectations. Q4 sales growth of 3.5% to 7% includes roughly 2.5-3 points from the shipment shift, and the quarter remains weather-dependent. Operating cash flow guidance was cut to $230-$250 million from $290-$310 million because Spring '27 production was pulled forward. Inventory is up 11%, with units up 10%. The forward-looking positive is the Spring '27 order book, which improved to mid-single-digit growth, with U.S. wholesale leaning mid-single digits.
Bears still have legitimate ammunition for 2027. Gross margin must cycle an approximately 180-basis-point net tariff refund benefit. Those refunds added $0.85 to nine-month EPS. Management also flagged oil-driven input cost pressure later in the year and an increasingly competitive China market. Strip out the refunds, and full-year earnings growth looks far more modest than the guidance headline.
Investors were not leaning bullish into the print. Earnings Whispers sentiment swung from slightly positive at 0.03 to clearly negative at -0.25, a meaningful deterioration. Price action was more neutral. At $60.90, shares were down 1.4% since the open after the July report. They sat about 2% above the $59.68 200-day moving average and just 2.2% below the inter-earnings high of $62.25 set on October 22, having recovered nearly 11% from the September low. Trend readings are largely neutral, with AVWAP positive.
The bottom line is that Columbia produced the first credible evidence of a U.S. demand turn, supported by a better Spring book and an improving direct business. Still, much of the Q3 upside came from timing, tariff refunds and buybacks, and 2027 margins face real headwinds. Skeptical sentiment gives the company room to surprise. The burden now shifts to a weather-sensitive fourth quarter and to whether U.S. momentum can outlast the refund tailwind.
Read our earnings preview for Columbia Sportswear Company: https://www.earningswhispers.com/article/COLM/21176
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-21 | |
| Oct-15 | |
| Oct-07 | |
| Sep-14 | |
| Sep-10 | |
| Sep-08 | |
| Aug-18 | |
| Aug-17 | |
| Aug-05 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 |
