SPX Technologies Edges Whisper As Data Center Demand Surges, But HVAC Execution Costs Force First Profit-Guidance Trim
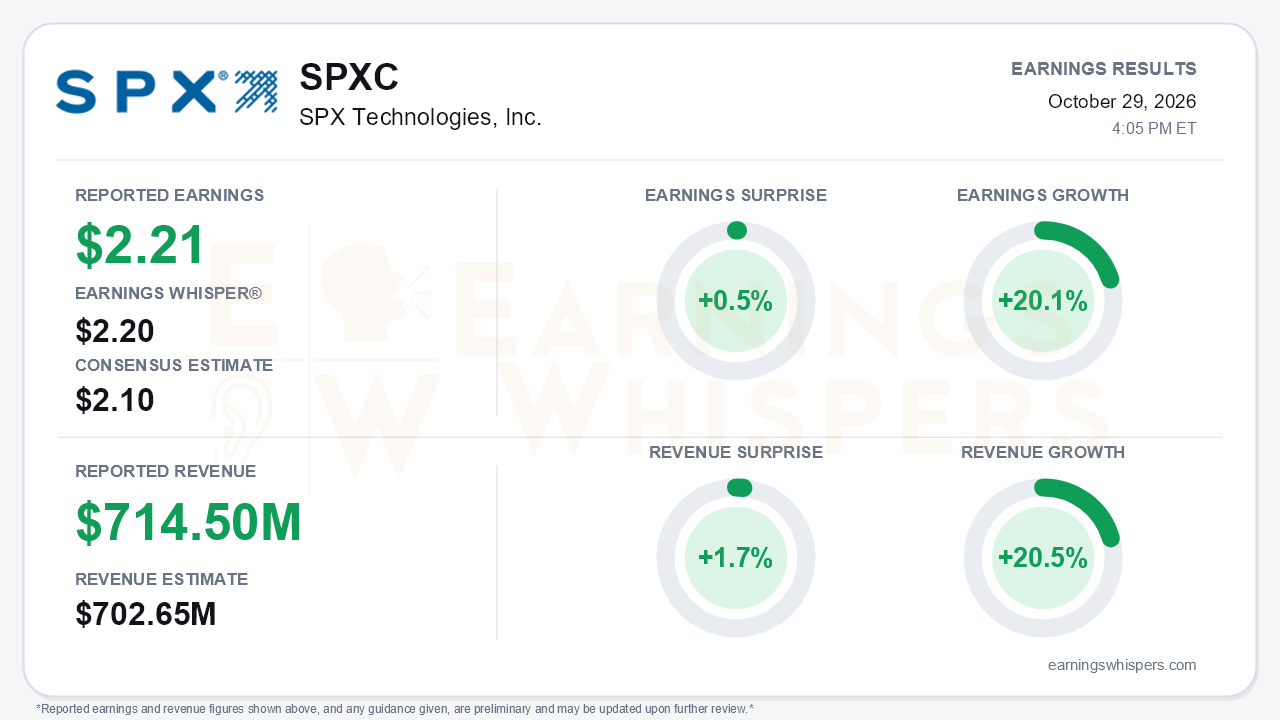
SPX Technologies (NYSE: SPXC) delivered a quarter that showed accelerating demand alongside deteriorating execution. Adjusted EPS of $2.21 topped the $2.10 consensus and edged past the $2.20 Earnings Whisper number, a 0.5% surprise. Earnings grew 20.1% year over year, and revenue rose 20.5% to $714.5 million, 1.7% above consensus. Management noted this was the company's fifth straight quarter of 20%-plus adjusted EPS growth. The more consequential news, however, was in the outlook. SPX raised its revenue guidance but lowered its adjusted EBITDA range to $625-$645 million (from $630-$660 million) and cut the top end of adjusted EPS guidance to $8.50, lowering the midpoint to $8.35 from $8.40. That is the central tension: SPX is winning more business than it can currently produce profitably.
The quality of the beat deserves scrutiny. Organic revenue growth was 11.8%. Acquisitions contributed 8.5 points of the 20.5% headline gain, and four 2026 deals have now absorbed roughly $1.2 billion. HVAC revenue jumped a record 35.5%, including 22.3% organic growth, but segment margin fell 140 basis points to 23.0%. SPX attributed the decline to labor and supply-chain inefficiencies tied to the volume ramp, plus elevated input costs. Detection & Measurement offset some of that weakness, with margin expanding 260 basis points to 27.8% even as revenue fell 7.7% on lower communications project volumes. Even that strength comes with an asterisk: management indicated that roughly 175 basis points of 2026 D&M margin stems from a one-time commercial resolution rather than structural improvement.
Cash generation weakened. Adjusted free cash flow fell to $23.1 million from $90.8 million a year ago, as capital expenditures nearly quadrupled to $40.0 million and inventories built further. Year-to-date adjusted free cash flow of $111 million trails last year's $164.2 million. Total debt climbed to $1.33 billion from $501.6 million at year-end after the FIS Water acquisition, and leverage rose to about 1.8x. That figure is manageable, but it is a meaningful step up from the 0.7x and 1.4x pro forma levels discussed last quarter.
The call preserved a credible growth story. Organic HVAC backlog reached about $1.1 billion, up 69% year over year and 15% sequentially from $919 million in Q2, continuing a steady climb from $585 million at the end of 2025. The 2026 data center revenue outlook rose again, to roughly $450-$460 million, after starting the year at $300 million. Management described demand as "increasing and accelerating" and signaled a bias toward a steeper 2027 ramp toward roughly $1.1 billion of annual data center capacity. Other positives included the start of shipments from the Madison, Alabama facility and early traction for a heat trace product launch. Management also suggested that D&M's 22-24% medium-term margin target is stale.
Bears have legitimate ammunition. Management quantified about $25 million of second-half cost pressure: roughly $15 million from labor turnover, lower productivity, and premium outsourced metal fabrication, and roughly $10 million from steel and diesel inflation that backlog pricing has not yet caught up with. The cut to HVAC margin guidance, from 24.5%-25.0% to 23.1%-23.5%, implies second-half HVAC margins near 24% rather than the roughly 26.5% previously embedded. Management also said these inefficiencies will persist into Q4 and partly into 2027. In addition, more than 90% of data center revenue is tied to hyperscalers, and management flagged softness in Aton's international business and in education, government, and new commercial markets.
The market had already turned skeptical before the report. Shares opened at $213.69 after the July report and briefly hit $236.89, but have since fallen 22.7% to $165.20. That leaves the stock about 20.5% below its 200-day moving average and only 6% above a 52-week low of $155.86 set on October 23. Investor sentiment, already slightly negative, deteriorated further from -0.107 to -0.185, a notable but not extreme shift. The Earnings Whispers trend readings are split: sequential growth and momentum remain positive, while price and AVWAP trends are negative. That split captures the disconnect between the operating trajectory and the stock's behavior.
The bottom line is that SPX's demand picture has rarely looked stronger, but the quarter revealed that scaling HVAC capacity is costing more than planned. The first profit-guidance trim of the year, weaker free cash flow, and higher leverage give investors reasons to question near-term margins, even as backlog and data center visibility keep improving. With the stock already sitting near its lows and sentiment soured, the debate now centers on whether these inefficiencies are temporary growing pains or a sign that margins will keep lagging volume into 2027.
Read our earnings preview for SPX Technologies, Inc.: https://www.earningswhispers.com/article/SPXC/21247
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-07 | |
| Sep-23 | |
| Sep-15 | |
| Aug-17 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 | |
| Jul-23 | |
| Jul-08 | |
| Jun-19 |
