Merit Medical Misses On Normalized EPS But Raises Guidance A Third Time As 9% Organic Growth Holds; Gross Margin Slippage Is The Crack
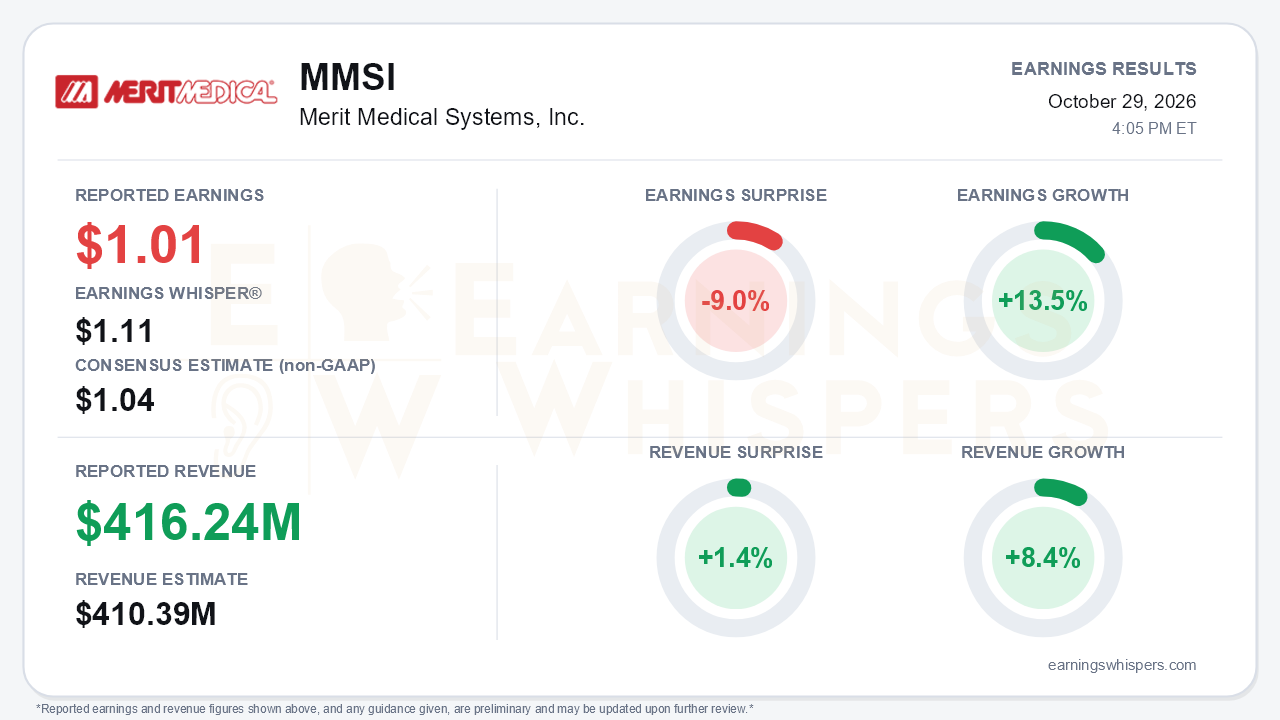
Merit Medical Systems delivered a quarter with two different headlines. On the Earnings Whispers normalized basis, the company earned $1.01 per share. That missed the $1.04 consensus and fell 9.0% short of the $1.11 Earnings Whisper number, though earnings still grew 13.5% year over year. Revenue was cleaner: $416.24 million beat the $410.39 million consensus by 1.4% and rose 8.4%. Management told a more triumphant story, reporting non-GAAP EPS of $1.12, up 22% and above its own $0.98 to $1.08 guide, and raising full-year EPS guidance for the third straight time. That is the central tension. The operating business is executing well above plan, but investors with whisper-level expectations were looking for a cleaner beat than the normalized figure delivered.
The gap between the two EPS figures deserves scrutiny. It is almost exactly the $0.11 per share of performance-based share compensation that Merit adds back in its non-GAAP reconciliation. That expense is a real and recurring cost of running the business. On a GAAP basis the picture is still strong: EPS rose 51% to $0.70, and GAAP operating margin widened to 14.1% from 11.1%. Non-GAAP operating margin of 21.3% expanded 160 basis points and landed at the top of guidance. The weaker spot is gross margin. Non-GAAP gross margin fell to 52.8% from 53.6%, a decline of about 81 basis points, after expanding roughly 98 basis points in the second quarter. Management cited platinum-related manufacturing variances, a bonus true-up and freight. Operating leverage, not product economics, carried the margin story this quarter.
The top line is where the quarter was most convincing. Organic constant-currency growth of roughly 9% matched the second quarter's pace and was far above the first quarter's 3.7% ex-divestiture rate. That makes this a sustained re-acceleration rather than a one-quarter blip.
- **U.S.:** revenue grew 11%.
- **Therapeutic:** organic growth of 11%, with endoscopy up 33% and oncology up 16% on pent-up ScoutMD demand.
- **OEM:** grew about 15% after a flat first half that included a 14% decline in the first quarter.
Not everything is pulling its weight. Procedural Solutions fell 16% and Renal Therapies slipped 2%. International grew only 3%, or 6% excluding China. Management trimmed its second-half China outlook by about $4 million, citing volume-based procurement and buy-local pressure.
Guidance moved in the right direction, but the raise was more about flow-through than a new forecast. Full-year non-GAAP EPS guidance rose to $4.33 to $4.37 from $4.25 to $4.35, a path that began at $4.01 to $4.15. Other updates:
- Organic constant-currency growth guidance moved to 7.1% to 7.6%.
- Full-year operating margin is now expected at 21.2% to 21.4%, versus 20.6% to 21.0% initially.
- Management expects cumulative free cash flow under its Continued Growth Initiative near $600 million, well ahead of the more-than-$400 million target.
The revenue range was raised mainly at the low end, so the implied fourth quarter decelerates to 7% to 8% organic against tougher comparisons. Bears have legitimate ammunition elsewhere too. Inventory is up roughly $60 million year to date, and year-to-date free cash flow of $129.5 million trails last year's $141.6 million. The Viewpoint/OneMark integration is running slower than hoped, Rhapsody faces stiff competition, and Section 232 tariff uncertainty lingers.
Forward catalysts are building. Management announced:
- The SoloPace acquisition, which brings Merit into TAVR temporary pacing. It is immaterial to 2026 and expected to be slightly accretive in 2027.
- A new Chief Operations Officer focused on working capital and operational execution.
- A February 11, 2027 investor day to unveil 2027 to 2029 targets.
Management also said a validated platinum alternative is ramping to address the gross-margin variance. That is the one fix the quarter most clearly needed.
The market had already priced in plenty of good news. Shares entered the report at $92.21, up 5.2% from the open after the July report and nearly 20% above the 200-day moving average. They sat just 2.8% below a 52-week high of $94.85 set three days earlier, near the top of an inter-earnings range that began at $82.77. Investor sentiment, by contrast, stayed slightly negative and was essentially unchanged, moving from -0.13 to -0.12. Earnings Whispers trend signals were uniformly positive heading in. With price this extended, a normalized miss against a $1.11 whisper matters more than it would have from a lower base.
The bottom line is that Merit's operating story improved again: organic growth held at 9%, operating margins expanded, and guidance rose for a third time. The quality of the earnings beat is less impressive than management's non-GAAP framing suggests, and gross margin moved the wrong way. With the stock near its highs and the fourth-quarter outlook implying deceleration, the platinum fix and the February investor day now carry much of the burden of extending the rally.
Read our earnings preview for Merit Medical Systems, Inc.: https://www.earningswhispers.com/article/MMSI/21219
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-06 | |
| Sep-04 | |
| Aug-19 | |
| Aug-05 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-02 | |
| May-19 | |
| May-08 |
