Rimini Street's Profitability Inflection Drives A Clear Beat, But Reaffirmed Guidance And Cooling RPO Growth Temper The Story
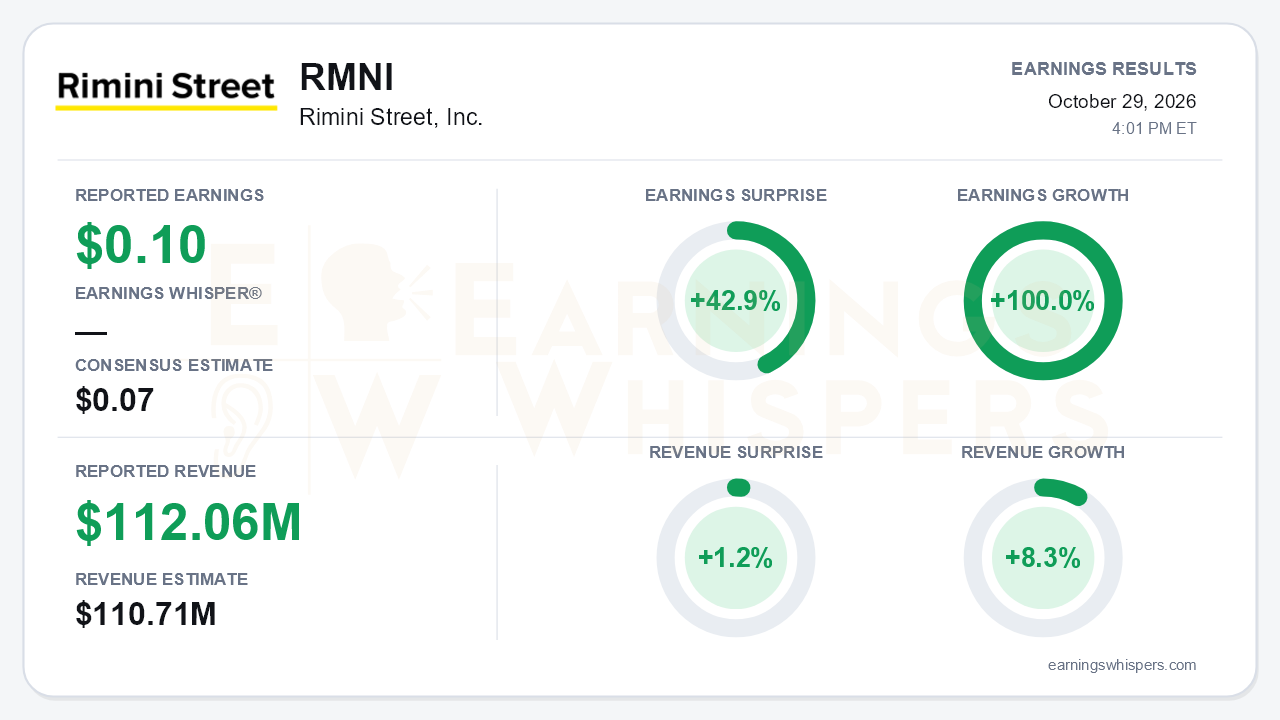
Rimini Street delivered its cleanest quarter in some time. Earnings of $0.10 per share beat the $0.07 consensus by 42.9% and were up 100.0% from a year ago. Revenue of $112.06 million topped the $110.71 million estimate by 1.2% and rose 8.3%, landing at the top of the company's $110 million to $112 million guidance range. The bigger development was margin, not the top line. Adjusted EBITDA rose 52% to $15.1 million, and the adjusted EBITDA margin reached 13.5%, up from 9.5% in the second quarter and 8.4% in the first. The central tension is that this operating inflection came alongside full-year guidance that was only reaffirmed and a forward-looking contract metric that keeps decelerating.
The quality of the beat holds up better than most. On a GAAP basis, net income more than doubled to $6.5 million, or $0.07 per diluted share, from $0.03. That gain came from real operating leverage rather than one-time items. Last year's nine-month comparison was inflated by a $36.2 million litigation settlement, but the third quarter carried no such benefit. GAAP gross margin improved to 61.4% from 59.9% a year ago and 60.9% last quarter. General and administrative expense fell in absolute dollars. Non-GAAP sales and marketing dropped to 34.4% of revenue from 37.6% in the second quarter, as first-half spending that had been pulled forward began to pay off. Revenue growth also accelerated for a third straight quarter. Reported growth moved from 1.2% to 6.7% to 8.3%. Excluding the PeopleSoft business being wound down, adjusted revenue grew 10.7%, the second consecutive double-digit quarter.
Beneath the headline, the demand indicators mostly improved. Calculated billings rose 21% to $80.5 million, a sharp reversal from an 8.8% decline in the second quarter. Adjusted ARR growth accelerated to 9.8% from 8.1%. Revenue retention reached 90%, meeting a goal management flagged earlier in the year. Large deals broadened, with 17 contracts above $1 million in total contract value worth $43.7 million, up from 14 in the second quarter and 11 in the first. Management cited record third-quarter SAP support sales and improving Oracle sales. CEO Seth Ravin pointed to five consecutive quarters of improving results, and the tone of the call was noticeably more confident.
Bears still have legitimate ammunition. Remaining performance obligations grew 6.8% to $652.9 million, or 7.4% excluding PeopleSoft. That is still a sequential gain, but year-over-year growth has slowed from 16.4% in the first quarter and 8% in the second. Several execution goals are also behind schedule:
- **Sales headcount:** The company has about 80 sellers, short of the early-90s target set earlier. Management is now emphasizing seller productivity over adding headcount.
- **Partner channel:** Partners remain a few quarters away from the goal of 40% of pipeline, with deals arriving in management's words as "onesies, twosies."
- **Agentic AI:** Management offered no revenue figures and acknowledged it lacks a good feel for the 2027 impact.
- **U.S. growth:** U.S. revenue grew only 4.3%, versus 11.6% internationally.
- **Pipeline:** Management described it as fairly similar in size, though improving in quality.
- **Cash:** Cash fell to $93.3 million from $123.4 million in the second quarter. Part of that reflects the seasonal drawdown of deferred revenue and $10 million spent on buybacks and debt prepayment, but the decline is worth monitoring.
Guidance is where the report may underwhelm. Management guided fourth-quarter revenue to $117 million to $119 million. It reiterated, rather than raised, its full-year "Rule of 20" framework of 4% to 6% revenue growth and a 12.5% to 15.5% adjusted EBITDA margin, despite outperforming year to date. The forward catalysts are real but mostly lie ahead:
- the Datacom reseller partnership in Australia and New Zealand;
- Rimini Govern for AI, now integrated with ServiceNow's AI Control Tower;
- survey evidence of VMware customers seeking alternatives;
- a January 14, 2027 Investor Day, where the fiscal 2027 plan will be presented.
Capital allocation is also tilting toward share repurchases, supported by $49.9 million in net cash.
The market setup is more complicated than the surprise implies. Investor sentiment fell from 0.40 to 0.04, essentially neutral and a meaningful cooling of enthusiasm. The stock has round-tripped badly. It reached a 52-week high of $5.68 on August 31, then slid to an inter-earnings low of $3.79 on October 28. It entered the report at $4.03, down 15.3% since the open after the prior report, 29.1% below that high and sitting right on its 200-day moving average. Most Earnings Whispers trend readings are neutral, with AVWAP still negative, consistent with a stock that has lost momentum despite improving fundamentals. Expectations were reset lower heading into the report, which gives a quarter of this caliber room to be reassessed.
The bottom line is that Rimini Street showed genuine operating leverage: accelerating adjusted revenue, a four-point jump in EBITDA margin and a billings rebound make this more than a cosmetic beat. Reaffirmed guidance, slowing RPO growth and sales-capacity goals that are behind plan keep the durability question open. The January Investor Day is likely where investors decide whether this quarter marks a turn or a peak.
Read our earnings preview for Rimini Street, Inc.: https://www.earningswhispers.com/article/RMNI/21239
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-19 | |
| Oct-13 | |
| Oct-06 | |
| Sep-14 | |
| Aug-31 | |
| Aug-12 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
