MVB Financial Misses Badly As A Land-Loan Credit Hit Buries Its Best Core Margin And Fintech Deposit Quarter
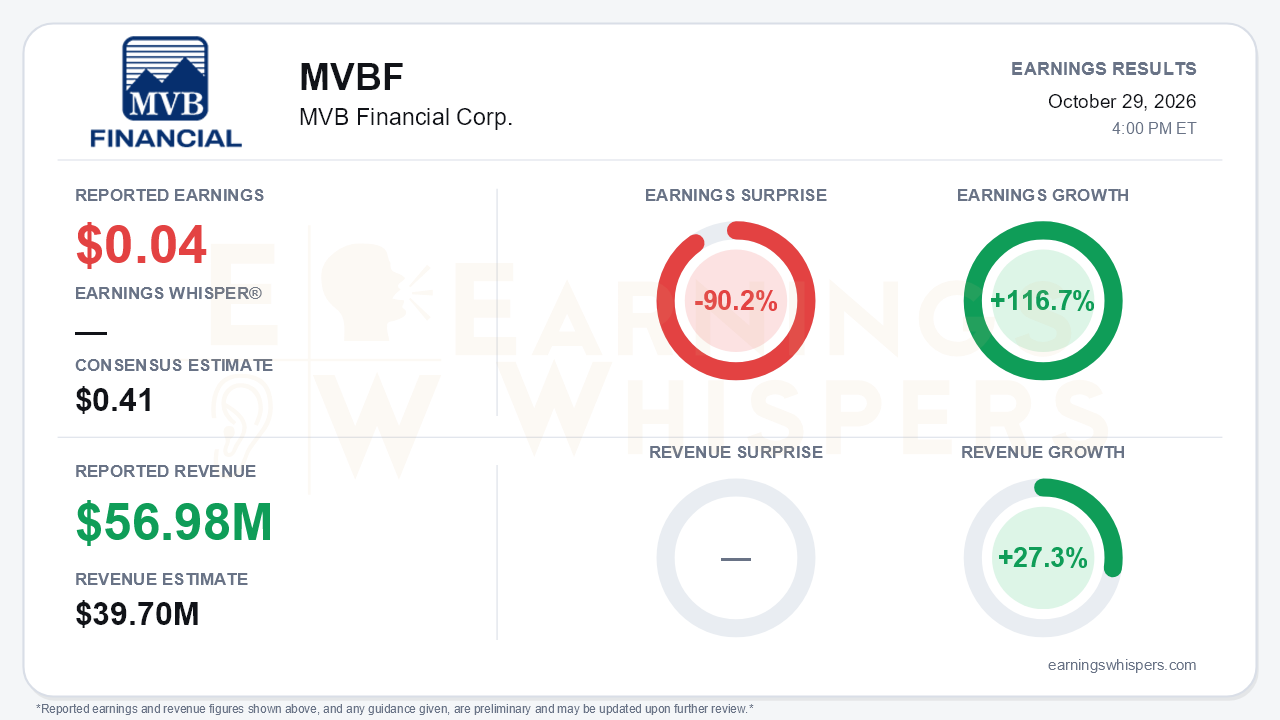
MVB Financial delivered a quarter in which the franchise improved while the income statement collapsed. Earnings Whispers puts reported EPS at $0.04 against a $0.41 consensus, a 90.2% miss, while revenue of $56.98 million beat the $39.7 million consensus by 43.5%. On GAAP terms, net income fell to $0.4 million, or $0.03 per diluted share, from $12.3 million, or $0.93, in the second quarter. The cause was a $9.9 million provision for credit losses, more than double the prior quarter's $4.7 million. That is the central tension: core net interest margin, funding costs and expenses all moved the right way, but credit consumed nearly all of pretax income, which fell to just $0.6 million.
The headline comparisons need careful reading. Earnings Whispers' normalized figures show EPS growth of 116.7% and revenue growth of 27.3% year over year. GAAP results tell a different story. Diluted EPS dropped from $1.32 in the year-ago quarter, but that period included a $34.1 million divestiture gain. The second quarter also carried a $10.0 million fintech investment gain and $2.3 million of nonrecurring interest income, which makes the sequential decline look worse than the core trend. The revenue beat also deserves scrutiny. Net interest income of $32.6 million plus $7.8 million of noninterest income is a much more modest picture than the headline revenue figure suggests. Excluding the prior-quarter gain, fee income still fell 10.5%. Management attributed the drop to seasonal gaming softness and weaker mortgage equity-method income tied to higher rates.
Beneath the noise, the operating trends were genuinely constructive:
- Core FTE net interest margin rose to 4.02% from 3.87% in the second quarter and 3.71% in the first, beating the call's earlier expectation for slower expansion.
- Cost of funds fell for a second straight quarter, to 2.07%.
- Fintech Payments deposits jumped 28% sequentially to $766 million, about a quarter of total deposits. Management is now targeting more than $1 billion.
- Nine fintech partners have been onboarded year to date, versus five in all of 2025, with 8 to 11 more expected in the fourth quarter.
- Noninterest expense fell to $29.8 million from $33.3 million a year ago.
- Risk and compliance headcount dropped to 81 from 116, already below the year-end target of 90, as the company scaled its AI "digital workers" to more than 100.
- Payment card income rose roughly 40% year over year.
Credit is where bears have legitimate ammunition. Nonperforming loans climbed to $46.8 million, or 1.9% of loans, from $29.2 million. Of the increase, $13.1 million came from a single acquisition-and-development land loan. On the call, management cited suspected misrepresentation in due diligence or the appraisal, and a forensic appraisal is underway. That loan alone drew a $4.6 million specific reserve. The legacy SBA book added $3.2 million in reserves, and roughly 53% of that $23 million portfolio is classified. Net charge-offs rose to 41 basis points from 23, and management guided to a similar level in the fourth quarter, so the elevated cost of credit is not presented as finished. Management's tone shifted from the second quarter's assertion that the credit profile had improved to a more defensive framing. It does point to criticized loans falling about 45% since early 2025 and an allowance that has risen to 1.44% of loans. Capital also softened: tangible book value per share fell to $25.26 from $26.52 on wider AOCI losses, and the TCE ratio slipped to 9.3%.
Loan growth is a second, quieter disappointment. Balances rose $43.8 million, a sixth consecutive quarterly gain, but at about 7.2% annualized the pace fell short of the $60 to $70 million per quarter guided after the second quarter. Noninterest-bearing deposits also declined $73.2 million, pushing the loan-to-deposit ratio to 81.6%. Looking ahead, management's 2027 priorities are a "margin optimization" effort to remix 6.5% to 7% loans into 8.5% to 9% specialty and fintech-sponsorship credits, and "prime capture" onboarding of established fintechs that generate revenue at launch. Both are credible margin levers, but both depend on underwriting discipline at the moment underwriting is under question.
The market entered the report without strong conviction either way. Investor sentiment edged from essentially neutral to slightly positive, a small change that signals no meaningful expectation shift. Shares closed at $29.64 the day before the release, down 2.8% since the open after the prior report. That left them 5.6% above the 200-day moving average, roughly midway between the $31.99 52-week high set on July 29 and the October 14 low of $28.22. Trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that MVB's core engine of margin, low-cost fintech funding and expense control strengthened meaningfully, but one apparently compromised land loan and lingering SBA problems turned the quarter into a near-breakeven print. Elevated charge-offs are guided to persist and loan growth missed the company's own target. Investors will need clean credit results before the fintech deposit story can earn full credit.
Read our earnings preview for MVB Financial Corp.: https://www.earningswhispers.com/article/MVBF/21224
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-15 | |
| Sep-25 | |
| Sep-15 | |
| Sep-09 | |
| Sep-01 | |
| Aug-19 | |
| Aug-06 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-15 |
