Twilio Beats And Raises Again, But Normalizing Upside And Slowing Messaging Complicate The Story
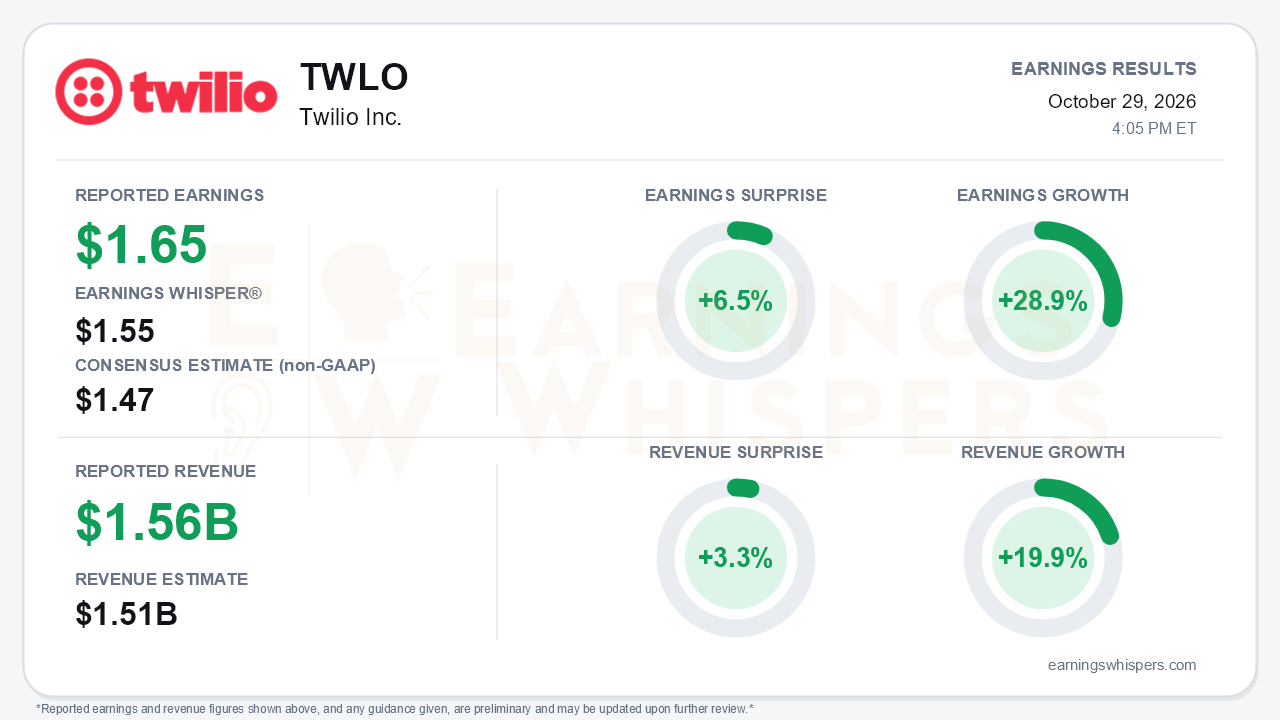
Twilio delivered another clean beat-and-raise quarter. Non-GAAP EPS of $1.65 topped the $1.47 consensus by 6.5% and cleared the $1.55 Earnings Whisper number. Earnings grew 28.9% from a year ago. Revenue of $1.56 billion beat the $1.51 billion consensus by 3.3% and rose 19.9%, with organic growth of 16%. Management raised full-year guidance for the fourth consecutive time and issued a preliminary 2027 outlook well above its Investor Day framework. That is the headline. The central tension is that the size of the upside is shrinking. Messaging, ISVs, and net expansion all softened sequentially, and the fourth-quarter guide implies a sharp organic slowdown. The story is still improving, but it is no longer accelerating on every line.
The quality of the quarter is largely solid. Non-GAAP operating income rose 39% to a record $326 million, lifting the margin to 21% from 18% a year ago and 19% in the second quarter. Free cash flow reached a record $370 million, a 24% margin, versus $248 million a year earlier. GAAP operating income more than tripled to $149 million, helped by flat operating expenses. Stock-based compensation fell to 9.9% of revenue from 12.2%. GAAP EPS of $1.00 compared with $0.23 and included a $22 million tax benefit. Investors should also note that year-to-date GAAP net income of $1.32 billion is inflated by a $937 million valuation-allowance release. Two blemishes deserve scrutiny. First, non-GAAP gross margin slipped to 49% from 50%. Second, about $53 million of reported revenue came from pass-through A2P carrier fees, which is why reported growth runs four points ahead of organic.
The call explained what changed beneath the surface. Organic messaging growth eased to 17% from 18%, and reported messaging growth fell to 24% from 28% as ISVs lapped tough comparisons. That matters because messaging is roughly 60% of revenue. ISV growth cooled to 20%-plus from 25%-plus. Dollar-based net expansion dipped to 114% from 116% last quarter, though it remains well above the 109% posted a year ago. Offsetting this, voice held above 20% growth and self-serve voice grew about 55%. Software add-ons grew 25%-plus, and the million-dollar customer cohort is expanding at its fastest pace in a long time. Management called the beat about four points, versus 5%-plus in each of the first two quarters, and characterized 2%-4% beats as the norm. In effect, management is telling investors to expect smaller upside going forward.
The forward catalysts are substantive. Management now guides 2026 organic growth to 15%, up from 8%-9% at the start of the year. Operating income and free cash flow guidance were raised to $1.19-$1.20 billion. The preliminary 2027 outlook calls for at least 10% organic growth, versus the 7%-8% framework, and at least $1.35 billion in operating income and free cash flow, up from $1.23 billion. Twilio also highlighted three newer developments:
- its first eight-figure Conversations deal, with a health insurer;
- an agent-identity product in private beta, targeting general availability in 2027 with software-like margins;
- engagement with all leading consumer-agent platforms, which management framed as an "AI super cycle."
The near-term guide is less exciting. Fourth-quarter organic growth of 11%-12% would be a steep step down from 16%. Gross profit growth is guided only in line as the email-migration tailwind fades and holiday hosting costs rise. Operating income of $300-$310 million sits below the third quarter, reflecting $11 million of one-time platform credits and new hires. Bulls can point out that the third-quarter organic guide was also 11%-12%, and Twilio delivered 16%. Bears can point to slow voice AI adoption in regulated industries, where penetration is only about 1% of voice minutes.
The market setup is more complicated than the surprise implies. Shares closed at $253.77 ahead of the report, up 7.9% since the open after the August release. They also sat 35.3% above the 200-day moving average. However, the stock had already retreated 17.7% from its $308.40 52-week high set on October 6. Investors had bid up the AI narrative and then partially unwound it before the print. Investor sentiment was essentially unchanged and barely positive, slipping from 0.0120 to 0.0111, so expectations were not euphoric. Sequential growth and momentum trend readings remain positive, while AVWAP is negative, consistent with the stock's pullback from its high.
The bottom line is that Twilio continues to out-execute its own targets, expanding margins, generating record cash, and lifting both 2026 and 2027 expectations. However, the easy upside is fading. Messaging and ISV growth are moderating, net expansion ticked lower, and management itself is resetting beat expectations. With the stock already well off its October peak, the debate shifts from whether Twilio can beat to whether its AI-driven demand vectors can offset a slowing core.
Read our earnings preview for Twilio Inc.: https://www.earningswhispers.com/article/TWLO/21254
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 11 hours | |
| 12 hours | |
| 14 hours | |
| 16 hours | |
| Oct-29 | |
| Oct-29 |
Twilio Earnings Top Estimates. Shares Fall On Slowing Organic Growth.
TWLO TWLO -15.24%
Investor's Business Daily
|
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 |
