West Bancorporation Meets EPS Estimates As Loan Growth Returns, But Its Margin Tailwind Is Fading
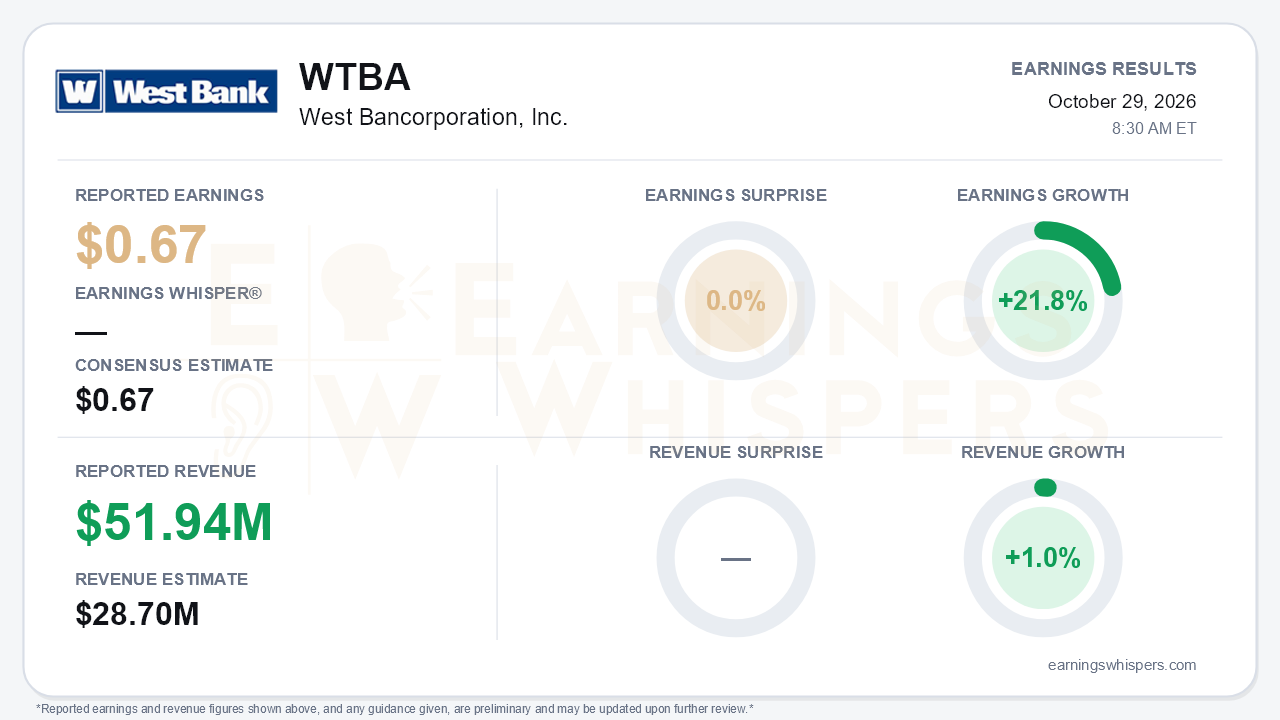
West Bancorporation delivered exactly what Wall Street expected in the third quarter: earnings of $0.67 per share, matching the $0.67 consensus and up 21.8% year over year. The more important story is that the quarter changed what drives the bank. For most of the past year, earnings growth came almost entirely from net interest margin expansion while loan balances stalled. This quarter loans grew for the first time in five quarters. At the same time, management signaled that the margin engine is losing power after the Federal Reserve's September rate hike. That handoff from margin-driven growth to volume-driven growth is the central tension.
The reported revenue figure needs context. Earnings Whispers shows revenue of $51.94 million against a $28.7 million consensus, an 81.0% surprise, with revenue up 1.0% year over year. That revenue figure appears to combine gross interest income ($49.2 million) and fee income. Net interest income plus noninterest income was roughly $29.1 million. The apparent blowout therefore looks like a difference in how revenue is defined, not genuine operating outperformance.
On a like-for-like basis, the quarter was solid but not spectacular:
- Net interest income rose to $26.4 million from $25.5 million in Q2 and $22.5 million a year ago.
- Net income of $11.6 million continued a steady climb from $10.6 million in Q1 and $11.1 million in Q2.
- Return on average equity reached 16.41%.
- The efficiency ratio improved to 47.81% from 54.06% a year earlier.
- Credit remains pristine, with no nonaccrual loans, a ninth straight quarter-end with nothing more than 30 days past due, and the watch list down to 0.6% of loans from 1.7% at the end of 2025.
- The board also nudged the quarterly dividend up to $0.26 from $0.25.
The growth rate, however, is decelerating. Year-over-year net income growth slowed to 25% from 35% in Q1 and 39% in Q2. Margin gains are shrinking each quarter: +12 basis points in Q1, +10 in Q2, and +8 in Q3 to a 2.77% net interest margin. Management now expects further slowing because the bank's high-beta deposit base will reprice upward with the Fed's move. This is a reversal from the Q2 call, when the CEO anticipated lower short-term rates. Deposit costs turned higher by 3 basis points after several quarters of declines, and management described deposit competition as "really intense."
The balance sheet shows that pressure clearly:
- Non-brokered deposits fell $65.8 million in the quarter, led by a roughly $70 million drop in interest-bearing demand accounts.
- The bank funded loan growth and paid down $60 million of FHLB advances largely by drawing down interest-earning cash, which fell from $260.6 million to $88.8 million.
- The loan-to-deposit ratio climbed to 91.6% from 88.2%.
The offset is a more constructive loan outlook. Loans grew 1.5% sequentially. Known Q4 payoffs fall to about $30 million from roughly $90 million entering Q3, and management called the pipeline robust, citing large closings across Des Moines, Iowa City, and Minnesota. Repricing also remains a tailwind: about $550 million of fixed-rate loans at roughly 4.5% will reprice over the next year, while new production is coming on in the high-6% range. That pool has shrunk from around $600 million last quarter, though.
Other risks are building:
- Technology and product spending is slated to rise in 2027-2028.
- The effective tax rate is creeping higher.
- Asset-sale payoffs will continue into 2027.
- The watch list is concentrated in transportation.
- Book value per share fell to $15.94 from $16.49 as the accumulated other comprehensive loss widened to $84.0 million, a direct cost of the rate reversal on the securities portfolio.
The market has rewarded the earnings trajectory anyway. Shares have gained 12.9% since the open after the July report to $30.04, about 15.3% above the 200-day moving average. Investor sentiment moved the other way. It was already negative and slipped further, from -0.26 to -0.35, a modest but noticeable deterioration. That gap suggests investors are skeptical that the margin-led earnings run can continue at this pace, even as the stock trades at a higher multiple of a shrinking book value. Most Earnings Whispers trend readings remain positive, though sequential growth is only neutral, fitting a business still improving but no longer accelerating.
The bottom line is that West Bancorporation's in-line quarter was cleaner than the headline suggests, with stronger profitability, spotless credit, and a long-awaited return to loan growth. But the easy part of the earnings recovery is ending. The rate hike, rising deposit costs, and weaker core deposit flows mean future gains must come from loan volume and repricing rather than margin expansion. After a double-digit rally and with sentiment souring, the burden of proof now rests on that pipeline converting into sustained balance-sheet growth.
Read our earnings preview for West Bancorporation, Inc.: https://www.earningswhispers.com/article/WTBA/21153
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-21 | |
| Sep-18 | |
| Jul-23 | |
| Jun-19 | |
| Apr-23 | |
| Mar-20 | |
| Feb-20 | |
| Feb-20 | |
| Feb-17 | |
| Feb-12 | |
| Feb-12 | |
| Feb-03 | |
| Feb-03 |
