Grid Dynamics Delivers A Margin Step-Change And Accelerating Growth, But A Flat Q4 Guide And Slowing AI Growth Temper The Story
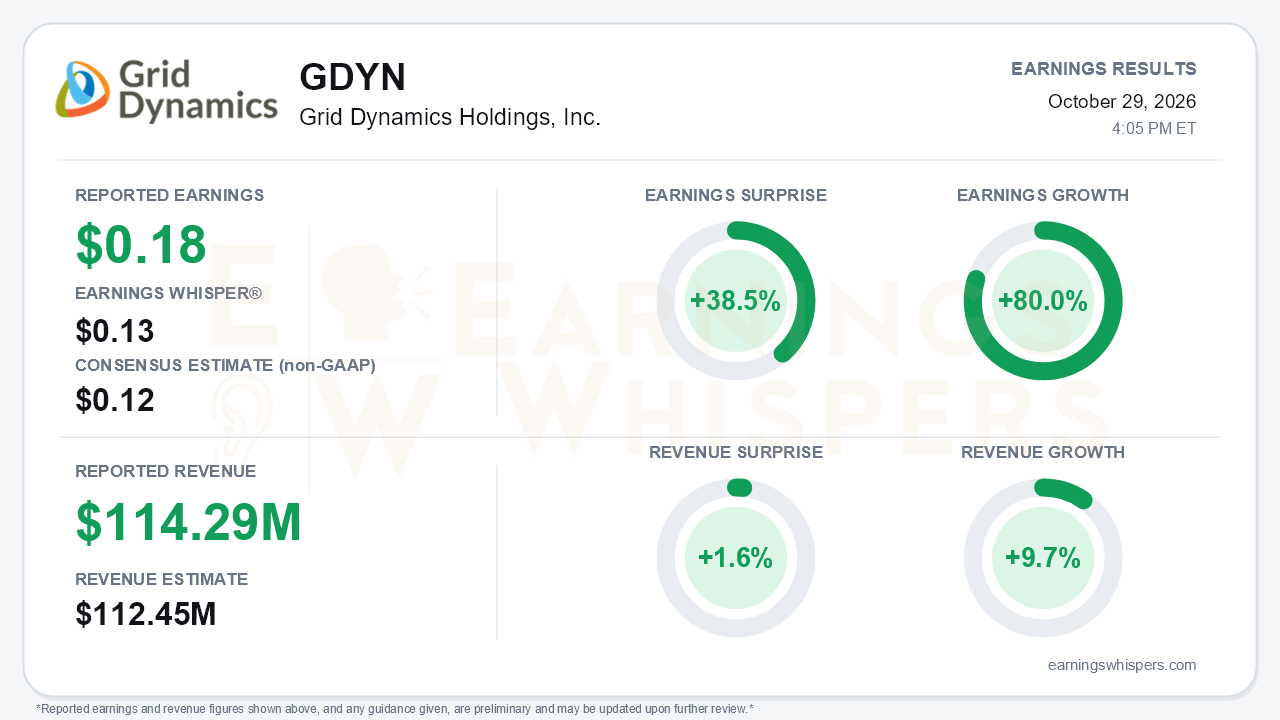
Grid Dynamics' third quarter was more about profitability than the top line. The company reported non-GAAP earnings of $0.18 per share. That beat the $0.12 consensus by 38.5% and cleared the $0.13 Earnings Whisper number, with earnings up 80.0% year over year. Revenue of $114.29 million topped the $112.45 million consensus by 1.6% and exceeded the high end of management's own $112.0 to $114.0 million guidance. Revenue growth of 9.7% year over year was the third straight quarter of acceleration, up from 3.7% in Q1 and 7% in Q2. The central development, though, was the margin reset. Non-GAAP EBITDA nearly doubled to $22.9 million, a 20.0% margin, against guidance of $16.5 to $17.5 million and a 13.6% margin just one quarter earlier.
The beat largely reflects operating improvement rather than below-the-line help. Non-GAAP gross margin jumped to 40.6%, from 36.9% in Q2 and 33.8% a year ago. On a GAAP basis, the company swung from a small operating loss of $0.2 million to $9.1 million of operating income, and GAAP EPS rose to $0.08 from $0.01. That happened even as other income fell and a heavy tax provision of $5.2 million absorbed nearly half of pretax income. The engine is efficiency. Headcount fell to 4,559 from 4,971 a year ago, mostly in non-engineering roles, while revenue grew nearly 10%. Revenue per employee crossed $100,000.
The quality of the beat still deserves some scrutiny. Restructuring costs of $2.0 million, more than double last year's level, were excluded from non-GAAP results. Management acknowledged that Q3 margins benefited from working days. Cash generation has also not kept pace with EBITDA. Operating cash flow for the first nine months was $30.5 million, essentially flat with last year, as accounts receivable climbed to $84.7 million from $71.3 million at year-end. Cash fell to $304.3 million from $342.1 million in December, reflecting $35.5 million of year-to-date buybacks and acquisition activity.
Demand looked healthy beneath the headline. TMT, now 32.3% of revenue, grew 29.3% year over year. Retail swung to 13.3% growth from flat in Q2, and top-10 customers grew 8.6% sequentially. The call also added several positive developments:
- AI revenue reached 31% of the total in the release, while call commentary cited roughly 32%.
- The company won a Cisco Partner of the Year award and a large AI-native fixed-price project.
- Contract durations are lengthening.
- Management, for the first time, framed 2027 as a return to "healthy double-digit growth."
Management also called roughly 20% EBITDA margins a "new norm," having beaten its 300-basis-point expansion commitment a quarter early.
Bears still have legitimate ammunition. AI revenue growth has slowed from roughly 60% in Q1 to 54.6% in Q2 and 45% in Q3. That remains strong, but the deceleration matters for a company marketing itself as an AI transformation partner. Q4 revenue guidance of $113.5 to $115.5 million sits above estimates but implies roughly flat sequential growth after Q3's 5.7% gain. Management did not restate the $435 to $465 million full-year outlook it had reaffirmed on three prior calls, and year-to-date results plus the Q4 midpoint imply about $441 million, near the low end. The Q4 EBITDA guide of $20 to $22 million points to margins of roughly 18% to 19%, a step down from Q3, and Q1 is seasonally the weakest margin quarter. Customer concentration is also rising, with the top five clients at 45.4% of revenue versus 40.1% a year ago. Finally, management's stated appetite for larger acquisitions in 2027, plus ongoing investment in robotics and cybersecurity, adds both upside optionality and execution risk.
The market had already started to price in the improvement. Shares stood at $9.49 at the time of the report, up 40.6% from the $6.75 opening after the July release and roughly 36.5% above the 200-day moving average of $6.95. Price and AVWAP trend readings are positive, consistent with that advance. Investor sentiment improved meaningfully, from -0.17 to roughly -0.01, but it remains essentially neutral rather than enthusiastic. The stock has re-rated faster than sentiment has warmed, which leaves less room for disappointment if Q4 growth stalls.
The bottom line is that Grid Dynamics delivered a genuine operating inflection. Growth accelerated, margins stepped up sharply, and management offered its first constructive 2027 framing. A flat Q4 revenue guide, slowing AI growth, rising concentration and soft cash conversion mean the next leg depends on proving that 20% margins and double-digit growth can coexist. That test is more demanding now that the shares have already rallied sharply.
Read our earnings preview for Grid Dynamics Holdings, Inc.: https://www.earningswhispers.com/article/GDYN/21199
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Sep-29 | |
| Sep-23 | |
| Sep-04 | |
| Aug-26 | |
| Aug-19 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-16 |
