SkyWest Misses As Prorate Fuel Forces Another EPS Cut And A Flat 2027, While A Depreciation Change Props Up The Quarter
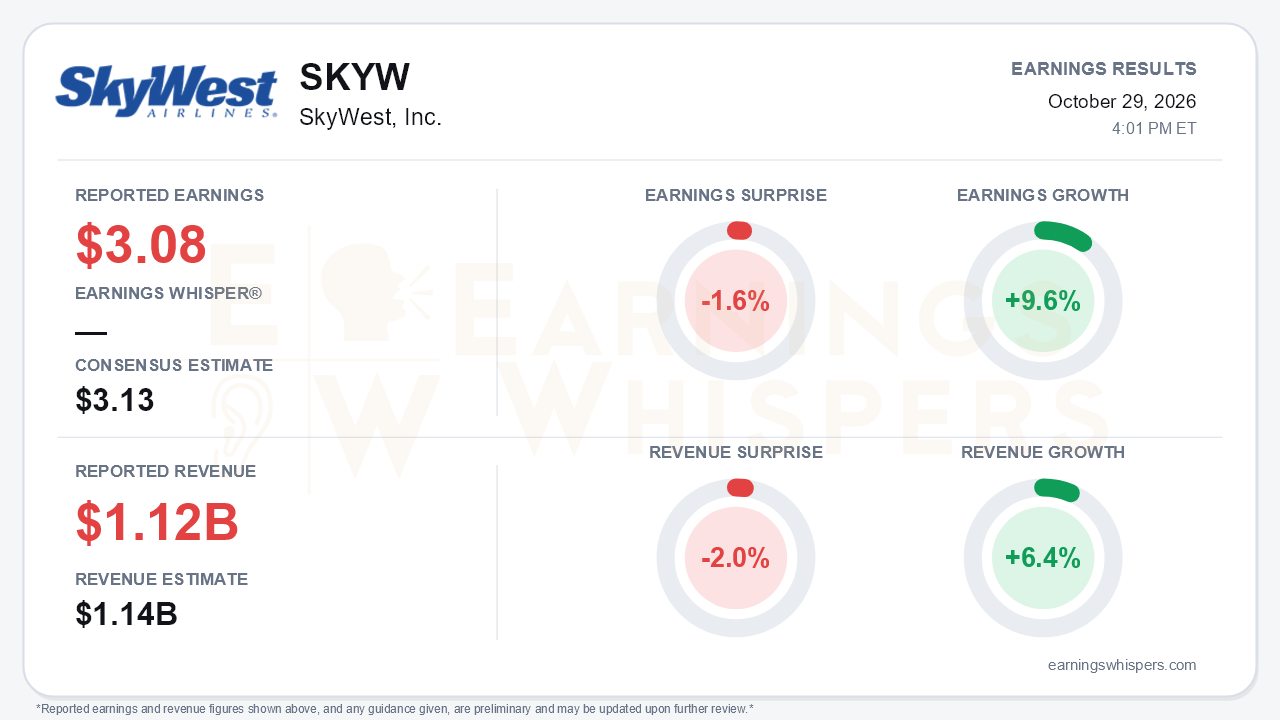
SkyWest (NASDAQ: SKYW) reported third-quarter earnings of $3.08 per share on revenue of $1.117 billion. That fell short of the $3.13 consensus by 1.6% and missed the $1.14 billion revenue estimate by 2.0%. On the surface the quarter looks respectable: earnings grew 9.6% year over year, revenue rose 6.4%, and EPS improved sharply from $2.54 in the second quarter. The more important development was on the call. Management trimmed its 2026 EPS outlook again and offered a first look at 2027 that calls for flat earnings on minimal capacity growth. That combination of a modest miss, softer guidance, and a stalled growth outlook is the central tension in an otherwise steady operating quarter.
The quality of the reported growth deserves scrutiny. Pre-tax income was $159 million, barely above $157 million a year ago. Most of the per-share gain came from two sources: a lower share count, with diluted shares down to 38.8 million from 41.4 million after continued buybacks, and an accounting change. SkyWest extended the estimated useful life of its E175 fleet from 22 to 30 years. That cut depreciation to $76 million from $92 million, roughly a $16 million benefit in the quarter. Without that change, pre-tax income would have been below the year-ago level. Fuel expense in the prorate business nearly doubled to $66 million from $34 million, and lease and other revenue declined. Earnings quality was also flattered by non-cash deferred revenue: SkyWest recognized $23.5 million more revenue than it received in fixed cash payments, up from $17.1 million a year earlier.
Operationally, the core contract-flying engine kept working. Block hours rose 4.5%, CRJ550 and CRJ900 flying grew sharply, and adjusted completion held at 99.9%. The softer details were in passenger metrics. Passengers carried fell 3.6% and load factor slipped three points to 81.0%. The bigger shift was management's view of fuel. Prorate fuel ran $4.56 per gallon in the third quarter against the $3.65 assumed in the prior guidance, a roughly $0.26 EPS hit, and the fourth quarter now assumes $4.90. Management previously said fare increases offset about 60% of fuel. Now it concedes SkyWest will not fully offset the cost and treats elevated fuel as an extended condition rather than a temporary one. As a result, prorate expansion is effectively paused, with management promising to be "patient" about adding aircraft.
The guidance trajectory tells the story. The 2026 EPS outlook has stepped down from the mid-$11s at the start of the year to about $11 in the first half and now about $10.60. The 2027 outlook includes:
- block hours up just 1-2%, versus roughly 5% this year;
- EPS flat with 2026;
- deferred revenue recognition falling to about $70 million from about $100 million, a non-cash headwind of roughly $0.60 per share;
- a tax rate rising to 25-27%;
- capital spending climbing to about $825 million.
That 2027 outlook came in below the mid-single-digit growth some analysts had floated. Further pressure comes from CRJ450 conversions taking three to four lines out of service and 20 CRJ700s that lack contracts.
The longer-term catalysts remain intact. SkyWest expects 18 E175 deliveries in 2027, up from 13 this year, which would take the fleet past 300, with the full block-hour and cash benefit landing in 2028. The first CRJ450 enters United service before year-end, against a reiterated opportunity of about 100 aircraft. Management also noted that each $1 move in fuel is worth about $1.20 of EPS, so relief at the pump would provide meaningful upside. The financing side is tightening, though. Cash fell to $569 million from $707 million at year-end as the company spent $75 million on buybacks during the quarter alongside heavy aircraft spending.
Investor sentiment remained negative and weakened slightly, moving from -0.17 to -0.19. Expectations were already guarded heading into the report. Shares at $96.54 are down 3.5% since the opening after the July report and sit just 0.5% above the 200-day moving average of $96.06, effectively on that line. The Earnings Whispers price and AVWAP trends are both negative, consistent with a stock that has drifted lower as the fuel narrative worsened.
The bottom line is that SkyWest's contract model continues to deliver stable production, but the headline growth was engineered partly through accounting and buybacks, and the forward picture has dimmed. Repeated EPS cuts, a flat 2027, and a fuel-driven pause in prorate growth push the E175 growth payoff out to 2028. Until fuel eases or new contracts fill idle aircraft, bears have legitimate ammunition.
Read our earnings preview for SkyWest, Inc.: https://www.earningswhispers.com/article/SKYW/21243
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-05 | |
| Jul-24 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-09 | |
| Jul-06 | |
| Jul-03 | |
| Jul-02 | |
| Jul-02 | |
| Jul-02 |
