CarParts.com Returns To Revenue Growth, But A Sequential EBITDA Slide And A Dropped Cash-Flow Target Temper The 'Offense' Pivot
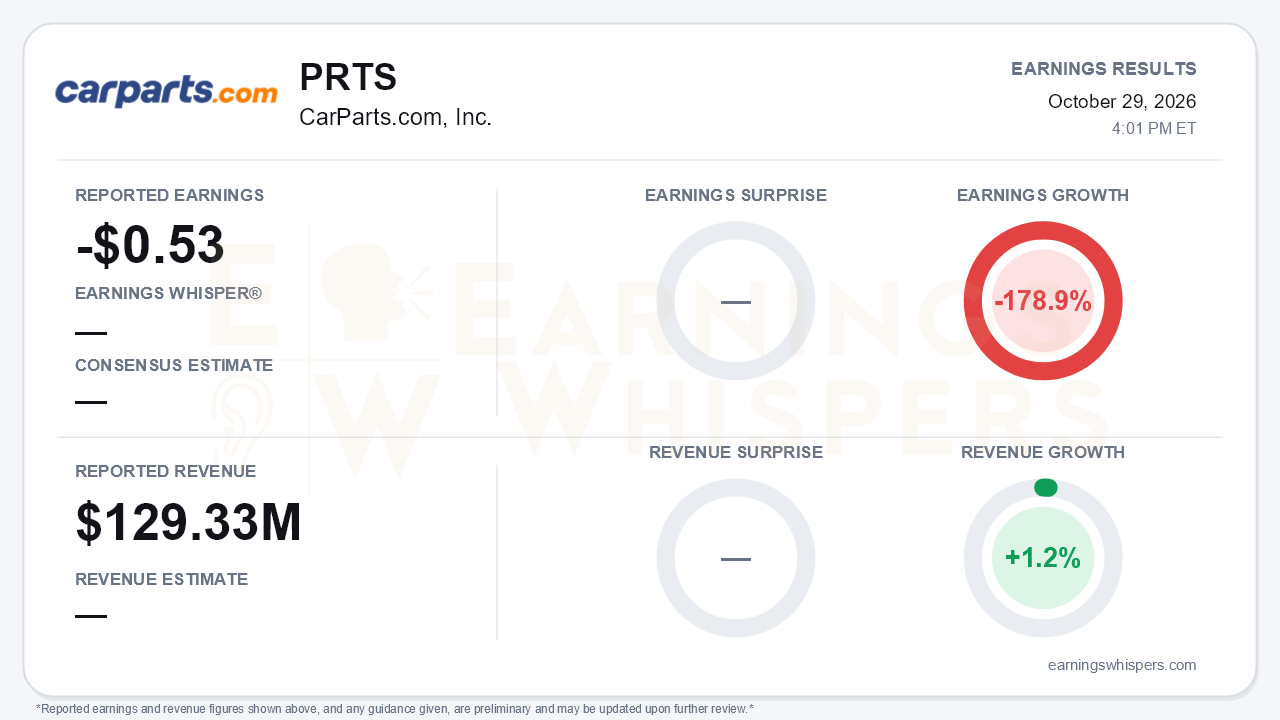
CarParts.com (NASDAQ: PRTS) used its third quarter to declare its restructuring largely complete and turn toward growth, and the top line supported that claim. Net sales rose 1.2% year over year to $129.33 million. That is the first year-over-year increase after declines of roughly 10% in each of the first two quarters. The earnings line is harder to read. Earnings Whispers' normalized comparison shows a loss of $0.53 per share and a 178.9% year-over-year decline in earnings. The company's own split-adjusted figures tell a different story: the per-share loss narrowed from $1.87, and the dollar net loss shrank by $6.8 million to $4.1 million. A 10-for-1 reverse split in May and a jump in weighted shares from 5.8 million to 7.7 million make per-share comparisons unusually noisy. In dollar terms, the loss clearly narrowed. No consensus figures were available, so there is no beat or miss to evaluate. The more important question is whether the improvement is still compounding. On that point, the quarter was mixed.
Most of the year-over-year improvement came from cost removal rather than sales leverage. Operating expenses fell to $47.0 million from $52.3 million, helped by distribution center consolidation, more efficient advertising and headcount cuts. Gross margin edged up 30 basis points to 33.4% on lower freight. That continues a steady climb from 32.5% in Q1 and 33.2% in Q2. Adjusted EBITDA swung to a $1.0 million profit from a $2.5 million loss. Management stressed that this was the third straight positive quarter and called the gains "structural, not one-time."
The quality of the quarter deserves scrutiny, however. Adjusted EBITDA fell sequentially from $1.8 million in Q2. That ended a run of sequential improvement management had highlighted on the prior call, and the framing shifted to "three consecutive positive quarters." Revenue also slipped sequentially from $135.6 million. The call disclosed a $1.4 million tariff-refund benefit in Q3, down from $2.2 million in Q2, and indicated that this tailwind is largely exhausted. That benefit is larger than the quarter's entire adjusted EBITDA. Management also said freight remains elevated despite the year-over-year relief, so the margin cushion going forward looks thin.
The call's operating metrics were genuinely constructive. The A-Premium drop-ship partnership exited the quarter at a roughly $55 million annualized run rate. That is above the $50 million marker and up from about $35 million at the end of fiscal 2025. Own-channel mix rose to 73% from 69% in Q1, and mobile app share reached 14.5%. Last-mile volume doubled again to more than 6,000 packages, with next-day delivery live at three of four distribution centers and Chicago targeted for Q4. Inventory fell to $77 million from $95 million at year-end. Management tied that drop to capital-light partnerships supporting the same or greater revenue. New growth levers include:
- the CarParts+ Rewards loyalty program, with more than 200,000 members enrolled;
- a Klarna buy-now-pay-later partnership at checkout.
Bears have legitimate ammunition in what management did not repeat. The free-cash-flow-positive-in-2026 target had been stated on each of the prior three calls but was not restated. JC Whitney's run rate reached only about $3 million. That falls well short of the Q2 expectation that it would roughly triple near term. The exit-2026 goal softened to "at or approaching" $7.5 million, and the $25 million medium-term figure went unmentioned. A record week at a roughly $5 million annualized pace after the Amazon SKU count doubled to 15,000 offers some hope. Even so, the trajectory has clearly reset lower. Cash fell to $33.8 million from about $38 million in Q2. Year-to-date operating cash flow of $10.0 million leaned heavily on an $18.3 million inventory release, and the balance sheet also benefited from $8.0 million in equity proceeds. Other soft spots include:
- retention-channel share slipped to 9.6% from 10.5%;
- consumers remain selective;
- the CFO role is still interim.
Market context is limited this quarter. No current sentiment reading or post-report price was supplied. Shares opened at $5.95 after the August report, well above the 200-day moving average, which now sits at $4.13. That gap suggests the stock had some cushion entering this print. It is not possible to judge how much of it remains without a current price.
The bottom line is that CarParts.com delivered the revenue inflection and the partnership milestones it promised, and its cost base is fundamentally leaner than a year ago. But profitability went backward sequentially, a fading tariff-refund tailwind flatters the thin EBITDA, and management quietly stepped back from its free-cash-flow and JC Whitney ambitions. The growth narrative is credible. The proof now has to come from EBITDA and cash generation rather than run-rate markers.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-13 | |
| Oct-08 | |
| Sep-25 | |
| Aug-06 | |
| Aug-04 | |
| Jul-28 | |
| Jun-16 | |
| Jun-09 | |
| May-28 | |
| May-07 | |
| Apr-16 | |
| Apr-14 |
