GoDaddy Beats As Airo Turns Accretive, But Buybacks Do The Heavy Lifting While Margin And Core Growth Soften
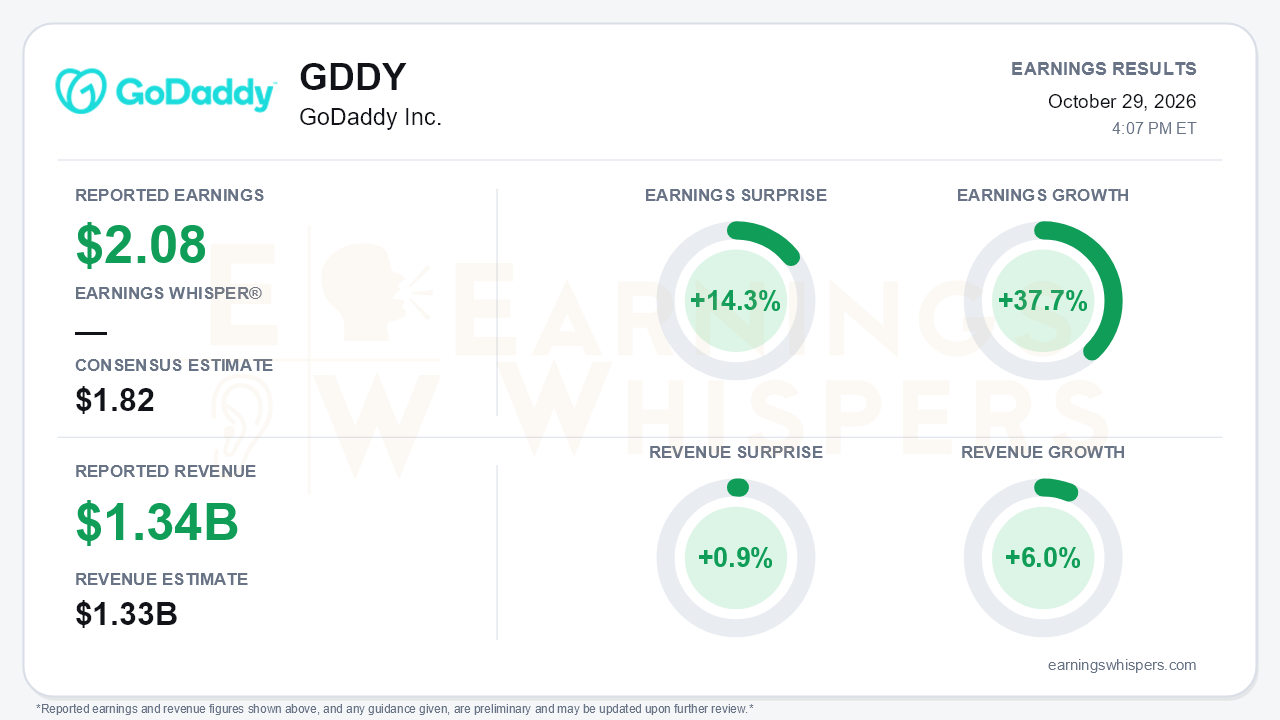
GoDaddy delivered a clean headline beat for the third quarter. It reported earnings of $2.08 per share against a $1.82 consensus, a 14.3% surprise, on revenue of $1.342 billion versus the $1.33 billion estimate. Earnings grew 37.7% year over year, while revenue rose a far more modest 6.0%. That gap is the central tension. The bottom line is expanding much faster than the business, and the call explained why. GoDaddy has repurchased $1.4 billion of stock year to date, cutting its share count 12%, up from 7% at the second-quarter report. Per-share earnings are being amplified by financial engineering at a moment when several operating growth rates are cooling.
The quality of the beat deserves scrutiny. The press release itself was only a pointer to materials on the investor relations site, so the operating detail comes almost entirely from the call. The supplied data also does not specify the EPS basis. Normalized EBITDA margin improved about 120 basis points to roughly 33%, ahead of the ~33% guide. However, normalized EBITDA growth slowed to 10% from 14% in Q2 and 13% in Q1. Free cash flow growth decelerated to 9% from 13% and 15% over the same span. Trailing twelve-month free cash flow still climbed to $1.8 billion from $1.73 billion, with $481 million generated in the quarter. Management also reframed its free cash flow 'North Star' as a three-year CAGR above 25%, up from a 20% target. The cash machine is intact. It is simply growing more slowly, and the share count is doing more of the work.
The genuinely new development is Airo, the company's AI-driven small-business platform. Its annualized bookings run rate doubled to more than $100 million, from about $50 million in Q2 and $10 million in Q1. Management said Airo became incremental to total bookings sooner than expected, more than offsetting migration away from legacy Websites + Marketing. That is a notable reversal. In Q2, management flagged roughly a one-point bookings headwind from legacy products and declined to give a crossover timetable. Airo became the default option in the domains purchase path, the company's largest funnel, in late Q3 and is already attaching better than the product it replaces. More than 70% of new Airo customers add a second paid product. Several related metrics improved:
- ARPU rose to $253 from $250 and $246 over the prior two quarters.
- Applications and Commerce bookings growth improved to 8% from 7%.
- Agent-friendly APIs expanded from domains into hosting, email and commerce.
The softer numbers sit underneath. Core platform bookings growth slipped to 4% from 5%. International revenue growth dropped sharply to 3% from 8%, which management tied to aftermarket mix. Applications and Commerce revenue growth eased to 9% from 12% in Q1. Gross margin ticked down, and the CFO explicitly guided to further erosion, because Airo's inference costs keep its margins below Websites + Marketing even as they improve through 2027. Management also flagged other new pressures:
- Sharper industry discounting in domains.
- Freemium hosting offers from AI-native and developer channels.
- Email seat reductions.
- Incremental Q4 marketing spend behind Airo.
The company is responding with new competitive bundles in 2027 and testing open-weight models in its own data centers to contain inference costs. Bears have legitimate ammunition here: Airo's success arrives with lower price points, cannibalization risk, and structurally thinner gross margins.
Guidance tilted constructive. Management now expects full-year revenue toward the high end of $5.215–$5.255 billion and reaffirmed its above-33% normalized EBITDA margin target and roughly $1.8 billion in free cash flow. It also expects Q4 bookings to accelerate and run slightly ahead of revenue. That is a forward signal worth watching, since bookings lead revenue. The December 1 Investor Night is the next obvious catalyst for longer-range targets.
The market setup is more complicated than the surprise implies. Shares have rallied 37.8% since opening at $76.83 after the July report, closing at $105.89, about 15.1% above the 200-day moving average. Price and AVWAP trend readings are both positive. Investor sentiment, however, remained firmly negative and weakened slightly, from -0.48 to -0.51. The stock has rerated sharply while investors stay skeptical. Expectations embedded in the price are now higher than the negative sentiment suggests, which makes the gross-margin and discounting commentary more consequential.
The bottom line is that GoDaddy produced a beat-and-raise quarter with a credible new growth engine, as Airo crossed from cannibalizer to contributor ahead of schedule. Yet the 37.7% earnings growth overstates underlying momentum. EBITDA and free cash flow growth are decelerating, core and international growth are slowing, and gross margin is set to compress further. With the stock well above its 200-day average after a near-40% run, Q4 bookings acceleration and the Investor Night targets now need to carry the story.
Read our earnings preview for GoDaddy Inc.: https://www.earningswhispers.com/article/GDDY/21198
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-25 | |
| Oct-23 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 |
