Grab Must Prove Its Raised Outlook Holds As Shares Slide Toward Range Lows
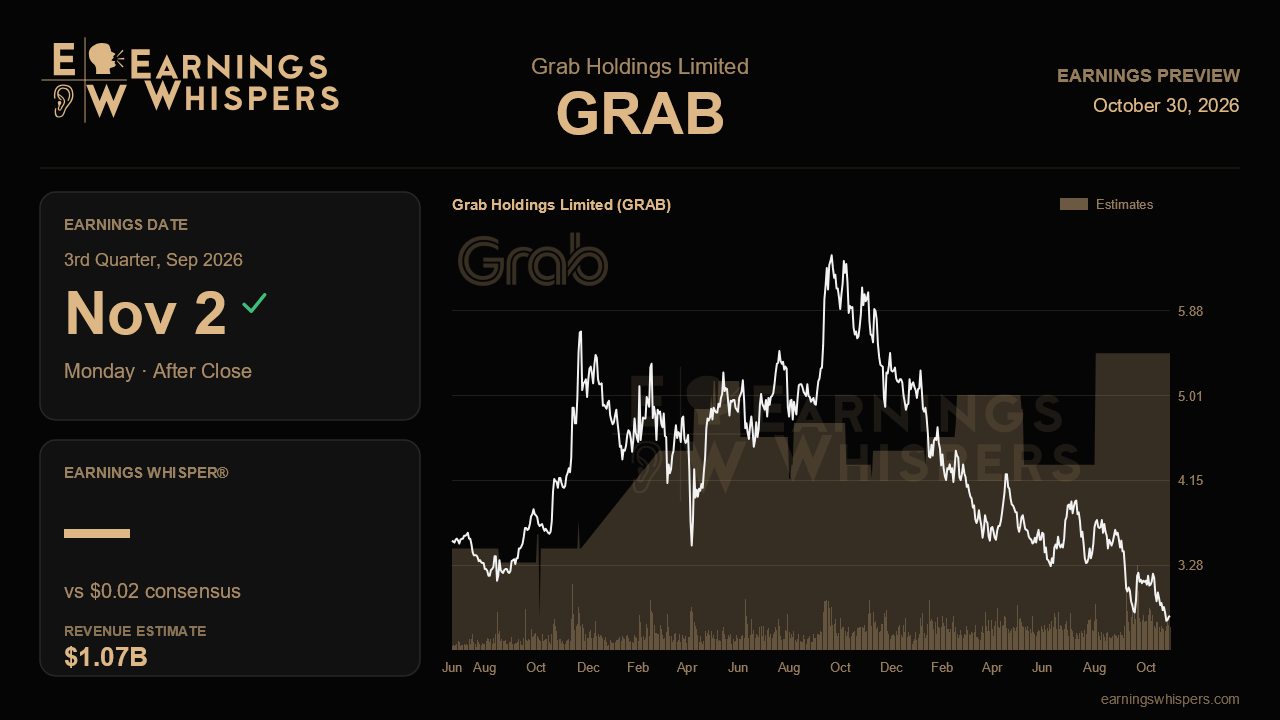
Grab heads into its third-quarter report with an awkward disconnect. Three months ago management delivered its most confident quarter in years, posting record adjusted EBITDA, raising full-year guidance for the first time in 2026 and expanding its buyback. The stock has since fallen about 22%, trailing the S&P 500 by roughly 25 percentage points. Either the market sees cracks the company has not yet acknowledged, or the shares are pricing in risks that the upcoming numbers could ease. The release after the close on November 2 should show which view is closer to the truth.
The Street is looking for earnings of about $0.02 per share on revenue near $1.07 billion. The revenue figure implies growth of roughly 23% from $873 million a year ago, an acceleration from the pace Grab has been running, though part of that lift reflects the consolidation of Superbank and Stash rather than purely organic momentum. The per-share estimate doubles last year's penny but sits well below the prior quarter's $0.06. That gap is a reminder that Grab's GAAP line remains thin and noisy, so adjusted EBITDA and segment trends will matter more than the headline profit figure.
The core test is whether the second-quarter narrative carries into the back half. Adjusted EBITDA reached $168 million last quarter, up 54% from a year earlier, its 18th straight quarter of growth, and margins widened to 16.9% of revenue from 13.3%. A sequential rise from that level, with margins holding near or above that mark, would support the raised outlook. Management also attributed demand to volume rather than price, citing record monthly transacting users of 54 million and deliveries growth that sped up to 24% in constant currency, with GrabMart outpacing food. Continued user gains and steady deliveries growth would show that the engine still has momentum.
Financial services may be the most important checkpoint. Grab has promised since 2022 that the segment would reach adjusted EBITDA breakeven in the second half of 2026, and this quarter is the first opportunity to show it. Management also raised its year-end loan book target to more than $3 billion from above $2 billion, so loan growth on that path, without a jump in credit costs, would add credibility. Any slip in the breakeven timeline after four years of commitment would carry a heavy reputational cost.
The weak spot is mobility. Last quarter mobility revenue rose only 12% even as gross merchandise value climbed 18% and transactions 28%, as saver products, smaller average tickets, driver incentives and fuel support squeezed the take rate. Segment margin landed at 8.6%, near the bottom of the 8.5% to 9% target range. With fuel prices still high, a 2% to 3% currency drag built into guidance, and Indonesian commission changes that took effect in July, a dip below that range would challenge the notion that these pressures are under control. Updates on the Foodpanda Taiwan deal, competitive pressure tied to Uber and Delivery Hero, and the Punggol autonomous service planned for the fourth quarter will add context.
Sentiment has edged up to modestly bullish from neutral before the last report, but the chart tells a gloomier story. At $2.76, the stock trades about 24% below its 200-day moving average and just above its post-earnings low of $2.67, well beneath the $3.18 floor of the prior quarter's range. That leaves room for relief if results are clean, and little support if they are not. Ultimately, the report comes down to whether Grab can show financial services breaking even and mobility margins holding inside their range. If both happen, the raised outlook looks intact and the selloff looks overdone. If either falters, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Sep-22 | |
| Sep-21 | |
| Sep-15 | |
| Sep-15 | |
| Sep-09 | |
| Aug-11 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| May-26 | |
| May-21 |
