Priority Technology's Rally Meets A Margin Test As Payables Profitability Faces Scrutiny
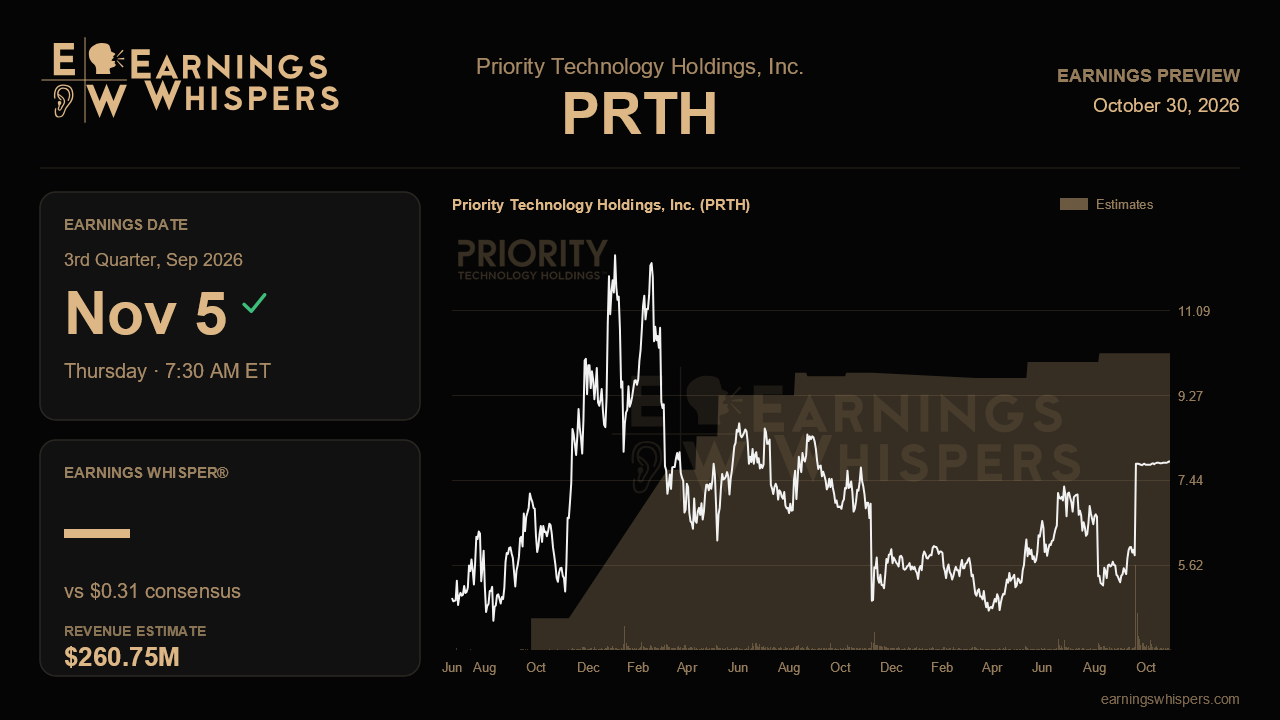
Priority Technology heads into its third-quarter report with an unusual split between what the stock has done and what management last said about profits. Shares have climbed nearly 22% since the second-quarter release, while the S&P 500 went nowhere. That call, however, was the first time this year that management steered gross profit and adjusted EBITDA toward the low end of their full-year ranges. The upcoming release, due before the open on November 5, needs to show that the margin squeeze in payables was a mix-driven pause and not the start of a longer erosion.
The Street's bar is moderate. Consensus calls for earnings of $0.31 a share, up about 10.7% from a year ago, on revenue of $260.8 million, up 8.0%. That would be a slight step down from the 9.4% growth posted last quarter, and revenue is modeled a bit below the $262.3 million delivered in the second quarter. Management reaffirmed 2026 revenue guidance of $1.01 billion to $1.04 billion and said it was tracking toward the high end. With full-year consensus at $1.03 billion, analysts sit comfortably inside the range but below where the company pointed. That leaves room for a top-line beat if the growth engines hold up. The larger risk sits further down the income statement, against gross profit guidance of $405 million to $425 million and adjusted EBITDA guidance of $230 million to $245 million.
Payables is the segment that will decide the tone. Last quarter its gross margin fell to 21.4%, down 760 basis points from a year earlier, and segment adjusted EBITDA dropped 17.5%. That was a sharp turn from gains of more than 50% in the prior two quarters. Management gave three reasons: a heavier mix of buyer-funded volume, which is booked on a gross revenue basis; lower starting margins on large new enterprise clients; and higher Visa and Mastercard interchange costs. The first two explanations imply margins should firm as volume matures. The interchange piece is more structural. A stabilizing payables margin would support the mix argument. Another decline of similar size would suggest pricing power is weaker than management described, especially as payables revenue growth already slowed to 21.6% from 35.6%.
Treasury deserves almost as much attention, since it and payables produce about two-thirds of adjusted gross profit. Treasury margin slipped to 88.5%, and CFTPay enrollments fell as partners pulled back on marketing. Any rebound in enrollments, or continued growth in billed clients past 1.1 million, would ease concerns that the high-margin engine is cooling. In merchant acquiring, organic growth improved to 4.5% from 3.9%, helped by firmer construction and restaurant activity. Holding or extending that recovery would give the revenue outlook a steadier base. Early traction from the new sports franchise deals and the expanding automotive dealer endorsements would add credibility to the enterprise growth story.
The stock's setup adds pressure. Shares at $7.85 sit essentially at their post-earnings high of $7.86 and well above the 200-day average near $6.07, so the stock is testing a breakout. Sentiment has moved in the other direction, with bearish readings rising to about 66% from roughly 47% before the last report. The unresolved special committee review of a take-private proposal makes the picture harder to read, since it is unclear how much of the rally reflects operating confidence rather than deal considerations. Further deleveraging below 3.8 times and another solid free cash flow quarter would strengthen the fundamental case either way.
Ultimately, this report hinges on whether Priority can keep growing revenue at the high end of its guidance without margins sliding further. If payables and treasury margins stabilize and management sounds firmer on its profit ranges, the low-end framing from August starts to look conservative. If margins erode again or the profit outlook slips below those ranges, a stock trading at its highs leaves little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-18 | |
| Oct-13 | |
| Oct-12 | |
| Sep-25 | |
| Sep-21 | |
| Sep-21 | |
| Sep-21 | |
| Sep-21 |
Priority Technology CEO to Take Firm Private in $1.6 Billion Deal
PRTH +33.79%
The Wall Street Journal
|
| Sep-21 | |
| Aug-26 | |
| Aug-26 |
