SandRidge Faces First Test Of Cherokee Bolt-On As Street Braces For Softer Oil Prices
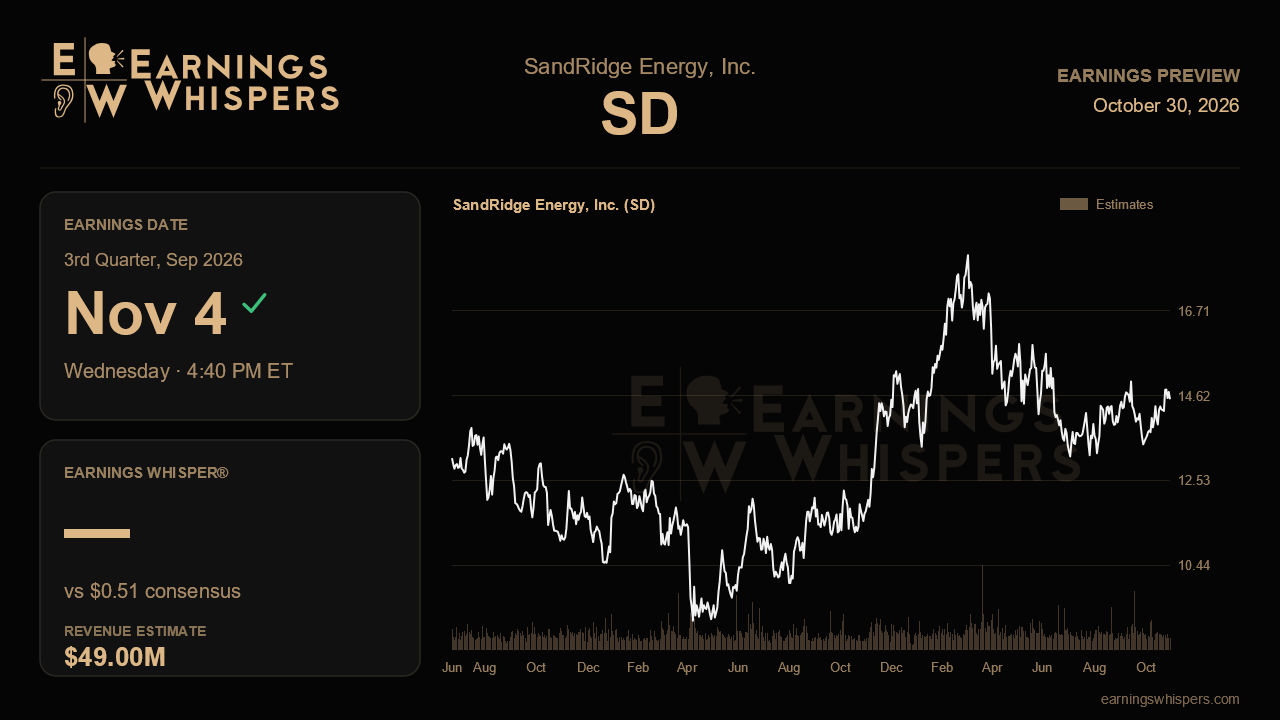
SandRidge Energy enters its third-quarter report with an unusual setup: the company should be bigger than it was three months ago, yet Wall Street expects it to earn less. The Cherokee bolt-on announced in late June was slated to close during the quarter. Production set a record at 19.7 thousand barrels of oil equivalent per day last time. Even so, consensus calls for EPS of $0.51 and revenue of $49.0 million, both below the $0.57 and $51.1 million the company posted in the second quarter. That gap tells you the Street is assuming the extraordinary oil pricing behind last quarter's numbers will not repeat, and that the debate is really about how much new barrels can offset softer realizations.
On a year-over-year basis the picture still looks healthy. The estimates imply roughly 21% EPS growth from $0.42 and about 23% revenue growth from $39.8 million a year ago, which is strong expansion for a debt-free producer that funds its drilling and dividend from cash flow. Management did not issue fresh numerical targets beyond reaffirming its 2026 capital budget of $76 million to $97 million and its well program, so there is no explicit guidance range against which to measure consensus. The notable point is that the plan was held steady rather than raised, even with the acquisition and record volumes in hand.
The most important evidence this quarter will come from production. The acquired acreage brought interests in 21 wells with an average 30-day initial rate of about 2,100 barrels of oil equivalent per day, 58% of it oil. If the deal closed on schedule, investors should expect a visible step-up in both total and oil volumes, and management's commentary on how those wells are declining after their early rates will matter as much as the headline figure. A sequential volume gain that merely matches the acquisition, with no help from the organic program, would suggest the base is softening underneath. The company also flagged that one of its ten 2026 completions is slipping into next year, so updates on well timing and the fourth well's record drilling speed and cost will show whether execution is staying sharp.
The gas side is the clearest swing factor. Realized natural gas prices collapsed to $1.36 per thousand cubic feet from $3.13 the prior quarter as regional basis differentials widened, and Henry Hub was weakening as well. That backdrop makes the exciting new Cherokee sub-member well, which produced more than 1 Bcf in its first 100 days, more of a long-dated option than a near-term earnings driver. Any sign that differentials have narrowed would be a welcome surprise, while further deterioration would challenge the stacked-pay development case. On costs, lease operating expense fell to $5.73 per barrel of equivalent last quarter; holding near that level despite persistent diesel surcharges would validate the efficiency narrative.
The market has already given SandRidge some credit. Shares are up 8.8% since the last report while the S&P 500 was flat, and sentiment sits at a moderately bullish 45.4%. Still, at $14.53 the stock trades just below its 200-day moving average of $14.95 and roughly 5% under its post-earnings high of $15.25, so it is in the middle of its range rather than pressing toward a breakout. Updates on cash, which reached about $115 million, and capital returns after last quarter's 8% dividend increase and special payout will also shape the reaction.
Ultimately this report needs to show that SandRidge's growth is structural rather than a byproduct of a price spike. If acquisition volumes arrive as advertised, oil mix keeps rising and unit costs hold, the company can absorb lower realizations and keep its improving story intact. If volumes disappoint while gas pricing stays depressed, the reaffirmed rather than raised guidance from last quarter will look less like caution and more like a ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Sep-11 | |
| Aug-06 | |
| Aug-05 | |
| Aug-03 | |
| Jul-31 | |
| Jul-23 | |
| Jul-08 | |
| Jun-29 | |
| May-21 | |
| May-06 | |
| May-05 | |
| Apr-13 | |
| Mar-19 |
