Gran Tierra's Q3 Report Tests Whether Strong Cash Flow Survives Its Latin America Exit
Gran Tierra Energy heads into its third-quarter report as a company in mid-transformation. Last quarter it delivered its cleanest set of numbers in some time and, almost in the same breath, agreed to sell its entire Colombia and Ecuador business to Morrill and Prom, pivoting toward Canada and Azerbaijan. That leaves investors weighing two things in the November 5 release after the close. The first is whether the operating momentum from the spring carried into the summer. The second is whether the company can start to describe what it will look like once its main producing assets are gone.
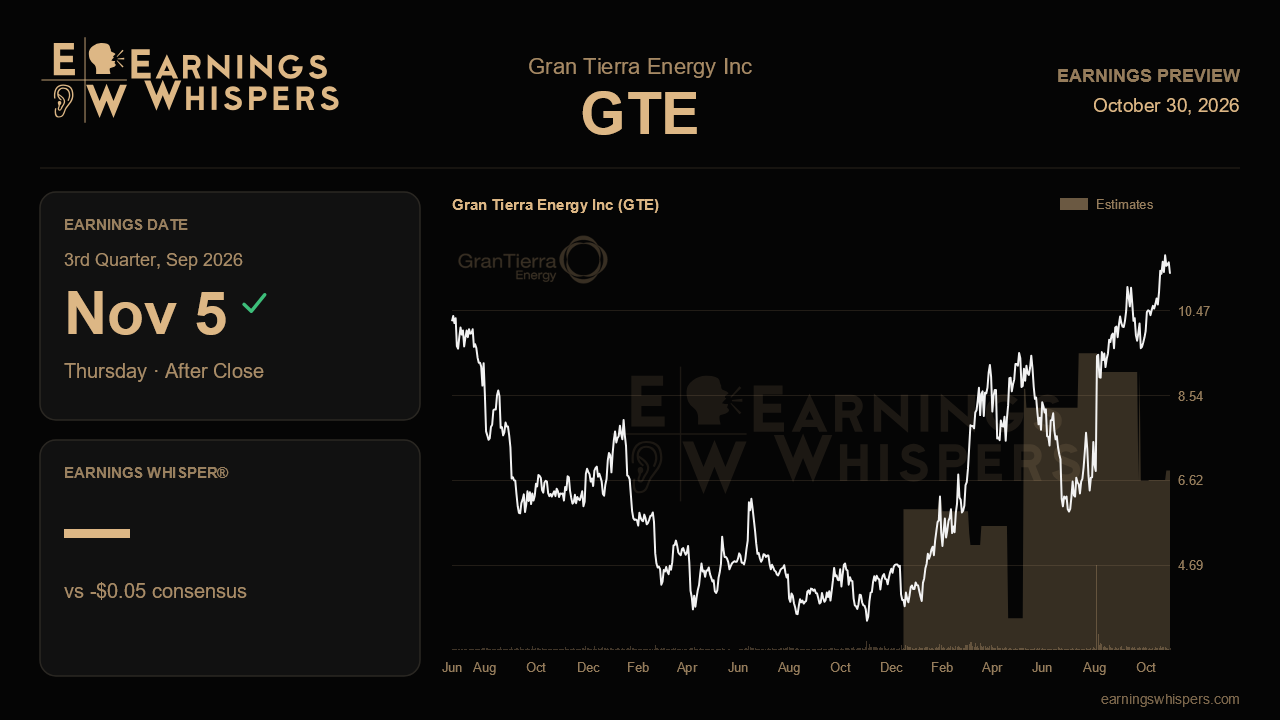
The Street is not expecting much on the bottom line. Consensus calls for a loss of about $0.05 per share. That would be a big improvement on the $0.30 loss from a year ago, which is where the projected 83% growth figure comes from. It would also be a sharp step back from last quarter's $0.70 profit. There is no formal guidance to measure that estimate against. Management largely held its prior framework, keeping capital spending within its earlier range and production inside the annual band, and declined to give post-transaction G&A or 2027 targets. Analysts are therefore working from a moving baseline, and a small loss may reflect caution about volumes and deal-related noise more than any loss of confidence in the core assets.
Production is the operating number that matters most. Output fell to roughly 41,500 barrels per day in the second quarter, down 9% sequentially. Part of that drop came from Canadian asset sales and part from unplanned artificial-lift failures at Acordionero and Cohembe. Management described those failures as temporary, so this report should show whether volumes recovered once the pumps were fixed. Ecuador, which slipped below 8,000 barrels per day, is another checkpoint. The completion of the $123 million Soriente carry in mid-July should also start to improve the economics there. A rebound in volumes alongside steady operating costs would support the view that last quarter's 22% drop in expenses was structural rather than a one-off. Another quarter of declines would undercut it.
Cash generation and the balance sheet are the other key tests. Funds flow reached $1.70 per share last quarter and free cash flow turned positive at about $6 million. Capital spending was weighted to the first half, so lower third-quarter capex should help free cash flow even if volumes stay flat. Management also accelerated debt reduction, buying back $50 million face value of 2031 notes at a 10% discount after the quarter ended. Further buybacks would reinforce the deleveraging story. The persistent risk is pricing. The Colombia-Ecuador border remains closed, forcing alternative transport routes with wider quality and transport discounts. That could offset some of the strength seen in Ecuador's realized pricing, which ran above Brent last quarter.
The market has already leaned into the bullish case. Shares are up about 9.5% since the last report, while the S&P 500 is slightly down over the same period. At $11.31, the stock sits well above its 200-day moving average near $8.21. It trades in the upper part of a post-earnings range of $8.49 to $11.94, a much higher band than the $5.65 to $9.63 range of the prior quarter. Sentiment has improved too, rising to 27.7% bullish from 11.2% heading into the last report. That is a meaningfully more optimistic backdrop, which means investors may be less forgiving of operational slippage.
Ultimately, the quarter will be judged less on the penny-level EPS result than on clarity. Investors want progress on the special stockholder vote and the deal timeline, an update on Tiscarama field work and the Azerbaijan gravity survey, and the first credible outline of the cost structure that remains after the sale. If production recovers and management starts to show how Canada and Azerbaijan can support the cash flow investors have come to expect, the improving narrative holds. If it doesn't, a rally built on the promise of transformation could struggle to find its next leg.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Oct-29 | |
| Oct-09 | |
| Oct-05 | |
| Sep-23 | |
| Sep-22 | |
| Sep-11 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-31 | |
| Jul-28 |
