Viasat Must Show Its Defense Backlog Can Outrun Commercial Erosion As Growth Expectations Rise
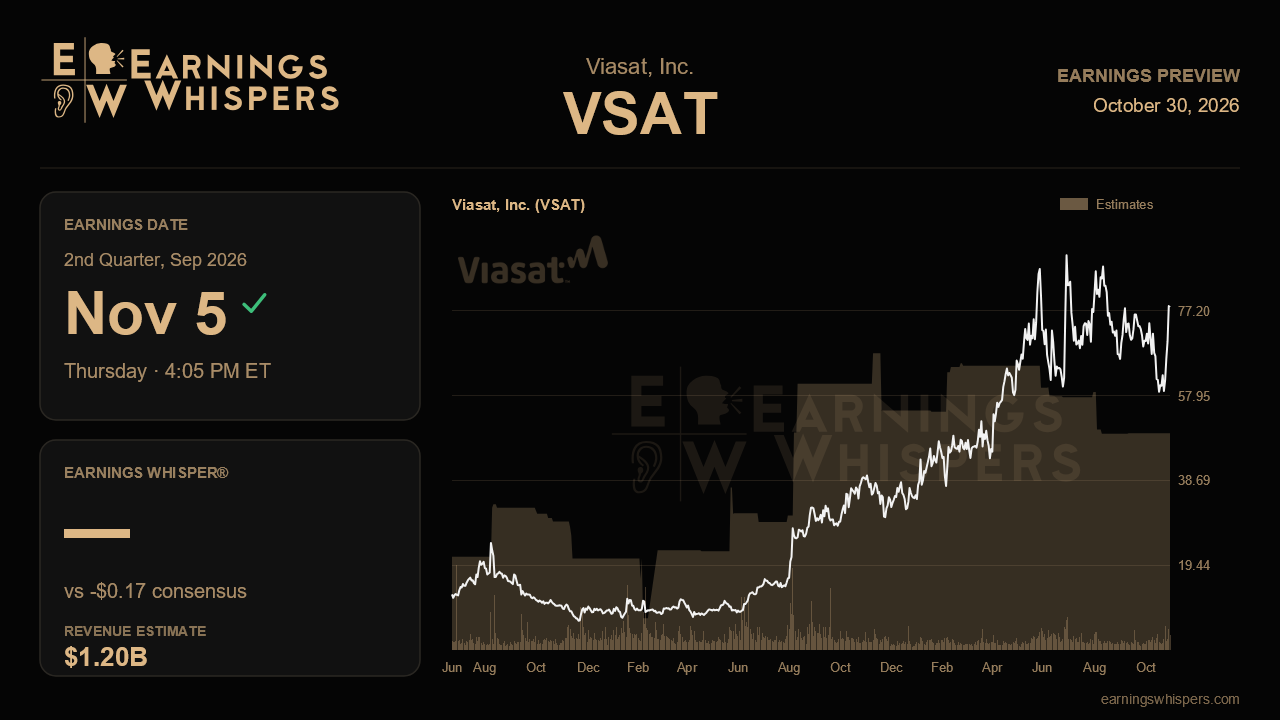
Viasat heads into its fiscal second-quarter report with a split personality that the market has not yet resolved. Its defense and government business is collecting awards at the fastest pace in recent memory, while its legacy commercial services are losing ground to tougher competition. Last quarter those forces roughly cancelled out. This time the Street is betting the defense momentum starts to show up in the top line, and that is a meaningfully higher bar.
Consensus calls for revenue of about $1.20 billion, up 5.2% from a year ago, alongside a loss of roughly $0.17 per share. That revenue target matters more than it looks. Viasat's sales slipped about 1% in the June quarter and were flat excluding one-time items, so analysts are effectively asking for a swing of roughly six percentage points in growth within a single quarter. The good news is that the estimate sits squarely in line with management's reaffirmed fiscal 2027 outlook for mid-single-digit revenue growth, flat to slightly higher adjusted EBITDA and roughly $180 million of free cash flow. The less comfortable point is that a full-year mid-single-digit target after a negative first quarter leaves little room for another soft period. The projected loss also contrasts with last quarter's small profit, so the bottom line is likely to be judged through EBITDA and cash flow rather than per-share earnings.
The defense story is where validation must come from. Defense and Advanced Technologies awards jumped 22% last quarter and segment backlog rose 32%, helped by the Protected Tactical Satcom Global win carrying a $4 billion ceiling. Yet segment revenue actually fell 4%, dragged down by a 24% decline in Space and Mission Systems tied to a supplier delay and a shift from development to production, plus lumpy encryption shipments. Management framed awards as a leading indicator of revenue later in the fiscal year. A return to growth in that segment, continued strength in tactical networking after last quarter's 36% surge on Trellisware international sales, and government satellite communications growth holding near the 10% pace would all suggest the conversion is underway. Another quarter of rising backlog and falling revenue would start to look like an execution problem rather than timing.
On the commercial side, the questions are about how fast the erosion is spreading. Aviation backlog has shrunk from about 1,100 aircraft two quarters ago to roughly 850, with management acknowledging deactivations to a rival and a moderating growth rate. Maritime revenue fell 7% despite an order book of more than 1,400 vessels for Nexus Wave, as installations lag in a fragmented distribution channel. Fixed broadband subscribers dropped to 115,000. Stabilization in aviation backlog and faster maritime installs would ease concerns; another sharp step down would reinforce the view that commercial weakness is structural. Updates on ViaSat-3 Flight 3 service in Asia-Pacific, the still-open strategic review of the defense unit and spectrum assets, and further cash movement out of Inmarsat, which reached $450 million last quarter, will also shape the narrative.
Sentiment has warmed considerably, with bullish readings climbing to about 70% from roughly 33% ahead of the prior report. The stock, however, has barely moved, gaining less than 1% since last quarter while edging out a slightly lower S&P 500. At about $78, shares sit comfortably above the 200-day moving average near $64 but well short of the post-earnings high of $88.40, in the upper middle of a wide range. That suggests optimism without a crowded breakout trade.
Ultimately, this report comes down to whether the defense backlog begins converting fast enough to deliver the growth step-up the Street now expects. If DAT revenue turns higher while commercial declines stop accelerating, the reaffirmed full-year outlook looks credible. If not, the gap between record awards and stagnant revenue becomes the story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 16 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 |
