Universal Electronics Must Show Its Revenue Slide Has Bottomed As Cost Cuts Carry Profits
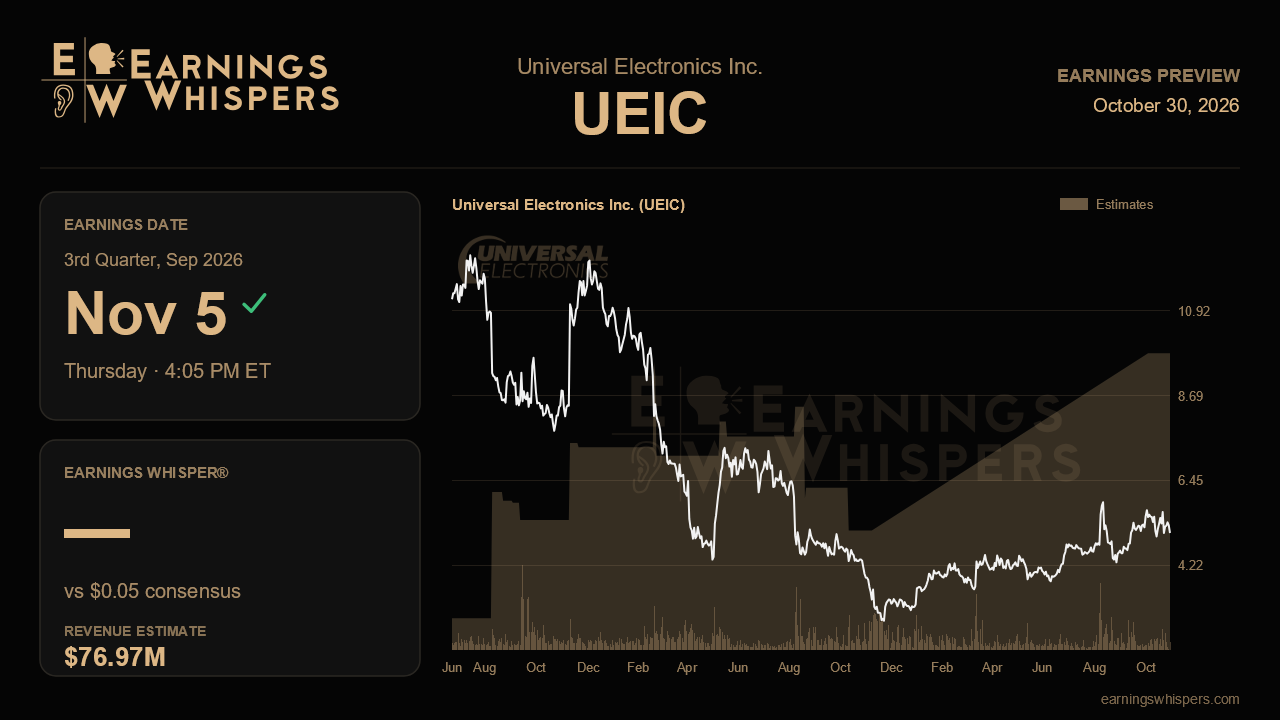
Universal Electronics has proven it can make money on a shrinking business. The third-quarter report has to show that the business is about to stop shrinking. After four straight quarters of falling sales, the restructuring story now needs a top line that cooperates, and the November 5 release after the close is the first real chance to check whether it does.
The Street is looking for adjusted earnings of about $0.05 a share on revenue of $77.0 million. Against a year-ago profit of $0.02, that works out to 150% earnings growth. The headline number flatters the picture, though, because it rests on a tiny base. Revenue is still expected to fall 15% from $90.6 million a year earlier. The more telling comparison is sequential. Consensus implies a modest lift from the second quarter's $73.2 million, which would be the first quarter-over-quarter gain in more than a year. If the company delivers that, the slide has at least paused. If revenue prints near or below the second-quarter level, the argument that cost cuts can outrun demand erosion gets harder to make.
The full-year math raises the stakes. Management has now reaffirmed its adjusted EPS framework of $0.45 to $0.65 on three consecutive calls, never raising and never trimming it. First-half earnings came to roughly $0.20 to $0.24, depending on how the second quarter is measured, and that total includes a one-time $5.1 million tariff recovery that management said will not repeat. Even the low end of the range therefore needs back-half earnings of more than $0.20. A $0.05 third quarter would leave the fourth quarter carrying most of that load. A clean beat would make the target look comfortable. A miss, or any softening in the language around the range, would suggest the reaffirmations were more hope than plan.
The swing factor is gross margin. Excluding tariffs, adjusted gross margin slipped to around 27% last quarter from nearly 30% in late 2025. Management attributed roughly 240 basis points of that drag to component and memory inflation and about 150 basis points to the Chinese currency. It also named component costs and stretched lead times as the central risk for the second half. Operating expenses, by contrast, have been the clear success story. They fell 24% year over year last quarter, and R&D has dropped steadily. There is a limit to how much more can be cut without hollowing out product development, so further margin compression would quickly eat into the gains from leaner spending.
The growth catalysts introduced last quarter are mostly fourth-quarter events, but this report should show whether they are on schedule. The company moved to sole-source status on a remote control program for a large video customer, with production slated for November. It also shipped its first mass-production smart thermostat platform to a major HVAC OEM, which asked for more volume in the fourth quarter. Connected home, meant to be the growth engine, fell to $25.1 million from $34.1 million a year earlier. Any sign that the thermostat ramp is beginning to stabilize that segment would matter more than the third-quarter EPS figure itself. The report will also be the first under Wade Janke as permanent CEO, so his tone on the outlook will carry some weight.
The market has not given the turnaround much credit. Shares have fallen 8.7% since the last report while the S&P 500 was essentially flat, and sentiment leans modestly bearish. Still, at $5.07 the stock sits above its 200-day moving average of $4.46 and in the middle of a $4.24 to $5.99 post-earnings range, which is meaningfully higher than the prior quarter's band. In short, expectations are tempered rather than washed out. What will decide whether the narrative holds is not whether Universal Electronics can stay profitable through cost discipline, which it has already shown. It is whether revenue and gross margin have stopped deteriorating enough to make a back-half-weighted earnings target believable.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-29 | |
| Sep-15 | |
| Sep-08 | |
| Aug-06 | |
| Aug-06 | |
| Jul-30 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-04 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 | |
| Mar-04 |
