Eastman Chemical Misses On Easy Comparison As Price-Cost Whipsaw And Another Cash-Flow Cut Overshadow Strategic Wins
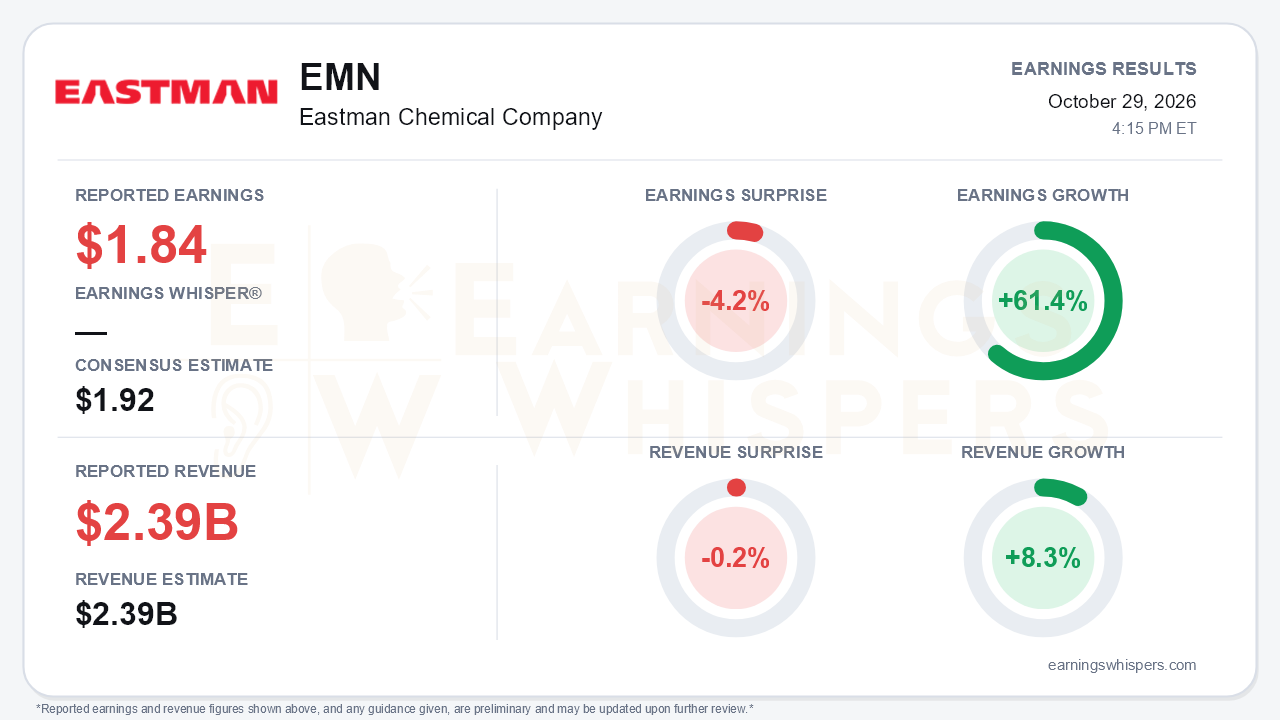
Eastman Chemical reported third-quarter adjusted earnings of $1.84 per share, missing the $1.92 consensus by 4.2%. Revenue of $2.385 billion came in essentially in line, 0.2% below the $2.39 billion estimate. On paper, growth looks strong: earnings rose 61.4% year over year and revenue grew 8.3%. That growth is less impressive than it appears. The year-ago quarter was depressed by deliberate inventory-reduction actions that hurt asset utilization, so this year's gains largely reflect a normalization. The central tension is that a quarter showing sharp earnings growth still fell short of expectations, and full-year guidance came in below estimates. Management also trimmed its cash outlook and now faces a fourth quarter in which several tailwinds have turned into headwinds.
The quality of the quarter deserves scrutiny. The 8% sales increase came almost entirely from 7% higher selling prices. Volume/mix contributed just 1%, and most of the pricing passed through higher raw material and distribution costs tied to the Middle East conflict rather than reflecting stronger demand. Adjusted EBIT rose to $305 million from $210 million, which the company attributed to better asset utilization, lower planned maintenance and favorable price-cost, partly offset by higher variable compensation. GAAP EPS of $2.19 exceeded the adjusted figure. Because GAAP and adjusted EBIT were both $305 million, the gap reflects items below the operating line, and the $1.84 adjusted figure is the better measure of core performance. Cash generation was the weak spot. Operating cash flow fell to $290 million from $402 million a year ago, and the company has built roughly $560 million of working capital year to date.
Segment results were uneven. Additives & Functional Products was the standout, with 10% higher prices driving improved price-cost, and management said the segment is on track for record earnings. Chemical Intermediates posted 16% revenue growth on wider spreads as the conflict tightened markets. Fibers revenue was flat, and EBIT declined on lower acetate tow contract pricing. Advanced Materials showed no volume growth. On the call, management said third-quarter Advanced Materials volumes came in below second-quarter levels, even though it had guided to similar or higher volumes. It attributed the shortfall to roughly one-month startup delays on new Tritan and PET polymer lines.
The forward picture deteriorated in specific ways. Management now expects Advanced Materials to face a roughly $15 million price-cost headwind in the fourth quarter, after it had anticipated a tailwind of more than $15 million on the second-quarter call. The full-year headwind for the segment is now about $30 million. In Chemical Intermediates, the propylene-propane spread has compressed to about 14 cents per pound from roughly 27 cents in the third quarter, and an open US-Asia arbitrage of about 20 cents adds pressure. Management suggested the segment's 2027 earnings may be moderately below 2026. Full-year 2026 operating cash flow guidance was cut to about $850 million, down from about $900 million in the second quarter and roughly $970 million in the first quarter. Circular platform revenue is now framed as up to about $100 million, versus more than $100 million previously, with about $20 million of incremental earnings against the $30 million targeted in January. Customers are placing smaller, more cautious orders, and a planned turnaround slipped into the fourth quarter. Adjusted EPS guidance of $6.00 to $6.20 landed below Street expectations.
Bulls still have real material to work with. The $375 million DOE award was reinstated at full value with a rescoped project, and management indicated DOE could fund 30% to 50% of the combined Kingsport expansion and second methanolysis plant. Management also plans to acquire idled US recycling and polymer assets to lower second-plant capital costs. The ethylene-to-propylene metathesis project was formally advanced, with roughly $100 million of targeted EBITDA, a one-to-two-year payback and a mid-2028 startup. Management framed 2027 constructively:
- volume growth in Advanced Materials, Additives & Functional Products and Fibers;
- at least $100 million of incremental circular revenue;
- significantly higher cash flow as working capital unwinds.
Offsetting these, capex is rising to about $500 million in 2027 from roughly $400 million, and acetate tow pricing faces another mid-single-digit decline.
The market had already turned cautious ahead of the report. Investor sentiment moved from essentially neutral to modestly negative, a meaningful shift but not a capitulation. Shares at $67.93 are down 2.8% since the open after the July report and sit 4.3% below the 200-day moving average of $71.00. The trend readings are mixed: price trend is negative, while AVWAP remains positive.
The bottom line is that Eastman's earnings growth flattered a quarter that was mostly about passing through inflation. Execution slipped in Advanced Materials, and the outlook weakened on price-cost, spreads and cash flow. The DOE reinstatement and the metathesis project preserve a credible 2027 growth story. However, management has now cut its cash-flow guidance for the third time this year, so investors are likely to want evidence that the January price increases and the working-capital release actually materialize.
Read our earnings preview for Eastman Chemical Company: https://www.earningswhispers.com/article/EMN/21187
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-16 | |
| Oct-06 | |
| Sep-15 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-08 | |
| May-27 | |
| May-19 | |
| May-19 | |
| May-07 |
