Quaker Houghton Posts A Pricing-Driven Beat And Record EBITDA, But Slower Volumes, A Delayed Margin Recovery And Weak Cash Flow Temper The Quarter
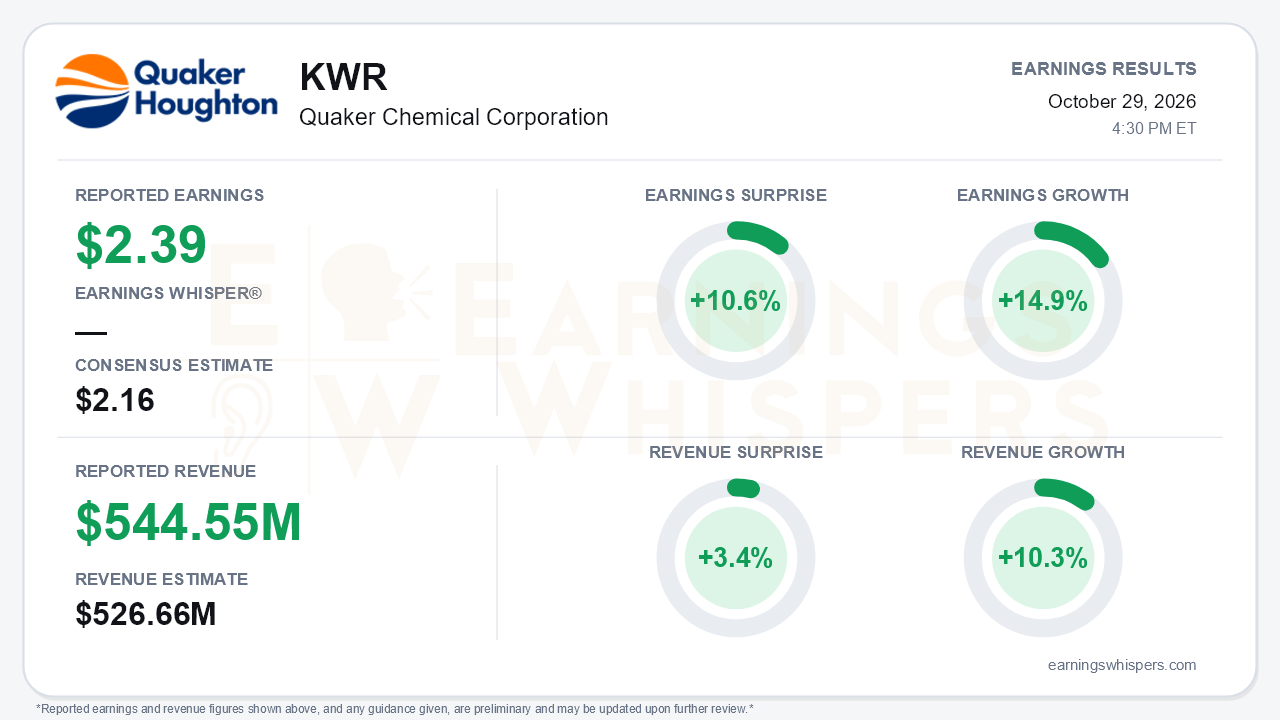
Quaker Houghton (NYSE: KWR) delivered a clean headline beat in the third quarter. Non-GAAP earnings of $2.39 per share topped the $2.16 consensus by 10.6%, and revenue of $544.55 million beat expectations by 3.4%. Earnings grew 14.9% year over year and revenue rose 10.3%, while adjusted EBITDA reached a record $89.8 million, the second record quarter in a row. The more important story is what drove the beat. Pricing finally caught up with raw materials, with price and mix contributing 7%, up from just 1% in the second quarter. At the same time, volume growth slowed, the gross-margin recovery was pushed out, and cash generation weakened. That is the central tension: profits are hitting records while several underlying indicators are moving in the wrong direction.
The quality of the beat deserves scrutiny. Earnings growth decelerated to roughly 15% from 28% in the prior quarter, even as the top line accelerated. On a GAAP basis, diluted EPS was $1.73, slightly below $1.75 a year ago. The roughly $0.66 gap to the non-GAAP figure reflects restructuring charges, $0.14 of business-transformation costs, duplicate headquarters lease costs and discrete tax items. Gross margin was 35.5%, down 130 basis points from 36.8% a year earlier, as higher input costs absorbed much of the pricing benefit. Adjusted EBITDA margin of 16.5% improved sequentially from 16.0% in Q2 and 15.1% in Q1, but it still trailed last year's 16.8%. Sequential improvement is real, but year-over-year margins have not yet been restored.
Beneath the consolidated figures, results diverged sharply by region. The Americas was the standout. Sales rose 14% on 6% volume growth as idled steel capacity restarted, and segment earnings climbed 11%, a reversal from a 3% decline in Q2. EMEA volumes fell 2% as second-quarter pre-buying unwound. Even so, segment earnings rose 18% to their best level in more than five years following the Dortmund closure, and management expressed hope that the region's margin floor has been reset higher. Asia/Pacific grew volumes 5%, but segment earnings slipped slightly because pricing lags in the company's most price-sensitive region and China is softening. Management characterized underlying end markets as flat to slightly lower. That means the volume growth is coming from share gains: the call cited a 12th consecutive quarter of net share gains and churn in the low single digits.
The forward picture contains genuine catalysts alongside clear setbacks. On the positive side, management offered an early qualitative commitment to grow EBITDA, volume and revenue in 2027. It also reported transformation run-rate savings now exceeding $10 million, with SG&A below 24% of sales. After the quarter closed, the company completed its first term loan B, which extended maturities and reduced required debt payments, and an Investor Day is set for December 10. On the negative side, the timeline for returning gross margin above 36% slipped from "by year-end" to "a quarter or two." Raw materials, which management expected in Q2 to moderate in the second half, are now seen rising further in Q4, with no meaningful relief until 2027, partly because of supply tightness tied to the Middle East conflict. Fourth-quarter revenue and EBITDA are guided up year over year but down sequentially, with a typical seasonal decline of about 4% that could be steeper in Asia.
Bears also have legitimate ammunition on cash flow. Third-quarter operating cash flow was roughly $14 million, compared with $51 million a year ago. Year-to-date operating cash flow of $47.6 million is barely half the prior-year pace, as receivables rose about $73 million and inventories about $57 million. Net debt stands at $727.6 million, or 2.3x trailing adjusted EBITDA. Share repurchases slowed to $3.3 million from $24 million in Q2, and 2026 capex guidance was trimmed to 2-2.5% of sales. Some of the working-capital build reflects higher prices flowing through receivables and inventory, but the cash conversion trend still contrasts with the record EBITDA headline.
Investor sentiment improved modestly ahead of the report, moving from slightly negative (-0.056) to essentially neutral. That shift signals fading skepticism rather than enthusiasm. The stock has gone essentially nowhere since the last report. At $157.87, shares were down 0.4% from the open following the July release, though they sit about 5% above the 200-day moving average of $150.30. Price trend readings are neutral and the AVWAP trend remains negative, consistent with a market that has not yet rewarded the earnings recovery.
The bottom line is that Quaker Houghton's beat was earned largely through pricing catch-up and share gains in flat end markets. The Americas restart and EMEA restructuring give the profit story real support. However, decelerating volumes, a postponed gross-margin recovery, persistent raw-material inflation and weak cash conversion mean the quarter was better on the income statement than beneath it. The Investor Day and the 2027 outlook will need to show that margins and cash flow can follow earnings higher.
Read our earnings preview for Quaker Chemical Corporation: https://www.earningswhispers.com/article/KWR/21211
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-15 | |
| Oct-01 | |
| Aug-27 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-16 | |
| Jun-25 | |
| Jun-02 | |
| May-13 |
