ACCO Brands Beats And Raises, But Tariff Refunds And The Trust Deal Mask A Sharper Organic Slide
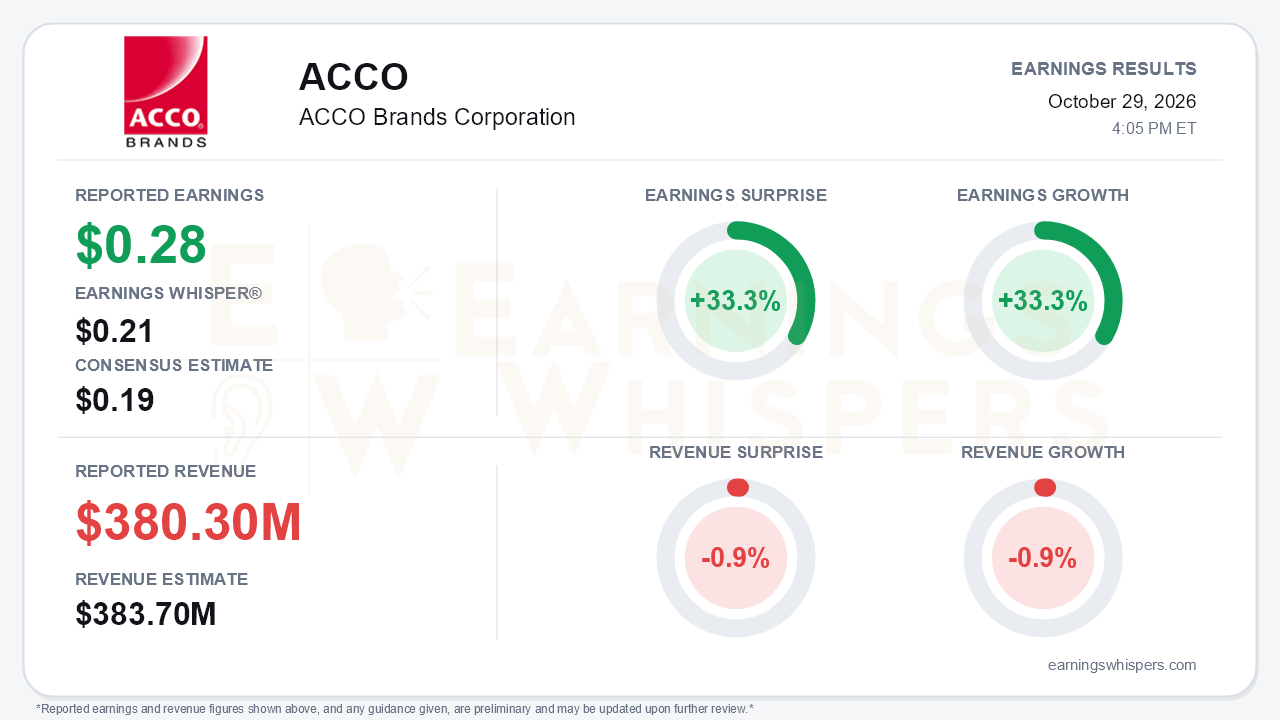
ACCO Brands posted third-quarter adjusted earnings of $0.28 per share. That cleared the $0.19 consensus by 33.3% and topped the $0.21 Earnings Whisper number, while earnings grew 33.3% from a year earlier. Revenue of $380.3 million missed consensus by 0.9% and fell 0.9% year over year. Management raised full-year guidance for the second straight quarter. The quality of the beat deserves scrutiny, though. Net tariff refunds contributed $0.11 per share, and without them adjusted EPS would have been roughly $0.17. Management itself said that underlying figure landed at the low end of its 17- to 21-cent outlook. That is the central tension: the headline beat and the guidance raise come largely from a one-time cash windfall and an acquisition, while the organic business deteriorated faster than in the first half.
The top line shows the slowdown clearly. Reported sales growth moved from 8.3% in the first quarter to 5.1% in the second and turned negative in the third. Comparable sales fell 6.2%, worse than the 2.3% and 2.5% declines of the prior two quarters. EPOS contributed 4.9 points of growth but could not offset that decline. Both segments posted comparable declines of about 6%, and technology peripherals were the common weak spot. Refunds also flatter the margins. They added roughly 520 basis points to gross margin and 400 basis points to the 12.6% adjusted operating margin. Excluding them, adjusted operating margin would have been about 8.6%, below the 10.2% of a year ago. GAAP EPS rose to $0.12 from $0.04, helped by refunds and a far lower tax rate, despite a $4.8 million reserve tied to a customer liquidation.
The call made the operating picture plainer. Tech peripherals fell by a low-double-digit rate as global laptop sales dropped about 20% and Switch 2 underperformed. Management also cited enterprise budgets shifting toward AI, plus higher hardware, memory and console prices weighing on accessory demand. That is a notable reversal from the first quarter, when management described computer accessories as strong with a meaningful pipeline. Underlying gross margin was roughly 30.7% excluding refunds, down from 33.1% in the second quarter. Management attributed the decline to unfavorable mix, promotions, fixed-cost deleverage and pricing lag. The traditional businesses offered the offset:
- North American back-to-school finished up mid-single digits with share gains, ahead of the flat to low-single-digit view given in the first quarter.
- Mexico rose about 20%.
- Workspace Solutions declines moderated to a low-single-digit rate.
The guidance raise needs context as well. Full-year adjusted EPS guidance moved to $0.98-$1.02 from $0.87-$0.91, but the new range explicitly includes $0.12 from tariff refunds. Stripping that out leaves the range essentially where it was. The sales outlook rose to 4%-6% growth, but it now includes a quarter of Trust revenue. Free cash flow guidance increased to about $100 million from $75-$85 million. Year-to-date free cash flow reached $89.0 million, including $21.3 million of refunds, and leverage fell to 3.6x from 4.3x at the end of the second quarter. However, the full-year target implies a muted fourth quarter of about $11 million, reflecting integration, restructuring and working-capital uncertainty. About $5 million of additional refunds received after quarter-end are not in the outlook, which offers modest cushion.
The strategic catalyst is the Trust acquisition, which closed October 1. It adds roughly $100 million of European and Latin American computer and gaming peripherals. Management expects the deal to be modestly accretive in its first year and to deliver $5-$8 million of synergies within 18 months. Combined with Kensington, PowerA and EPOS, it builds a tech peripherals platform of nearly $500 million, about 30% of pro forma sales. Management sees long-term mid-single-digit growth in that platform and flagged gaming tailwinds from GTA VI and new console cycles. Bears have legitimate ammunition, however. ACCO is doubling down on the very category that is currently shrinking, and it must integrate two acquisitions in a single year.
Investor sentiment improved meaningfully into the report, rising from -0.21 after the prior quarter to roughly neutral at +0.01. Shares at $4.36 are only 3.1% above the opening price following the July report, yet they sit 10.4% above the 200-day moving average of $3.95. Price and AVWAP trend readings are positive. The market had already warmed to the deleveraging and cash-flow story before this report, which raises the bar for the organic trends to stabilize.
The bottom line is that ACCO delivered a cosmetically strong beat-and-raise built on tariff refunds, debt reduction and acquired growth, while the core business weakened. Comparable sales and underlying margins both deteriorated, and stripping out refunds, earnings guidance is effectively unchanged. The balance sheet is in better shape, and Trust broadens the growth platform. Still, until tech peripheral demand stops contracting, the improving sentiment rests more on cash and capital allocation than on operating momentum.
Read our earnings preview for ACCO Brands Corporation: https://www.earningswhispers.com/article/ACCO/21159
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-21 | |
| Oct-16 | |
| Oct-02 | |
| Sep-15 | |
| Aug-14 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-24 | |
| Jul-22 | |
| Jun-09 |
