Standex Accelerates And Raises FY27 Outlook As Electronics Surges, But Shares Enter The Report Deeply Out Of Favor
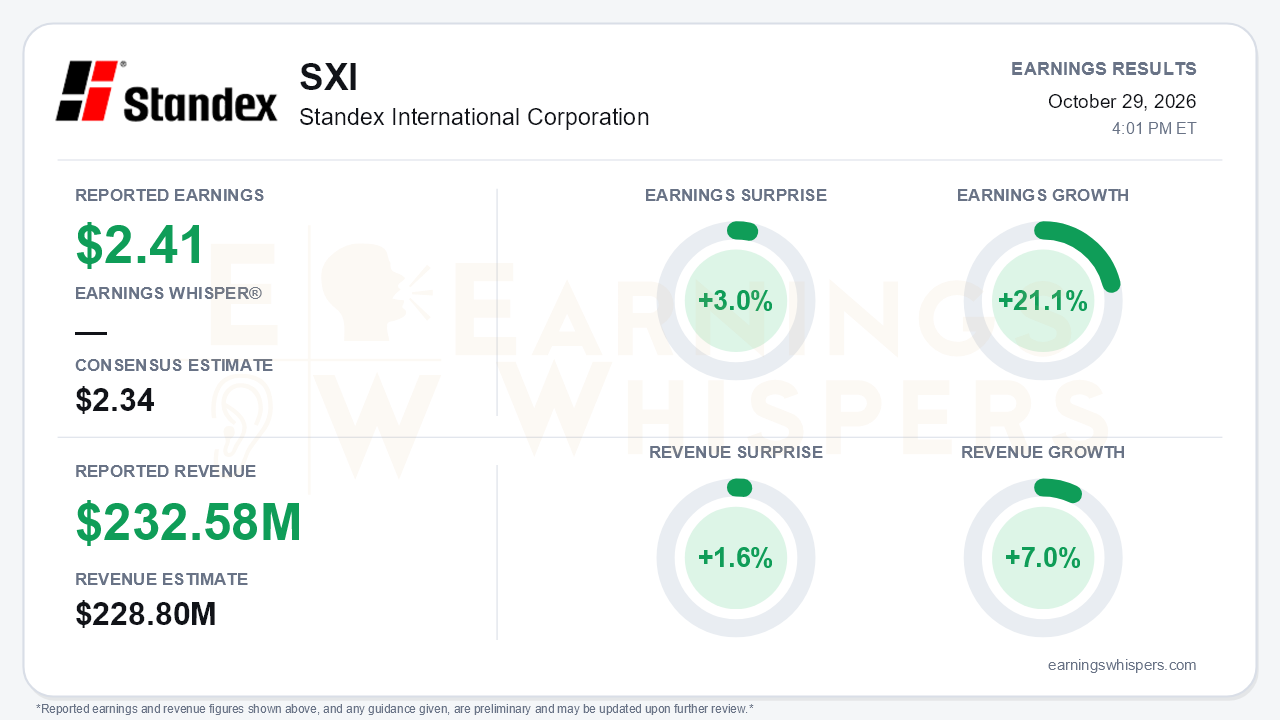
Standex International delivered the kind of quarter that a stock trading 18.9% below its post-July open was not priced for. Adjusted earnings of $2.41 per share beat the $2.34 consensus by 3.0% and grew 21.1% year over year, a sharp acceleration from 7.4% growth in the fourth quarter and 13.5% in the third. Revenue of $232.58 million topped the $228.8 million estimate by 1.6% and rose 7.0%. More important than the modest beat, management raised full-year guidance for the first time this cycle. FY27 total sales growth now stands at high single digits, up from mid-to-high single digits. Organic sales are expected to rise by more than $100 million, and adjusted EPS growth is now quantified at high teens. That is the central tension: the fundamental story is accelerating while investor sentiment and the chart moved firmly the other way.
The headline 7.0% revenue growth understates the momentum. Organic growth was 12.4%, up from 7.7%, 6.5% and 6.4% over the prior three quarters. Reported growth was diluted by the absence of the divested "Other" business, which contributed $9.5 million a year ago. Electronics did the heavy lifting with 29.5% organic growth, more than double the prior quarter's 12.9%. The segment posted record revenue of $140.5 million, record orders of about $173 million, and a 1.23 book-to-bill. Total orders reached a record of roughly $273 million, a 1.17 book-to-bill. Adjusted gross margin hit a record 44.4%, up 240 basis points. Adjusted operating margin expanded 110 basis points to 20.2%, with gains in every segment. Electronics margin recovered to 29.4% from the ERP-affected 27.2% in the fourth quarter. GAAP diluted EPS from continuing operations jumped to $1.99 from $1.25 as restructuring charges fell sharply.
The quality of the quarter is high but not spotless. Adjusted EPS slipped sequentially from $2.45, and adjusted EBITDA margin eased 60 basis points from the fourth quarter. Corporate expense rose about $3 million on variable compensation, medical costs and recruiting. Free cash flow was just $9.1 million, down from $10.4 million, as inventory built by nearly $14 million. Net leverage rose to 2.0x from 1.8x after the $64 million buyout of the Narayan noncontrolling interest. Engraving & Hydraulics remains a genuine drag. Its organic decline deepened to 15.7% on North American auto weakness, from 9.6% in the fourth quarter and 1.8% in the third, and management expects a further sequential dip.
The call added substance to the raise. The grid sales outlook was narrowed upward to $190-200 million. Croatia shipments begin this quarter, and the larger Houston facility is expected in mid-2027. Capex of $45-55 million, roughly double FY26's $25.2 million, signals real confidence in grid capacity. Missile sales are now expected at about $20 million this year, versus roughly $15 million previously, and the multi-year range rose to $50-90 million. New product sales were lifted to $94 million and fast-growth market sales to more than $315 million. Management is also pursuing three- to five-year supply agreements with key grid OEMs, has identified aftermarket instrument transformers as a new opportunity, and announced a fresh $100 million buyback.
Bears have legitimate ammunition, though. Data centers account for roughly 30% of FY27 growth and about three-quarters of grid growth. That ties the stock to a sentiment-driven theme vulnerable to project delays and local opposition. The Croatia ramp depends on customer audit timing. The leadership changes add execution questions: the CFO is moving to run Electronics, and a new CFO and Chief Legal Officer are arriving.
The market setup reflects those worries more than the operating data. Earnings Whispers investor sentiment deteriorated meaningfully, from -0.22 to -0.56. Shares at $248.19 sit 10.5% below the 200-day moving average of $277.39, and price and AVWAP trends remain negative. Because that snapshot was taken on report day, it captures how deeply out of favor the stock was going in, not the reaction to the raise.
The bottom line is that Standex delivered accelerating organic growth, record orders, broad margin expansion and a credible guidance increase. The near-term outlook calls for only slightly higher sequential revenue at similar margins, so the debate now shifts to whether a backlog increasingly levered to grid and data-center demand can convert into cash. Engraving & Hydraulics also needs to stop deteriorating. With sentiment sharply negative and the stock well below trend, expectations entering the quarter were low.
Read our earnings preview for Standex International Corporation: https://www.earningswhispers.com/article/SXI/21328
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Oct-19 | |
| Oct-14 | |
| Sep-10 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-24 | |
| Jul-23 |
