Jinko Holdings Nears Breakeven On A Tripled Gross Margin, But Shrinking Volumes And A Q4 Margin Warning Temper The Inflection
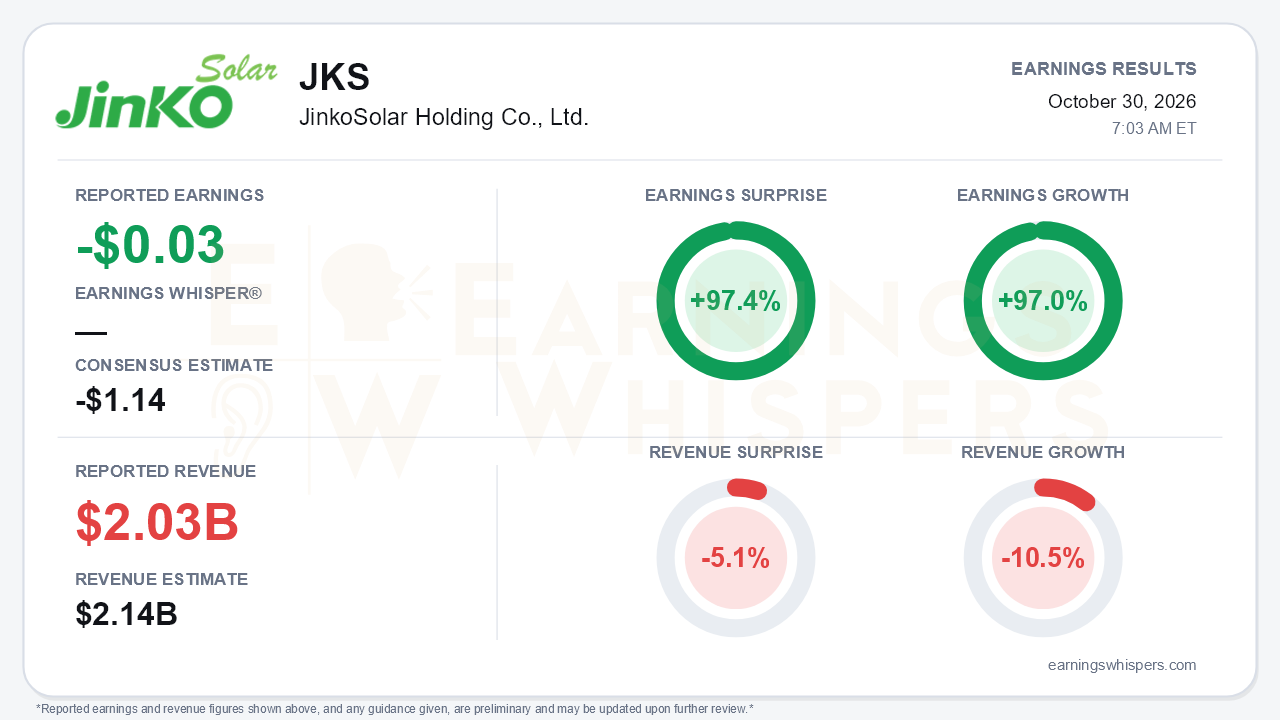
Jinko Holdings (NYSE: JKS), the former JinkoSolar, delivered the profitability inflection that a deeply skeptical market was not positioned for. The company reported an adjusted loss of $0.03 per share against a consensus estimate of -$1.14, a 97.4% earnings surprise. Earnings improved 97.0% year over year. Revenue of $2.031 billion missed the $2.14 billion consensus by 5.1% and fell 10.5% year over year on Earnings Whispers' dollar basis. The company's own RMB figures show a steeper 15.7% decline. That is the central tension: margins and losses improved dramatically, but the volume engine underneath them is still shrinking. Management is already warning that part of the margin gain will not carry into the fourth quarter.
The gross-margin swing was the core of the quarter. Gross margin reached 12.3%, up from 4.2% in Q2, 8.3% in Q1 and just 0.3% in Q4 2025. Management attributed the improvement to TOPCon 3.0 cost optimization, a richer mix of high-efficiency Tiger Neo 3.0 modules and a larger contribution from higher-margin energy storage. The operating loss narrowed to RMB80 million, a 0.6% operating loss margin, from RMB1.44 billion in Q2. Operating expenses fell 10.2% sequentially, helped by lower credit losses and the absence of impairments. The quality of the beat still deserves scrutiny below the operating line:
- RMB385.6 million of subsidy income was essentially what lifted adjusted net loss to near breakeven, at just RMB7.9 million ($1.2 million).
- A RMB228.7 million currency loss hit results.
- A RMB167.5 million fair-value loss on the investment portfolio was excluded from adjusted results.
- On a GAAP basis, the loss attributable to shareholders was $0.48 per ADS. That is far better than RMB14.32 per ADS a year ago, but still a meaningful loss.
The call added two layers to the story: a credible storage story and a soft module story. Energy storage recognized about 1.75 GWh in Q3, matching all of 2025, up from more than 1 GWh in Q2 and 0.52 GWh in Q1. The business posted its first positive quarterly operating profit, with gross margin of roughly 15-20%. Management reaffirmed about 10 GWh of 2026 shipments and guided revenue recognition to 6-7 GWh, implying about 3 GWh in Q4, with roughly 7 GWh of backlog carrying into 2027. Modules tell a different story:
- Q3 shipments of 15.0 GW came in at the low end of the 15-17 GW guide, down 25% year over year.
- Full-year shipments are tracking to roughly 61-63 GW, the bottom of a 60-70 GW range that was already cut from 75-85 GW.
- The Q4 guide of 16-18 GW is a modest step up, and Tiger Neo 3.0 should rise from about 30% to 40% of the mix.
Bears have legitimate ammunition, starting with management's own warnings. Management explicitly flagged Q4 gross-margin pressure from a heavier China shipment mix and low-priced long-term contracts signed early in the year. It also cited elevated freight and energy costs tied to the Middle East conflict, which it expects to persist for several quarters, and described current module pricing as unsustainable, with a recovery needed in 2027. The balance sheet also moved the wrong way:
- Cash fell to RMB15.56 billion from RMB16.94 billion.
- Net debt rose to $4.41 billion from $4.12 billion.
- Inventories climbed to RMB17.61 billion, with inventory days up to 133 from 125.
The partial offsets are receivables days, which improved to 103 from 113, and China's Level 1 efficiency standard, effective January 2027. Management expects that standard to phase out weaker capacity, and the company plans about 40 GW of compliant capacity by year-end.
The strategic repositioning adds a second source of uncertainty. Management said the renamed holding company will not put additional capital into solar manufacturing and will instead invest in AI, semiconductors, advanced materials and commercial space. The portfolio has real wins:
- Fair value is about RMB2.05 billion.
- Nine-month gains total about RMB327 million.
- The LAPLACE exit returned roughly RMB357 million in cumulative gains on RMB65 million invested.
Even so, redirecting capital toward frontier-tech stakes while net debt rises invites questions about priorities.
The market had braced for the worst going into the report. Shares fell 44.4% from the $14.79 open after the August report to $8.23, sitting 57.1% below the 200-day moving average. The stock entered earnings just 5.2% above the 52-week low of $7.83 set on October 22. Investor sentiment deteriorated meaningfully over the period, falling from roughly neutral at -0.05 to -0.27. Earnings Whispers price, momentum and AVWAP trend readings are all negative. A near-breakeven quarter lands against expectations that had been reset sharply lower.
The bottom line is that Jinko's third quarter showed genuine operating progress. The tripled gross margin, profitable storage and sharply narrower losses go well beyond what bearish positioning anticipated. However, the improvement leaned on mix, subsidies and storage while module volumes and revenue kept contracting, and management is already guiding to margin pressure in Q4. The report makes the turnaround argument more credible, but sustaining it depends on storage scale, module pricing in 2027 and disciplined use of capital as the company recasts itself as a holding company.
Read our earnings preview for JinkoSolar Holding Co., Ltd.: https://www.earningswhispers.com/article/JKS/21331
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-23 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-17 | |
| Oct-16 | |
| Sep-09 | |
| Sep-09 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 |
