Federal Realty Matches The Whisper And Raises FFO Guidance Again, But Rising Capital Costs Now Shape The Story
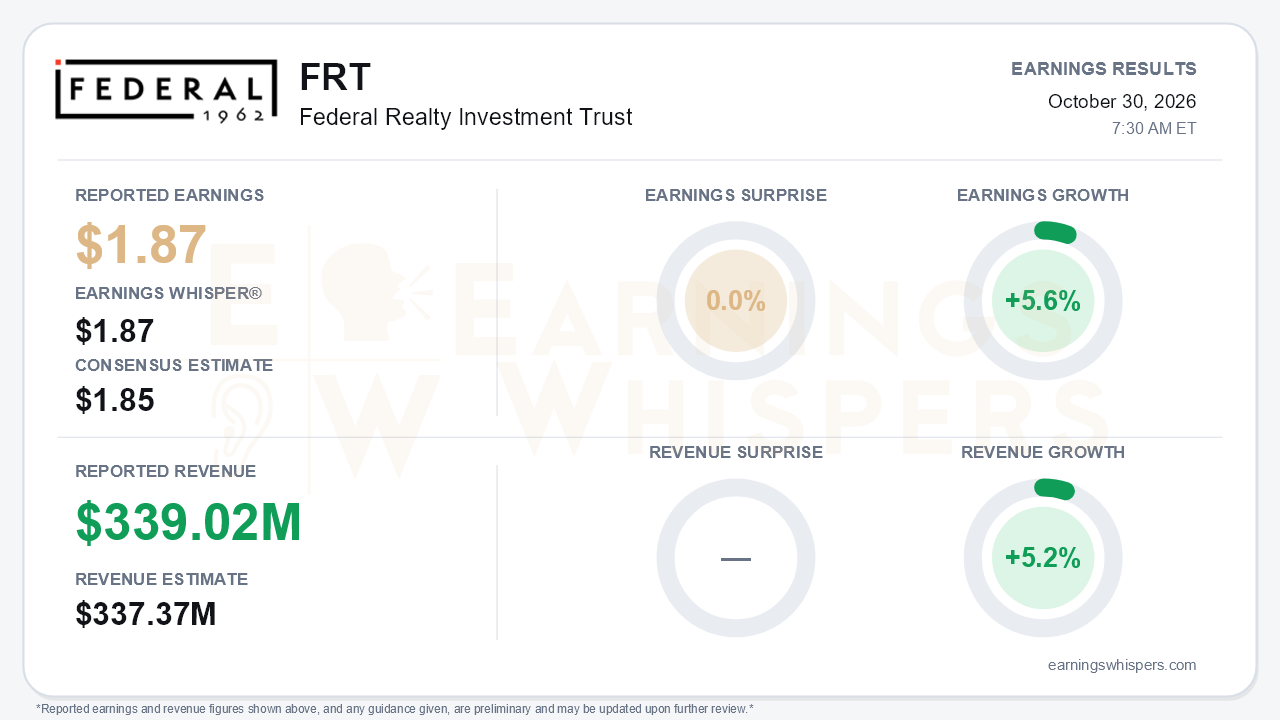
Federal Realty Investment Trust delivered exactly what the market was looking for, and not much more. Core FFO of $1.87 per share matched the Earnings Whisper number and edged past the $1.85 consensus, a result Earnings Whispers scores as in line. Revenue of $339.02 million beat consensus by 0.5%. FFO grew 5.6% year over year and revenue rose 5.2%. Management raised full-year Core FFO guidance for the third straight quarter, to $7.54 to $7.58, though the new range remains in line with estimates. The operating engine is running well. The central tension is that the cost of funding growth rose sharply during the quarter, and the stock has been pricing that in.
The quality of the quarter is solid, but growth is decelerating. FFO growth of 5.6% compares with about 7% in the second quarter and 10.6% in the first. Several underlying metrics also cooled modestly:
- Cash-basis comparable POI growth slipped to 4.0% from 4.2% in Q2 and 5.1% in Q1.
- Comparable leasing spreads eased to 14% on a cash basis from 15%.
- GAAP comparable POI growth was only 2.5%, partly because straight-line rent fell to $3.3 million from $5.8 million a year ago.
That gap favors the cash numbers, which is the better-quality direction. GAAP EPS rose to $0.74 from $0.69. The full-year midpoint implies roughly 7.1% Core FFO growth. That figure is flattered by stronger early-year comparisons, so Q3's slower pace is the more current read.
On the call, occupancy fundamentals were the clear strength. The leased rate reached 96.5%, the highest since 2007. Small-shop leased rose to 94.1%, and anchor leasing alone added 60 basis points sequentially. Physical occupancy was flat at 93.8%. The resulting 270-basis-point signed-but-not-occupied gap represents roughly $42 million of rent: about 30% is expected to commence in the fourth quarter and about half in 2027. That embedded rent gives the guidance raise credibility. Management lifted cash-adjusted comparable POI guidance by 25 basis points, to roughly 4.3% to 4.5%, but held the GAAP comparable POI midpoint at 3.5% after raising it in prior quarters. Bears also have a legitimate point on the leasing pipeline, which shrank to 1.3 million square feet from 1.5 million in Q2 and 1.7 million in Q1.
The Summit acquisition is the quarter's defining capital decision. Federal Realty paid $508 million for the 870,000-square-foot Birmingham center, closing October 1. Management cited:
- a low-6% cash yield and roughly 6.9% GAAP yield;
- a projected POI growth rate above 5% annually over five years;
- about 30% of leases rolling over five years at mid-to-high-teens mark-to-market;
- unpriced upside from the vacant Saks box and densification of the 100-acre site.
The funding backdrop has worsened, however. Disposition cap rates widened 25 to 50 basis points from May expectations, to the mid-to-upper 5% range. More than $600 million of asset sales has slipped to 2027. As a result, the Summit's roughly 3 cents of fourth-quarter accretion is temporarily inflated by higher leverage. Management widened its long-term refinancing headwind assumption by at least 50 basis points versus the Investor Day framework. Other balance-sheet pressures include:
- about $680 million of debt maturing in mid-2027 that will be refinanced at higher rates;
- liquidity down to about $1 billion from $1.2 billion;
- net debt to EBITDA up to 5.5x from 5.4x.
The $460 million of 3.5% exchangeable notes helped, with capped calls protecting against dilution up to about $165 per share. Management's tone stayed confident on operations but added rate caveats absent from earlier calls.
The market has been focused on that rate risk rather than the leasing data. Shares are down 11.7% from the $126.18 opening after the July report, which marked the inter-earnings high. They bottomed at $104.36 on October 14. At $111.44 entering the report, the stock had recovered 6.8% off that low but sat about 1.3% below its 200-day moving average. Management bought back roughly $95 million of stock at under $109, a move it tied to share-price weakness. Investor sentiment swung meaningfully, from modestly positive (0.12) after the prior report to negative (-0.23). The Earnings Whispers trend readings are split: price and AVWAP trends are negative, while sequential growth and momentum remain positive.
The bottom line is that Federal Realty's operations remain among the strongest in retail real estate, with record leased occupancy, embedded rent commencements and a third guidance raise. Still, this was an in-line quarter with decelerating FFO growth, a thinning leasing pipeline and a materially tougher capital environment. The Summit could prove an excellent long-term asset. Near term, though, the investment debate has shifted from whether Federal Realty can lease space to how much higher funding costs will erode the growth that leasing creates.
Read our earnings preview for Federal Realty Investment Trust: https://www.earningswhispers.com/article/FRT/21283
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 15 hours | |
| 16 hours | |
| 16 hours | |
| Oct-22 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-21 | |
| Sep-10 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-31 | |
| Jul-31 |
