BayFirst Nears Breakeven As Loan And Deposit Growth Return, But The Bank Still Can't Cover Its Costs And Dilution Is Not Finished
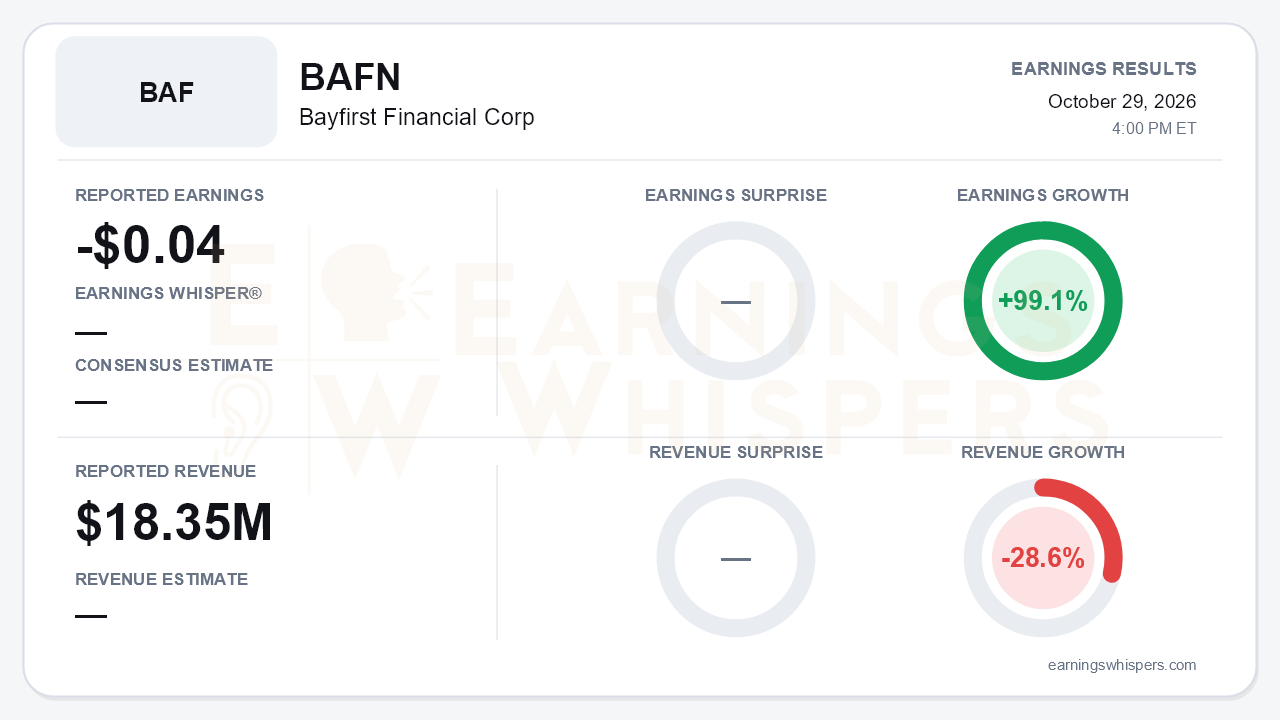
BayFirst Financial reported a third-quarter loss of $0.04 per share. That compares with a loss of $8.05 in the second quarter, when the asset resolution plan was booked, and $4.71 a year earlier. Earnings Whispers calculates a 99.1% year-over-year improvement in EPS. Revenue fell 28.6% to $18.35 million, which reflects the wind-down of the SBA 7(a) business. No consensus estimate was available, so there is no beat or miss to measure. The central takeaway is that this was the first clean quarter after the recapitalization. The CFO said it contained no non-recurring items, and balance-sheet growth turned positive for the first time in a year. The near-breakeven result is real progress. It is not yet proof of a profitable franchise.
The quality of the improvement deserves scrutiny on two fronts.
First, the per-share comparison is flattered by share count. Common shares rose from about 4.1 million to nearly 27 million after the Series D and E preferred converted. The $954,000 loss to common is therefore spread across roughly six-and-a-half times as many shares. In dollar terms, the net loss of $677,000 compares with $19.1 million a year ago. That is a dramatic narrowing, but less dramatic than the per-share figure implies.
Second, the core bank is still not covering its costs before credit:
- Net interest income was $10.6 million and noninterest income was $1.1 million, for about $11.7 million of revenue.
- Noninterest expense was $12.8 million.
- The result is a pre-provision loss of roughly $1.1 million.
- A $69,000 provision release helped the bottom line at the margin.
The operating trends are the encouraging part, and they changed direction convincingly.
- **Loans.** Loans held for investment rose $20.1 million after declines of roughly $35 million to $41 million in each of the prior three quarters. Community bank loans grew $41.9 million, a 25% annualized rate.
- **Deposits.** Deposits rose $25.3 million after outflows of about $97 million to $98 million in each of the first two quarters. Management highlighted that deposit growth outpaced loan growth for the first time in nearly three years. The mix was healthy: savings and money market balances rose $22.6 million while time deposits shrank.
- **Margin.** Net interest margin jumped 59 basis points to 4.07%, from 3.48%.
- **Loan timing.** Most loans were booked in September, so average loans actually declined $17 million from the prior quarter. That timing sets up a cleaner net interest income tailwind for the fourth quarter.
- **Expenses.** Noninterest expense fell from $17.7 million in the second quarter and $25.2 million a year ago.
- **Credit.** Net charge-offs fell to 1.52% annualized from 2.08%. Nonperforming assets dropped to 1.29% of total assets from 1.75%.
- **Tone.** Management described loan demand as "very strong" and is hiring commercial bankers to meet it. The new South Tampa branch beat its deposit expectations in its first month.
Bears still have legitimate ammunition.
- **Legacy SBA losses.** Unguaranteed SBA 7(a) balances of $132.4 million are running off about $10 million per quarter. They are still generating roughly $2.9 million of quarterly charge-offs, and management only hopes that pace moderates. The more than $30 million reserve against that book gives meaningful cushion. The falling allowance ratio, 4.85% from 5.37%, shows the second-quarter reserve build being consumed rather than released.
- **Deposit quality.** Deposits remain down 13.4% year over year. Brokered funding is still $165.7 million, and the insured share of deposits slipped to 79%.
- **Capital ratios.** Total risk-based capital eased to 12.44% after the Series A and B redemptions. Tier 1 leverage improved to 8.79%.
- **Governance.** The prior restatement and internal-control remediation remain in the background.
Dilution is the issue shareholders feel most directly. Tangible book value fell to $3.64 per share from $4.82. The rights offering added about 4.1 million more shares at $3.50, raising $14.4 million in gross proceeds. The release dates the share issuance to October 8, while the call described the offering as completed at the end of September. The pending Series C redemption, with most holders expected to convert at tangible book value, adds another layer. Management offered no numeric guidance and no explicit profitability timeline. It said only that the third-quarter loss is not indicative of what lies ahead, and a single analyst participated in Q&A.
The market context is thin but telling. Shares opened at $6.41 after the August report, near a 200-day moving average of $6.54. The rights offering was priced at $3.50, barely above the new tangible book value. That pricing is a reminder of how much per-share value the recapitalization reset, regardless of where the stock trades day to day. No current sentiment reading or trend snapshot was available.
The bottom line is that BayFirst delivered the inflection turnaround investors needed to see: loans and deposits are growing again, margin is above 4%, and credit costs are easing. The financial engine, however, is still running slightly below breakeven before provisions. The legacy SBA book continues to produce charge-offs, and the share count is not done expanding. The fourth quarter, with full-quarter benefit from September loan growth and no restructuring noise, will be the real test of whether near-breakeven becomes sustained profitability.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Sep-30 | |
| Sep-24 | |
| Sep-01 | |
| Aug-17 | |
| Aug-13 | |
| Jul-28 | |
| Jul-15 | |
| Jun-30 | |
| May-04 | |
| May-02 | |
| Apr-30 | |
| Mar-31 | |
| Feb-04 |
