Innovex Misses EPS Consensus, But 21% EBITDA Margins And A First 2027 Growth Framework Matter More
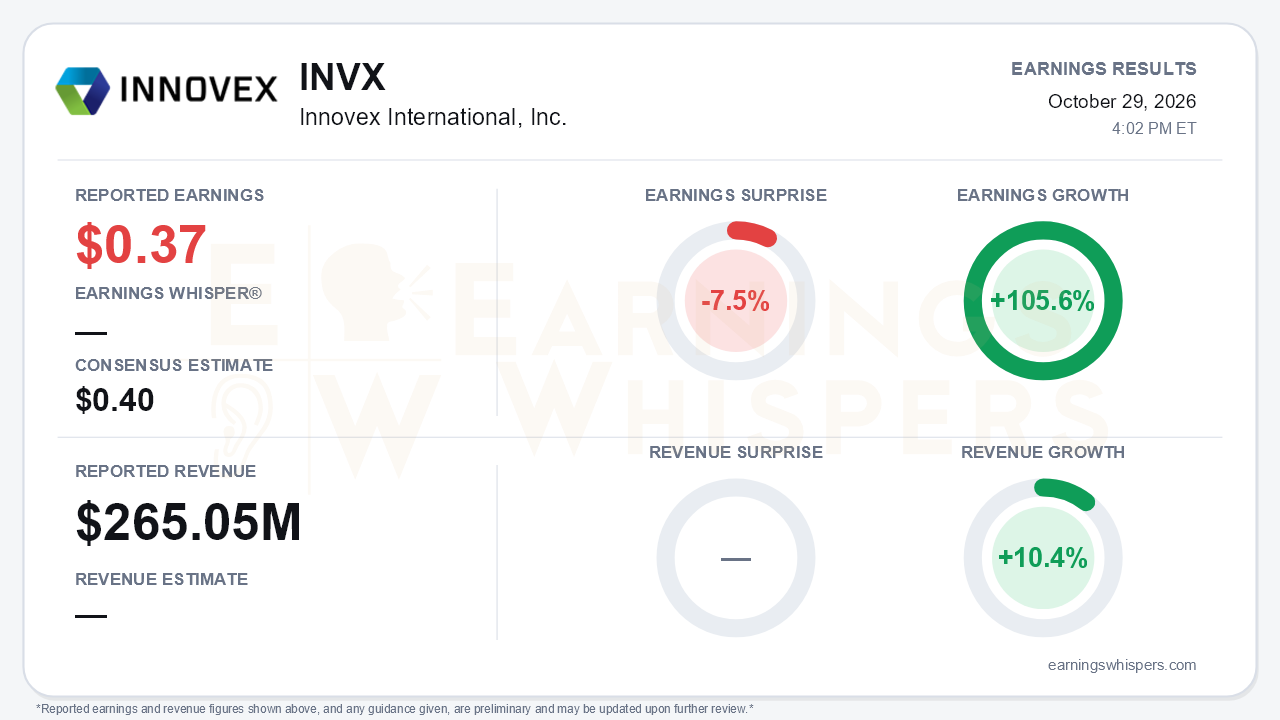
Innovex International (NYSE: INVX) reported third-quarter earnings of $0.37 per share, short of the $0.40 consensus by 7.5%. The miss does not capture the more important development: this was arguably the company's best operating quarter since the Dril-Quip merger. Revenue of $265.05 million rose 10.4% year over year and 8% sequentially, extending a progression from $239 million in Q1 and $245 million in Q2. Adjusted EBITDA reached $55.4 million at a 21% margin, up from 20% last quarter and 18% a year ago, and landed in the upper half of the company's own $51-57 million guide. On Earnings Whispers' normalized basis, earnings grew 105.6% year over year. That is the central tension. Operating momentum is clearly improving, while the per-share bottom line still fell short of what the Street had modeled.
The quality of the quarter needs some unpacking. GAAP net income fell to $26.3 million from $39.2 million a year earlier, but the year-ago figure was inflated by a $40.9 million gain on asset sales. Strip that out and the underlying improvement is real. Gross margin of about 36% sits above the first half of 2026 and well above 2025 levels. The drag sits lower in the income statement. SG&A climbed roughly $5 million sequentially to $44.4 million after the TCO acquisition, and litigation provisions continue to flow through results. The balance sheet now carries a $53.4 million legal settlement accrual tied to the Impulse patent case. Cash generation held up, with $32 million of free cash flow versus $30 million in Q2. However, conversion slipped to 58% from 63% as inventories rose by about $35 million. Cash fell to $189 million from $222 million after the $63 million TCO closing. There is still no bank debt.
The call added substance to the growth narrative:
- **North America land:** Revenue jumped 11% sequentially to $146 million. Two Permian cementing-tool share wins, including displacing a competitor at a large IOC, should add roughly $1 million of monthly revenue starting late in Q4.
- **International and offshore:** Revenue rose 5% to $119 million despite subsea delivery timing slippage.
- **Subsea order book:** It broadened meaningfully. Wins include a five-year Indonesia wellhead contract worth more than $30 million, Malaysia follow-ons through the OneSubsea alliance, and a North Sea fishing MSA that displaces the incumbent. The first 20K wellhead was also installed for a new major operator offshore US.
- **Far East outlook:** Management raised expected 12-month Far East project revenue to about $53 million from about $41 million at Q2, with less than $2 million recognized so far.
- **Middle East channel:** The first direct purchase agreement with a major national oil company bypasses local agents. Management expects more direct awards and described them as margin-accretive.
The forward-looking pieces are what changed the setup. For the first time, management offered an informal 2027 framework of roughly 10% revenue growth. It paired that with about 35% incremental margins as the company works toward its 25% EBITDA margin target. Venezuela moved from quoting activity to a quantified opportunity:
- a more than $5 million tubular award;
- about $50 million of tenders quoted;
- roughly $10 million of revenue targeted for 2027 and $20 million for 2028.
Bears have legitimate ammunition, though. The Middle East outlook shifted from "relatively flat" at Q2 to an expected Q4 decline on lower Saudi drilling. Conflict-related freight costs continue to run about $1 million per quarter. Q4 guidance of $260-270 million in revenue and $53-58 million in EBITDA is essentially flat sequentially at the midpoint, which Earnings Whispers characterizes as in-line. Management also tied the 2027 framework to Venezuela stability and to the Middle East holding at Q3 levels. Both are geopolitically exposed assumptions. ROCE eased to 10% on a trailing basis from 12% at Q2.
Investor sentiment remained positive but weakened, slipping from 0.16 to 0.08 ahead of the report. Expectations were cooling rather than collapsing. The shares have held up better than that mood suggests. At $30.00, the stock is up 4.2% since the open following the August report and trades about 10.5% above its $27.15 200-day moving average. Earnings Whispers' AVWAP trend is positive, while the price trend is neutral. The stock has been grinding higher rather than breaking out.
The bottom line is that Innovex's EPS miss looks less consequential than the operating evidence beneath it. Revenue, margins and backlog all improved, and management offered its first concrete multi-year framing. Near-term guidance is flat, the Middle East is softening, and acquisition-driven SG&A and litigation costs keep diluting per-share results. The investment case now depends on whether subsea backlog conversion, Permian share gains and Venezuela can deliver the roughly 10% growth management sketched for 2027, despite the geopolitical exposure built into those assumptions.
Read our earnings preview for Innovex International, Inc.: https://www.earningswhispers.com/article/INVX/21209
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-20 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-21 | |
| Jul-01 | |
| Jun-15 | |
| May-07 | |
| May-04 |
