Lear's Buyback-Fueled EPS Beat Masks A China-Driven Revenue Cut As Guidance Hinges On Margin Execution
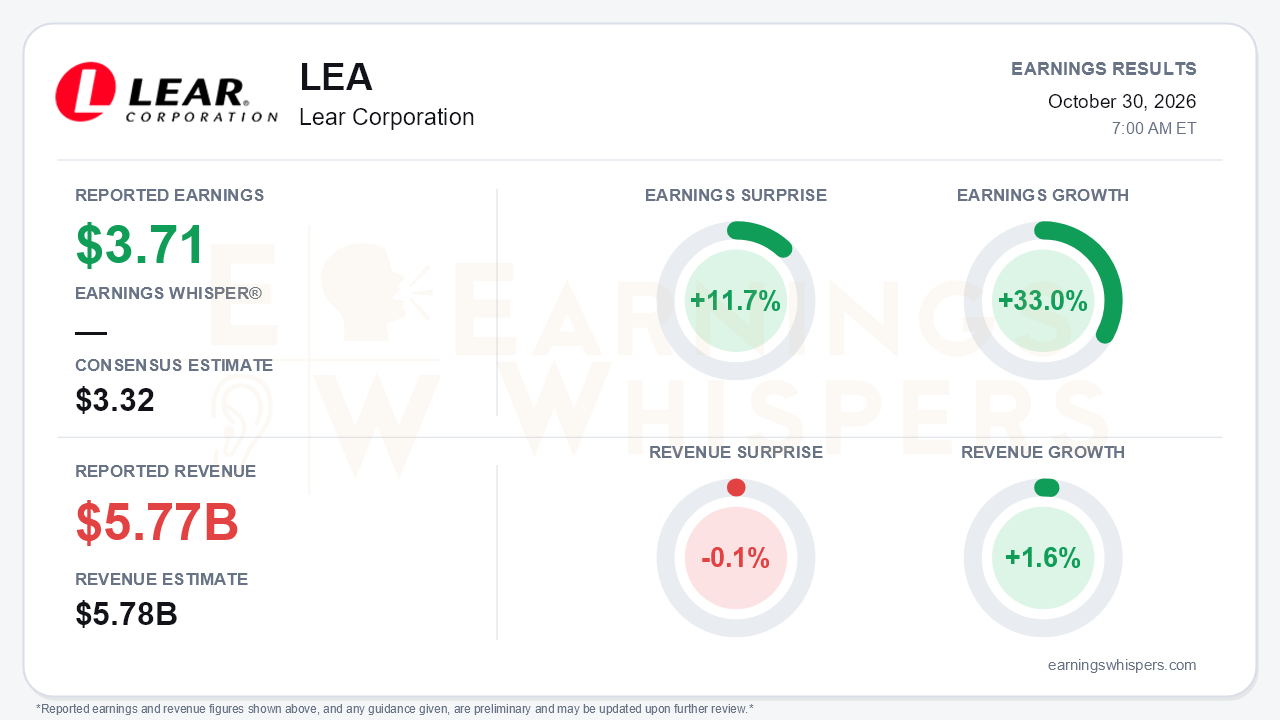
Lear Corporation delivered a clean earnings beat that comes with an important caveat. Adjusted EPS of $3.71 topped the $3.32 consensus by 11.7% and grew 33.0% year over year, a clear acceleration from roughly 23% growth in the second quarter and 24% in the first. Revenue told a different story. Sales of $5.773 billion slightly missed the $5.78 billion consensus and grew just 1.6%, extending a deceleration from 5% in Q1 and 3% in Q2. Management also cut its full-year revenue outlook for the first time this year while holding core operating earnings guidance. That is the central tension: Lear is still growing per-share profits, but it is doing so through cost actions and capital return while its top line loses momentum.
The quality of the beat deserves scrutiny. Core operating earnings rose a more modest 6% to $256 million, and margin improved only 20 basis points to 4.4%. Adjusted net income grew 23%, so roughly a third of the EPS growth came from a 7% decline in diluted shares, to 49.9 million from 53.7 million. A larger favorable tax adjustment within the non-GAAP reconciliation, $11.0 million versus $2.1 million a year ago, also flattered the adjusted figure. GAAP EPS of $2.74 rose 36%, so the improvement is not purely an adjustment story. Still, cash generation weakened. Operating cash flow fell to $329 million from $444 million, and free cash flow nearly halved to $158 million as capital spending climbed to $171 million. Year-to-date free cash flow of $420 million remains well ahead of last year's $246 million.
Beneath the consolidated numbers, results diverged sharply by segment and region. E-Systems was the standout. Adjusted margin rose 60 basis points to 4.8%, and year-to-date net performance of 105 basis points is running ahead of the 80-basis-point target. Seating was steadier but less convincing. Adjusted margin improved to 6.3% from 6.1%, but GAAP margin slipped to 5.5%, and year-to-date net performance of only 30 basis points needs a fourth-quarter step-up to reach the 40-basis-point goal. Geographically, Europe and Africa sales jumped 12% and content per vehicle there rose to $505 from $453. Asia sales fell nearly 10%, and North American sales declined despite higher content per vehicle.
That Asia weakness drives the guidance change. The revenue midpoint fell about $225 million to roughly $23.6 billion, reversing most of Q2's $165 million raise, and management tied about 90% of the cut to China production schedules. The cut came even though Lear improved its global industry production assumption to about -1% from worse than -2%. That combination points to platform-specific exposure rather than a broad industry slump. Management is counting on restructuring savings, now targeted at about $95 million instead of $80 million, and operational execution to offset lower volume and rising copper and launch costs. Bears have legitimate ammunition here. Restructuring costs rose $25 million, the wide fourth-quarter operating earnings range was not tightened despite reliance on unresolved commercial negotiations, a copper revaluation gain will not recur in 2027, and longtime CFO Jason Cardew is retiring. Management continues to frame 2027 as a year of limited growth.
The call did preserve a credible longer-term growth story. Year-to-date net business awards rose to about $3.9 billion from $2.9 billion at Q2, roughly 23% with Chinese automakers. Highlights included the largest complete-seat award in Lear's history with Mahindra, BYD programs in Thailand and Indonesia, and a Chinese luxury EV seat program. Modular thermal awards reached 47, up from 33 three quarters ago. Management also disclosed a roughly $2.25 billion three-year core backlog. The automated Orion, Michigan seating plant launches early next year with targeted 10-15% conversion cost savings and is intended as a template for other facilities. The repurchase authorization was expanded to $1.5 billion through 2029, about 26% of market capitalization.
The market setup was decidedly sour going in. Shares entered the report at $117.38, down 16.4% from the open after the July report. They sat 8.6% below the 200-day moving average and just 3.6% above the inter-earnings low set on October 23, about 19% beneath the post-July high. Investor sentiment deteriorated meaningfully, sliding from slightly negative at -0.09 to -0.36. The Earnings Whispers trend readings are mixed, with price and AVWAP trends negative while momentum is positive.
The bottom line is that Lear beat on the line investors watch most, but the beat leaned on buybacks, tax items and cost savings while revenue guidance moved lower on China. The award pipeline, E-Systems margin progress and capital return support the longer-term case. Near-term credibility now rests on whether Seating execution and commercial recoveries can deliver a fourth quarter strong enough to hold the earnings range against weakening volume.
Read our earnings preview for Lear Corporation: https://www.earningswhispers.com/article/LEA/21289
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-22 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Sep-24 | |
| Sep-24 | |
| Sep-15 | |
| Sep-08 | |
| Sep-02 | |
| Aug-13 |
