NVent Beats And Raises Again, But Lagging Orders And A Q4 Slowdown Keep The Bulls On The Defensive
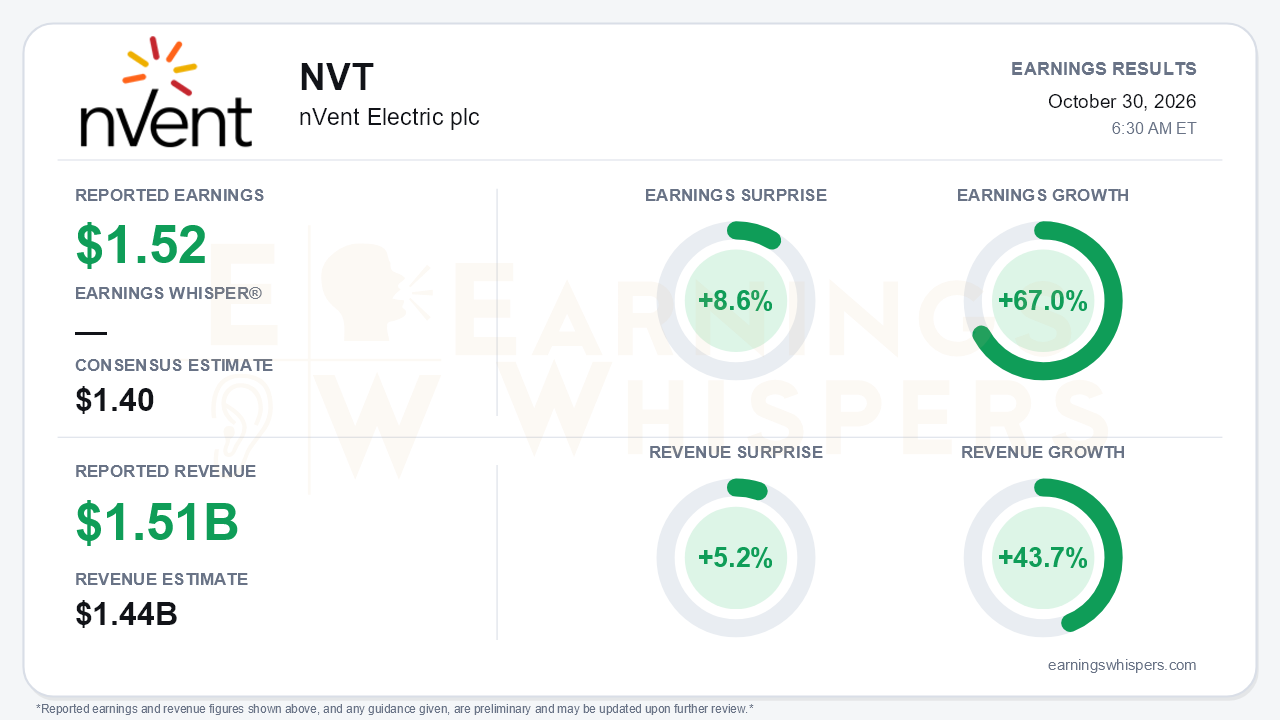
nVent Electric delivered a third consecutive large beat-and-raise in the third quarter. Adjusted earnings of $1.52 per share topped the $1.40 consensus by 8.6% and grew 67.0% year over year. Revenue of $1.515 billion beat the $1.44 billion estimate by 5.2% and rose 43.7%. The quarter also cleared management's own bar by a wide margin: the Q3 guide called for $1.35-1.38 in EPS and 32-35% organic growth. Full-year adjusted EPS guidance moved up again, to $5.36-5.39 from $5.00-5.10, and it now sits more than $1.30 above the $4.00-4.15 range offered in February. The central tension is that the fundamental story keeps getting stronger while the forward indicators that drive sentiment, orders and next-quarter growth, are cooling. The stock has been punished in the meantime.
The quality of the quarter was high. Return on sales reached 22.1%, up 190 basis points from a year ago. That extends an improving margin trend from flat in Q1 and +110 basis points in Q2. Systems Protection did the heavy lifting with 54% organic growth and a 23.0% margin, up 260 basis points. Infrastructure grew roughly 90% within that segment and more than 70% company-wide. Free cash flow climbed to $268 million from $167 million in Q2. The weak spot was Electrical Connections, where margin fell 180 basis points year over year to 28.2% on inflation and growth investment. Even there, the sequential trend is constructive, up from 24.4% in Q1 and 27.3% in Q2. Headline growth did decelerate from Q2's 53% reported and 47% organic, but Q2 faced an easier comparison, so the slowdown looks more like math than a demand problem.
The more encouraging development on the call was the broadening of growth beyond data centers. Industrial grew high teens and commercial-residential mid-teens in Q3, compared with low-single-digit and flat results in Q2. Management raised its full-year outlook for both to high-single-digit growth from mid-single-digit. Every geography grew double digits, including a Europe that was shrinking or barely growing in Q1. Backlog rose to $2.6 billion from $2.5 billion. The CEO described October orders as very strong and said he sees no slowdown in data center urgency.
Bears still have legitimate ammunition:
- **Orders lag sales.** Organic orders grew only low double digits for a second straight quarter, against 44% organic sales growth, versus roughly 40% order growth in Q1. Management points to a 65% prior-year comparison, but a widening gap between orders and shipments is exactly what investors watch late in a capex cycle.
- **Q4 slowdown.** Fourth-quarter organic guidance of 26-29% is a clear step down, partly reflecting supplier capacity constraints that management says it is treating prudently.
- **Cost headwinds.** The tariff assumption rose again, to about $105 million from $80 million at the start of the year, and corporate costs moved up to about $145 million.
The Maverick Power acquisition, closed October 1, reshapes the forward picture. The deal adds a roughly $700 million revenue run-rate in low- and medium-voltage switchgear and about 19 points to Q4 sales growth. Management says it roughly doubles nVent's content per megawatt in data centers. Combined with a planned 800V DC power rack and a modular liquid cooling platform now taking orders, it gives nVent a credible integrated power-plus-cooling offering. The costs are real, though:
- Maverick runs at mid-teens operating margins, so Q4 margin expansion narrows to about 60 basis points and incremental margins fall to the low 20s.
- Total debt rose to $2.2 billion from $1.5 billion after an $800 million note offering, though leverage is guided to 2-2.5x.
- A new 400,000-square-foot Arizona engineered buildings facility, due mid-2027, adds capacity but also commits more capital.
The market has not been rewarding the fundamental progress. Shares entered the report at $138.15, down 15.7% from the open after the July release. They sat 22.1% below the August 17 high of $177.38 and about 4.5% under the 200-day moving average. The stock did rebound 14.1% off its October 23 low of $121.04 heading into the print. Investor sentiment fell sharply, from 0.50 to 0.09, which leaves it barely positive. That reset lowers the bar, but it also shows how much conviction has drained out of the AI-infrastructure trade around this name. Trend readings are mixed: momentum remains positive while AVWAP is still negative, consistent with a stock that has stabilized but not repaired its post-August damage.
The bottom line is that nVent's reported results and guidance remain among the strongest in electrical infrastructure. Margins are expanding, growth is broadening, and Maverick materially enlarges the data center opportunity. Investors, however, have shifted their attention to second-derivative signals: orders running well behind sales, a decelerating Q4 organic guide, supplier constraints, and acquisition-driven margin dilution and leverage. With sentiment already deflated and the stock below its 200-day average, the debate now centers on whether the strong October order commentary turns into reaccelerating order growth in coming quarters.
Read our earnings preview for nVent Electric plc: https://www.earningswhispers.com/article/NVT/21293
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-27 | |
| Oct-22 | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 |
