LiveWire's Narrower Loss And 38% Sales Growth Are Overshadowed By A Going-Concern Warning, Withdrawn Guidance And A Restructuring Committee
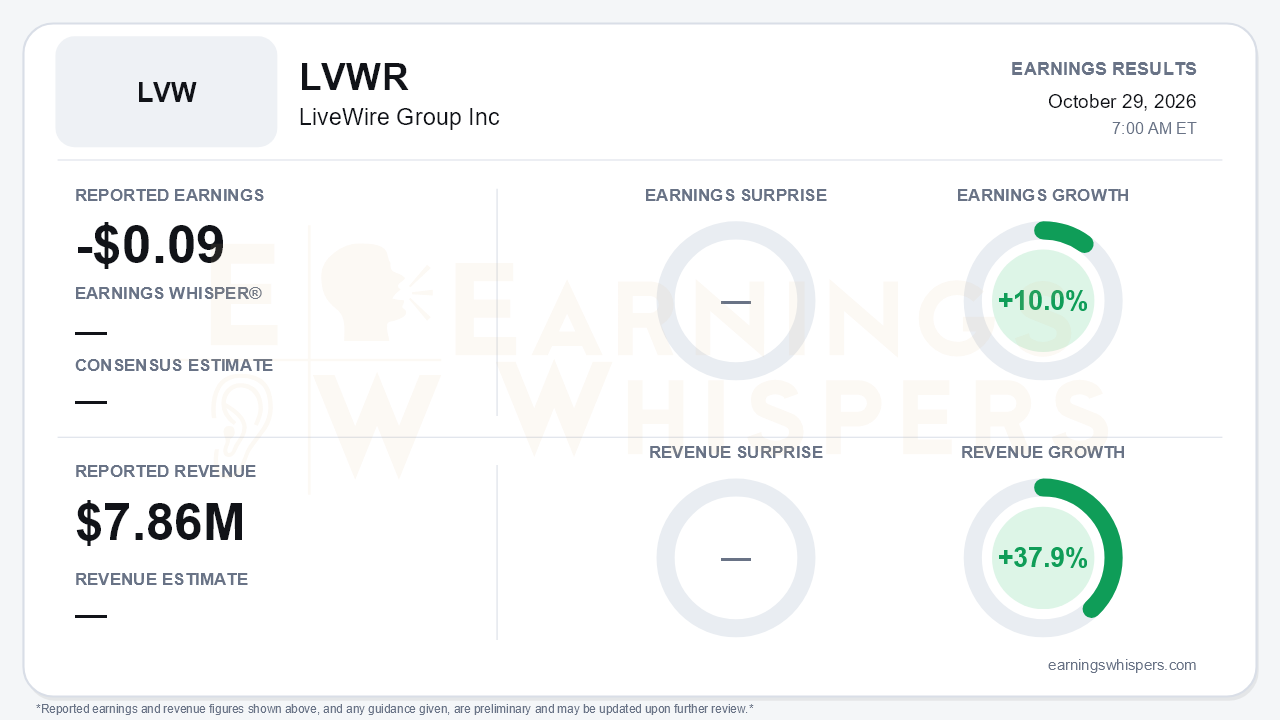
LiveWire Group posted another quarter of incremental operating progress, but it no longer matters much. For the September quarter the company lost $0.09 per share on revenue of $7.86 million. Earnings improved 10.0% from the prior-year loss of $0.10, and revenue grew 37.9%. No consensus estimate or Earnings Whisper was available. The real news came elsewhere in the release. Management disclosed substantial doubt about the company's ability to continue as a going concern. It withdrew full-year guidance for a $70 million to $80 million operating loss and formed a Special Restructuring Committee. The committee appointed a Chief Restructuring Officer, Roy Gallagher, as principal executive officer. That is the central tension: the operating story modestly improved just as the equity story moved into restructuring territory.
The quality of the earnings improvement deserves scrutiny. The operating loss narrowed to $17.5 million from $18.8 million, and adjusted EBITDA improved to negative $14.7 million from negative $16.5 million. Below the operating line, however, a new $1.5 million of related-party interest expense on the Harley-Davidson term loan offset most of those gains. Pretax loss was essentially flat at $19.4 million versus $19.3 million. The year-over-year improvement in net loss came largely from a $0.8 million tax benefit. Gross results did improve. Cost of goods sold of $8.2 million still exceeded revenue, but the gross loss shrank to roughly $0.4 million from nearly $2.9 million. Some of that gain was easy, because the prior-year quarter was depressed by heavy incentives. Selling, administrative and engineering expense rose $1.2 million, partly because last year's figure benefited from stock-compensation forfeitures.
Underlying demand was genuinely better. Consolidated units rose 21% to 7,233. Electric motorcycle units climbed 31% to 241, and segment revenue jumped 178% to $2.7 million. The company claimed 80% year-to-date share of the U.S. 50+ kilowatt on-road EV segment. STACYC units rose 20%, but revenue grew only 9%, and the segment's small operating loss widened on higher freight costs. The S4 Honcho, the product meant to drive 2026 volume, began U.S. deliveries of the Trail version in August, with the Street version and European shipments following this fall. The trajectory is slowing, though. Harley-Davidson's segment disclosures put LiveWire revenue growth at 41% this quarter, down from 87% in the first quarter. That figure differs from LiveWire's standalone 38% because the parent reports the segment on a different basis. On either measure, a few hundred motorcycles a quarter cannot close an operating loss running above $17 million.
The balance sheet explains the urgency. Cash fell to $39.9 million from $82.8 million at year-end, a $42.9 million drain in nine months. Shareholders' equity turned negative at $5.5 million. The roughly $77 million related-party term loan matures in December 2027, which the company explicitly cited in forming the restructuring committee. On the Harley-Davidson call, an analyst noted that cash could roughly halve by year-end, against a street model of about $60 million in 2027 losses. Management declined to comment beyond its disclosures. Harley-Davidson reiterated that it will not fund LiveWire's operating losses. That stance has hardened since the parent cut the term loan to $75 million from $100 million last year. Harley-Davidson's own outlook is improving, with retail and wholesale unit and operating income guidance raised. The parent is clearly ring-fencing LiveWire, so its strength offers no backstop.
The guidance withdrawal is telling for what it is not. A year-to-date operating loss of $53.2 million left LiveWire roughly on pace for its prior range. The guide was pulled because of the strategic process, not because operations collapsed. The committee's mandate is broad: it may pursue debt or equity financing, a sale, recapitalization or restructuring. Its power to rule on conflicts of interest, including those involving a controlling shareholder, signals that any outcome could reshape the capital structure. Bears have legitimate ammunition here. Significant dilution, asset sales or a transaction that subordinates common holders are all plausible paths.
The market had already been pricing distress. Shares opened at just $0.93 after the July report, far below the $1.57 200-day moving average. The release also flags the company's ability to satisfy NYSE listing requirements as a risk. Better unit trends and a narrower adjusted EBITDA loss do little to change that setup when the funding question dominates.
The bottom line is that LiveWire delivered its best operating comparison in some time, yet the quarter will be remembered for the going-concern warning. Unit growth, market share and the Honcho launch show the product has traction. With roughly $40 million of cash, negative equity, no parent support and a restructuring officer now running the company, equity holders' outcome depends on the terms of whatever transaction emerges.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 |
Harley-Davidson Wanted an Electric Revolution. That Dream Is in Trouble
LVWR +10.71%
The Wall Street Journal
|
| Oct-26 |
?? Under the Radar: Harley-Davidson's Electric Bike Spinoff Appoints Restructuring Officer
LVWR
The Wall Street Journal
|
| Oct-20 | |
| Oct-02 | |
| Aug-21 | |
| Aug-10 | |
| Aug-04 | |
| Jul-29 | |
| Jul-23 | |
| Jul-23 | |
| Jul-17 | |
| Jun-09 |
