MasTec's Record Backlog Outruns Pipeline And Communications Stumbles, But A 36% Slide Shows Investors Want Proof
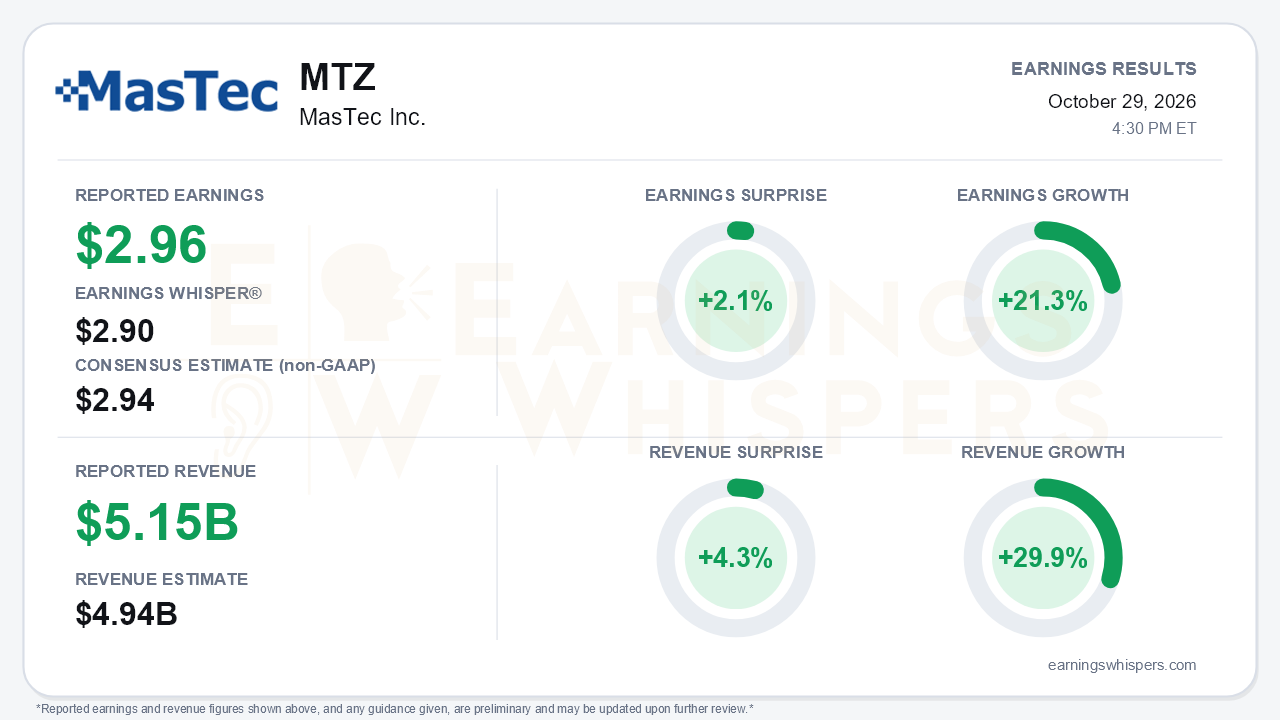
MasTec (NYSE: MTZ) delivered a third quarter that beat the Street on both lines. Adjusted EPS of $2.96 topped the $2.94 consensus by 2.1% and cleared the $2.90 Earnings Whisper number. Revenue of $5.152 billion, a quarterly record, beat the $4.94 billion consensus by 4.3%. Earnings grew 21.3% year over year and revenue rose 29.9%. The headline is not the real story, though. That story is an 18-month backlog that jumped $3.2 billion in a single quarter to a record $24.5 billion, up 46% year over year, set against a trimmed 2026 outlook as Pipeline delays and a deteriorating Communications segment weigh on near-term earnings. That is the central tension. Demand is clearly accelerating, but execution and timing are now limiting how much of it reaches this year's numbers.
The quality of the beat deserves scrutiny. Revenue ran well ahead of the company's own $4.9 billion target, yet adjusted EPS came in slightly below management's $2.98 guide. The upside, in other words, did not reach the bottom line. Adjusted EBITDA margin was flat at 9.4%. On a GAAP basis, diluted EPS fell to $1.89 from $2.04, and GAAP net income margin slipped 90 basis points to 3.3%. Much of that gap reflects intangible amortization, which more than doubled to $75 million after the Superior acquisition. Interest expense also rose, and restructuring and acquisition costs added further pressure. Cash flow was a bright spot in the quarter, with operating cash flow of $267 million versus $89 million a year ago.
Beneath the consolidated figures, the segments are diverging sharply. Power Delivery carried the quarter: revenue rose 65%, EBITDA climbed 132%, and margin expanded 380 basis points to 13.2%. Management said both the legacy business and Superior beat their targets. Legacy Power Delivery posted an organic book-to-bill above 1.5x, its strongest booking quarter ever. Superior's backlog grew to $1.8 billion from $1.4 billion at acquisition. Clean Energy and Infrastructure grew revenue 34% and remains on track for roughly 42% full-year growth, although its $1.825 billion in revenue fell short of the roughly $1.9 billion guide and the 10-Q flagged productivity issues on some projects. The weak spots were severe:
- Pipeline revenue rose 21%, but EBITDA fell 18% and margin collapsed 500 basis points to 10.4%. Permitting delays averaging about 60 days left crews and equipment idle.
- Communications revenue fell 11.8% and segment EBITDA margin dropped to 6.7%. Management cited carrier reorganizations, uncertainty around a fourth carrier, and wireline execution problems.
Forward-looking signals are unusually strong for a quarter that ended with a guidance trim. Management described limited notices to proceed on more than $1 billion of gas-generation work, with demand well above its May Investor Day views. It also cited roughly 2,100 miles of hyperscaler-related long-haul fiber awards, early work agreements on large turnkey data center pursuits, and comfort with 2027 consensus. Pipeline backlog rose 26% sequentially, which supports the claim that delayed revenue is shifting into 2027 rather than disappearing. Bears still have legitimate ammunition:
- Communications is now framed as roughly flat in 2027, and outside consultants have been engaged to deliver about 200 basis points of margin improvement.
- Net leverage rose to 2.5x from 1.8x, and net debt nearly doubled to $3.7 billion since year-end.
- Year-to-date operating cash flow of $388 million leaves a heavy fourth-quarter lift to reach the reaffirmed target of more than $1 billion.
- Q4 guidance is now a range, with the low end assuming a slower Pipeline ramp.
The market setup is more complicated than the surprise implies. Shares entered the report at $177.82, down 35.8% from the $277 open after the July release and 41.2% below the 200-day moving average of $302.21. The Earnings Whispers price and AVWAP trend readings both remain negative. Investor sentiment weakened meaningfully, falling from 0.31 to 0.07. It remains barely positive, but much of the earlier enthusiasm has drained away. That repricing suggests the market had already discounted Pipeline and Communications disappointments well before this release.
That backdrop changes how the quarter should be read. The full-year adjusted EPS guide of $8.92 to $9.30 still implies 39% growth at the midpoint, and management characterized the Adjusted EBITDA revision as about 1% at the midpoint. A stock that has fallen this far is pricing in more damage than the guidance itself shows. The question is whether investors trust conversion of the backlog more than they fear further slippage.
The bottom line is that MasTec's demand story got materially stronger this quarter while its near-term execution got weaker. A record $24.5 billion backlog, accelerating Power Delivery, and new gas-generation and data center catalysts preserve a credible multi-year growth narrative. Thin EPS upside, Pipeline margin compression, an unresolved Communications reset, and higher leverage mean the burden of proof now rests on fourth-quarter Pipeline ramp, cash generation, and evidence that the delayed work truly lands in 2027.
Read our earnings preview for MasTec Inc.: https://www.earningswhispers.com/article/MTZ/21223
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-16 | |
| Oct-12 | |
| Oct-09 | |
| Sep-10 | |
| Aug-27 | |
| Aug-27 | |
| Aug-18 | |
| Aug-17 |
