Sensient Beats As Natural Color Conversion Builds, But Decelerating Growth And A Narrowed Guide Temper The Quarter
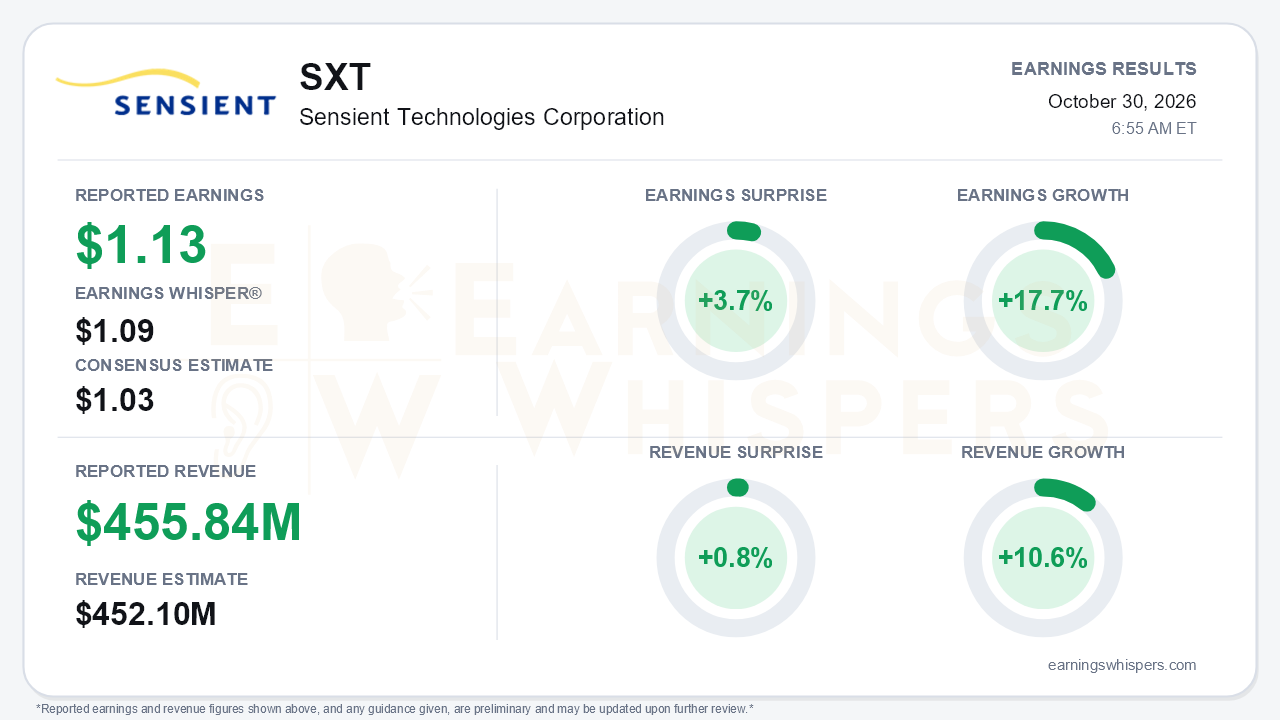
Sensient Technologies (NYSE: SXT) delivered a clean beat in the third quarter. Earnings were $1.13 per share against a $1.03 consensus and a $1.09 Earnings Whisper number, a 3.7% surprise. Revenue of $455.8 million edged past the $452.1 million estimate by 0.8%. Earnings grew 17.7% year over year and revenue rose 10.6%. Natural color conversion is building just as the bull case requires. The central tension is that the momentum of the past two quarters is cooling: EPS growth decelerated, consolidated guidance was reaffirmed rather than raised, and the conversion ramp is arriving more slowly than headline enthusiasm implies.
The GAAP comparison flatters the quarter. Reported diluted EPS jumped 29.9% from $0.87, but last year's period carried $3.3 million of Portfolio Optimization Plan costs. On an adjusted, local-currency basis, EPS growth was 17.7%, operating income rose 18.6% and adjusted EBITDA rose 15.4%. Those are healthy numbers, yet the call analysis shows a clear step down from the second quarter, when adjusted EBITDA grew 21% and EPS 26%. Part of that gap reflects a Q2 tariff refund, so the comparison is noisy, but the direction is unmistakable.
Color remains the engine. Segment revenue rose 18.1% to $210.3 million, and operating income increased 22.0% to $46.1 million. Asia Pacific was the standout. Local-currency revenue grew 14.8%, operating income rose 32.4%, and EBITDA margin expanded 330 basis points to 27.5%. Flavors & Extracts grew a more pedestrian 3.2% in local currency, though its margin improved 80 basis points to 18.5%.
The conference call kept the multi-year growth story intact while adding some caveats. Natural color conversion revenue reached roughly $30 million in the quarter, up from $25 million in Q2. That brings the cumulative total to about $75 million and implies an annualized run rate above $160 million. The regulatory and consumer backdrop also looks supportive. FDA synthetic color certifications are down nearly 10% over the trailing year, and 85% of new U.S. launches in the quarter were naturally colored.
The ramp itself is the concern. First purchase orders on conversions are running at about 10% of annualized value versus the typical 25-30%, as customers sell off synthetic inventory before switching. Management now frames the $1 billion target as a run rate approached by the end of 2028, with launch dates slipping later rather than earlier. An analyst openly questioned whether that represents a timeline slip.
Other details also leaned softer. Color EBITDA margin of 25.1% slipped from 26.3% ex-tariff in Q2, although management called a 25% margin sustainable through 2027. Personal care colors slowed on tariff-driven supply-chain shifts.
Guidance reinforces the deceleration theme. Sensient raised the low end of its GAAP EPS range to $4.15, narrowing guidance to $4.15-$4.20. Local-currency revenue, adjusted EBITDA and adjusted EPS targets were only reaffirmed, after raises in both Q1 and Q2. With $3.37 earned through nine months, the range implies a softer fourth quarter, which management attributed to seasonality and customer destocking. Asia Pacific's full-year revenue outlook did move up to low double digits from high single digits.
The balance sheet deserves scrutiny. Nine-month operating cash flow fell to $75.3 million from $83.3 million despite sharply higher earnings. The main drag was a $117.2 million inventory build and a $71.2 million increase in receivables. Capital spending nearly doubled to $105.8 million, with the full-year figure pinned near $160 million. Long-term debt climbed to $790 million from $709 million at year-end. Net leverage sits at 2.3 times, and management expects free cash flow to stay pressured until roughly 2028, with leverage rising through 2027. That is the cost of building capacity for natural colors, and it makes execution on the conversion ramp more consequential.
Investor expectations were modestly elevated going in. Earnings Whispers sentiment was roughly unchanged, ticking up from 0.084 to 0.092, and remains mildly positive rather than euphoric. Shares entered the report at $131.53, up 9.6% since the open after the July report and 15.8% above the 200-day moving average. The stock sits about 5% below the $138.82 52-week high set in late August, during this inter-earnings period. Momentum and AVWAP trend readings remain positive, consistent with a stock the market has rewarded, even though it has drifted off its summer peak.
The bottom line is that Sensient delivered a high-quality operating beat with its strategic thesis intact. Natural color wins are accelerating sequentially, the regulatory tailwind is strengthening, and margins are holding up across segments. However, slowing EPS growth, a reaffirmed rather than raised outlook, a slower conversion revenue ramp, and years of pressured free cash flow make this a steadier and more capital-intensive story than the 29.9% GAAP growth headline suggests. With shares well above trend, investors will need patience on the timing of the $1 billion opportunity.
Read our earnings preview for Sensient Technologies Corporation: https://www.earningswhispers.com/article/SXT/21303
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 11 hours | |
| 11 hours | |
| Oct-29 | |
| Oct-22 | |
| Oct-16 | |
| Aug-18 | |
| Aug-03 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-23 | |
| Jul-10 | |
| Jun-04 |
