NPK International Misses And Cuts Guidance As Dry Texas Weather Stalls Rentals, Leaving The Bull Case On A Q4 Rebound
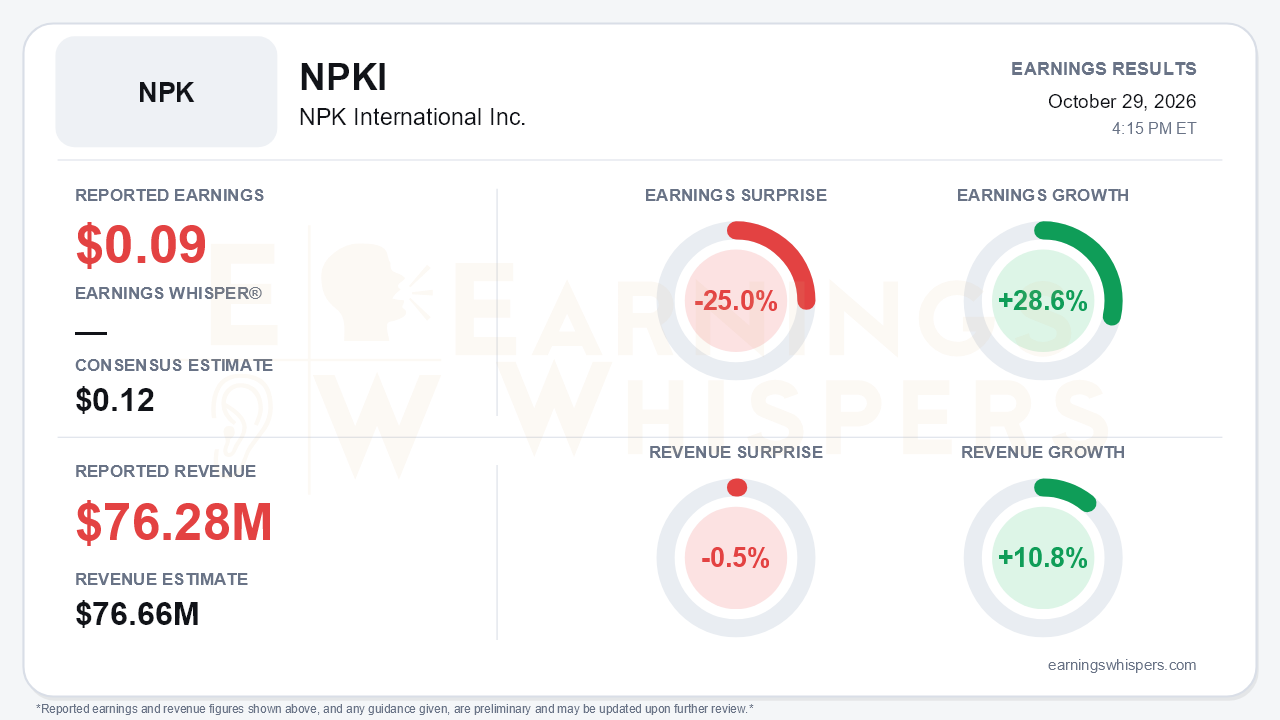
NPK International delivered a quarter that looked healthy against last year but fell short against expectations. Adjusted earnings of $0.09 per share missed the $0.12 consensus by 25.0%, and revenue of $76.28 million came in 0.5% below estimates. Year-over-year comparisons still look solid: adjusted EPS grew 28.6% and revenue rose 10.8%. But the more important development was the guidance cut. Management lowered its full-year 2026 outlook for the second time in the past two quarters' trajectory, reversing the raise it issued after the first quarter. The year-over-year growth is real. The problem is that the sequential momentum broke.
The quality of the quarter deserves scrutiny. On a GAAP basis, income from continuing operations was $0.07 per diluted share, flat with a year ago. The adjusted figure excludes $1.2 million of severance tied to an executive leadership transition and $0.7 million of strategic planning and diligence costs. Adjusted EBITDA rose 30% to $20.0 million, and margin expanded 390 basis points year over year to 26.2%. Against the record second quarter, however, margin fell 530 basis points, revenue dropped from $81.6 million, and GAAP operating income nearly halved to $9.2 million from $16.1 million. Rental revenue was the swing factor, sliding to $31.8 million from $37.2 million in Q2. Cash flow weakened sharply: free cash flow was negative $4.4 million versus positive $12.5 million a year ago. Net debt rose to roughly $22 million from about $4 million at the end of Q1, driven by buybacks, capex and an $11 million working-capital build.
The call pinned the shortfall on Texas. Exceptionally dry weather allowed a key utility customer to proceed with large projects without matting, producing roughly a $6 million sequential rental-and-service decline in that region. Regions outside Texas grew about $2 million sequentially, and management said it would have met or beaten guidance excluding Texas. That argument has merit, but it also exposes customer concentration risk with a single utility. US rental and service revenue was flat year over year.
Product sales add a second, less weather-dependent headwind. Utilities are prioritizing long-lead non-matting capex, so management expects Q4 product sales to fall to the mid-teens of millions, leaving the full year flat after a strong first half. Revenue guidance now sits at $300-$305 million, down from $310-$325 million, and adjusted EBITDA guidance moved to $90-$93 million from $92-$102 million. Organic rental growth for 2026 was downgraded to "modest" from "double-digit." Using the release figures, the new range implies fourth-quarter revenue of roughly $67-$72 million, below the $75.2 million reported a year earlier. The near-term revenue line is softening, not just pausing.
The call nonetheless preserved a credible growth story. Fleet utilization recovered from the low-60s to the mid-70s exiting October, and management guided Q4 rental and service to mid-teens year-over-year growth, which would be a record quarter, with implied EBITDA margin near 33%. Cross-rents fell by about one-third, a margin tailwind, and the 30% full-year EBITDA margin target was reaffirmed. Initial 2027 framing calls for mid-teens rental and service growth, flattish product sales and continued margin expansion. Quoting remains up more than 20% year over year at stable win rates, led by the Midwest and Northeast, with 765kV transmission projects being quoted into 2027-28. Bears have legitimate ammunition here, though: quoting growth has cooled from roughly 30% cited earlier in the year. In addition, manufacturing spend for 2026 slipped to about $20 million from $30-$35 million, even as the Louisiana expansion remains on track for mid-2027. Elevated diesel costs and resin inflation remain cost pressures.
Capital allocation leaned aggressive. NPK repurchased 1.0 million shares for $13.4 million at about $13.37, compared with $3 million in Q1, and has $76 million remaining on its authorization. The stock now trades at $11.20, below that repurchase price and down 12.2% since the open following the July report. Shares sit 19.3% below the $13.88 200-day moving average, and Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment was already negative heading into the report and deteriorated meaningfully, falling from -0.36 to -0.48. Investors were skeptical going in, and the guidance cut gave them more reason to be.
The bottom line is that NPK posted respectable year-over-year growth but missed on earnings and cut guidance, revealing how exposed the rental story is to weather and a concentrated Texas customer base. Management's case now rests on an October rebound turning into a record fourth quarter for rentals and on its 2027 framing holding up. Until that shows up in reported results, a stock trading well below its long-term average and facing souring sentiment is likely to keep the burden of proof on the company.
Read our earnings preview for NPK International Inc.: https://www.earningswhispers.com/article/NPKI/21226
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-21 | |
| Oct-16 | |
| Sep-14 | |
| Sep-02 | |
| Jul-30 | |
| Jul-29 | |
| Jul-28 | |
| Jul-15 | |
| May-02 | |
| Apr-30 | |
| Apr-16 | |
| Feb-26 | |
| Feb-26 |
Stock Of The Day NPK International Rides The Energy Construction Buzz
NPKI
Investor's Business Daily
|
