Pebblebrook Delivers A Third Straight Beat-And-Raise As Pricing Power Takes Over, But Q4 And Early-2027 Softness Temper The Setup
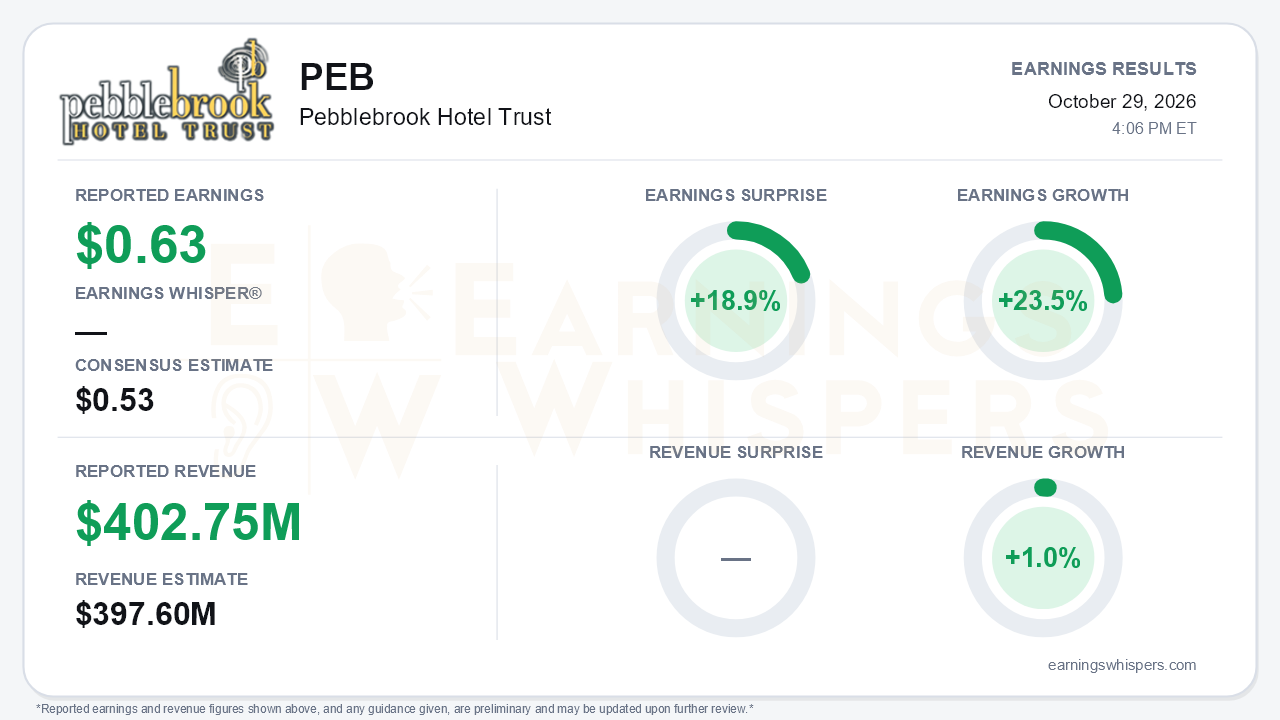
Pebblebrook Hotel Trust delivered another emphatic beat-and-raise. Adjusted FFO came in at $0.63 per diluted share, against a $0.53 consensus. That is an 18.9% surprise and 23.5% year-over-year growth. Revenue of $402.75 million topped the $397.6 million estimate by 1.3%. Management then lifted full-year adjusted FFO guidance to $1.88-$1.92, a $0.17 increase at the midpoint. It was the third consecutive quarter in which results cleared the high end of the company's own outlook, and the call analysis characterizes this raise as the largest of the year. The central development is a change in the character of growth. Pebblebrook's recovery has shifted from filling rooms to charging more for them. Same-property ADR rose 7.0% while occupancy rose only 1.2%.
The headline numbers need some unpacking. Reported revenue grew just 1.0%, which badly understates the operating trend. Nearly $170 million of dispositions over the past year shrank the reported base. Same-property total revenue rose 6.9%, and same-property RevPAR rose 8.3%, against a Q3 RevPAR outlook of only 1%-3% issued in July. On the GAAP side, the net loss widened to $54.6 million from $32.4 million. That reflects $77.3 million of non-cash impairments tied to the Hotel Zags sale and further disposition reviews, not operating weakness. Per-share results also had help from the buyback. Adjusted FFO grew 18.9% in dollars, but share repurchases lifted the per-share gain to 23.5%. Investors should credit both the operations and the capital allocation, while recognizing they are different engines.
Margin performance was the most impressive part of the quarter. Expenses rose just 4.0%, and only 2.7% per occupied room. That produced 58% flow-through, a 15.1% jump in same-property hotel EBITDA and 205 basis points of margin expansion to 28.8%. Resort margins climbed 250 basis points to 32.6%. The quality of that flow-through deserves some scrutiny, however. Management acknowledged on the call that roughly $2.6 million of fixed-cost savings flattered the quarter and will not recur every quarter. The demand picture still looks broad-based:
- Transient ADR rose 8.5%, and corporate transient ADR rose 9.4%.
- San Francisco, Chicago, Los Angeles and Boston all posted double-digit RevPAR gains.
- Management stressed that demand reaccelerated in September, well after the World Cup and America 250 events had passed.
The forward picture is constructive but not seamless. The Q4 outlook calls for RevPAR growth of 4%-6%, a clear deceleration from Q3 that management attributes to seasonality and convention timing. Early 2027 is the bigger soft spot. First-quarter revenue pace is currently negative because the Super Bowl moves to Los Angeles, San Diego and DC convention calendars are weak, and a San Francisco citywide event shifts into the second quarter. Downtown San Diego RevPAR already fell 4.5% in Q3, and international inbound travel has not improved. On the other side of the ledger:
- Overall 2027 revenue pace is running about 5% ahead, with Q2-Q4 pacing up 8% or more.
- Capital spending has normalized lower, supporting free cash flow.
- Net debt to EBITDA has fallen to 5.1x from 5.9x at year-end.
- NAV guidance was raised $1 to $23.50-$27.50.
- Management signaled openness to acquisitions and said NOLs mean no dividend increase is needed in 2027.
The tone shift is notable. Earlier this year management was taking things month by month; it now describes a multi-year pricing upcycle.
The market setup is more complicated than the surprise implies. Shares have climbed 11.4% since the open after the July report, to $21.72. That leaves them roughly 35.6% above the 200-day moving average of $16.02, and the Earnings Whispers price and AVWAP trend readings remain positive. Yet investor sentiment fell from 0.61 to 0.34. Sentiment remains positive, but the decline is meaningful. One reading is that much of the good news was already in the price after a strong run. The $350 million December convertible maturity, rising rates and policy uncertainty give cautious investors reasons to hold back. The stock still trades below the low end of management's revised NAV range, which helps explain why the company keeps buying back both common and preferred shares at a discount.
The bottom line is that Pebblebrook produced a high-quality operating quarter that turnaround skeptics were not positioned for. Rate-led RevPAR growth, real margin expansion, a guidance raise that exceeded the beat, and falling leverage all point the same way. Bears still have legitimate ammunition: a decelerating Q4, a negative Q1 2027 pace, some non-recurring cost help, and GAAP losses driven by impairments. With the stock well extended above its long-term average and sentiment cooling, the next test is whether the improving 2027 pace beyond the first quarter turns into the sustained pricing upcycle management now describes.
Read our earnings preview for Pebblebrook Hotel Trust: https://www.earningswhispers.com/article/PEB/21229
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 11 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-19 | |
| Oct-12 | |
| Oct-09 | |
| Oct-01 | |
| Sep-15 | |
| Sep-11 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jun-16 |
