GLPI Matches The Whisper And Edges Up The Low End Of Its AFFO Outlook, But Bally's Going-Concern Warning And A Weaker Cost Of Capital Now Drive The Story
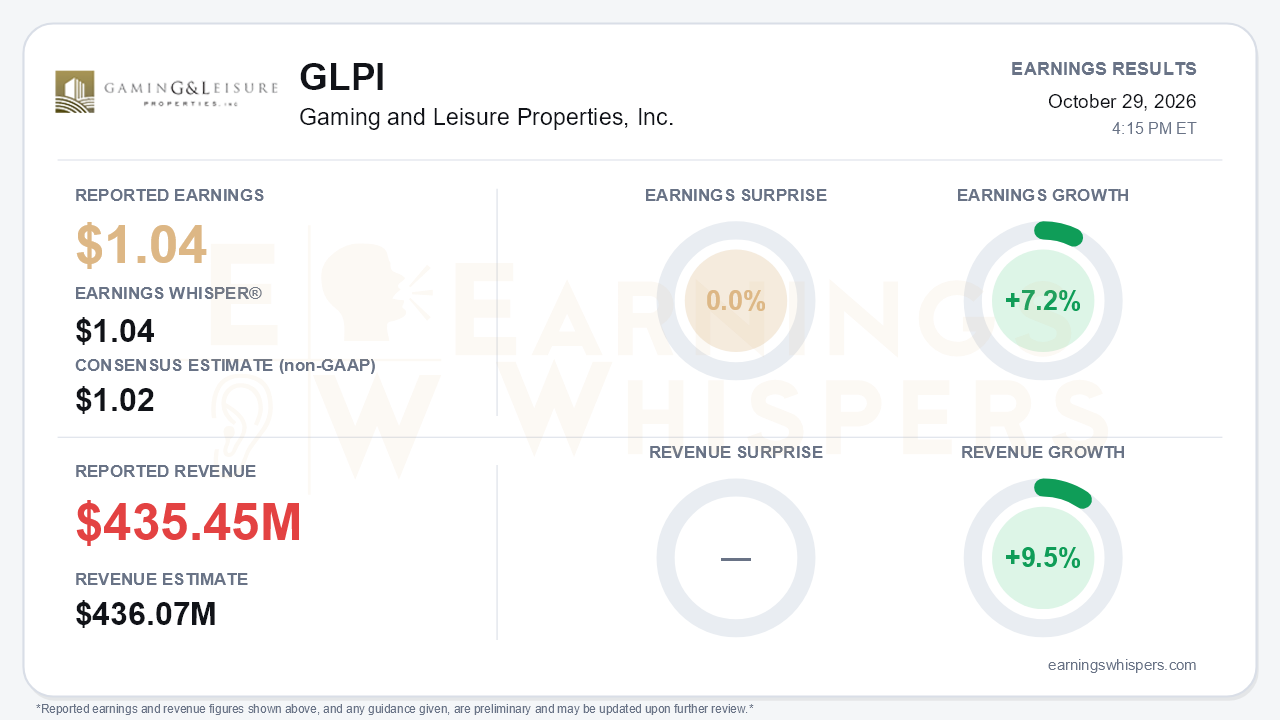
Gaming and Leisure Properties delivered exactly what the market was positioned for, and not much more. AFFO of $1.04 per share matched the Earnings Whisper number and topped the $1.02 consensus. Revenue of $435.45 million was essentially in line, 0.1% below estimates. Earnings grew 7.2% year over year and revenue rose 9.5%, both records according to management. Yet the quarter's central tension had little to do with the headline print. GLPI's own cash flows keep compounding through escalators and development funding. Meanwhile, its largest growth tenant added going-concern language, and management conceded that the company's cost of capital has deteriorated. A reliable earnings stream is now running into a narrower path for external growth.
The quality of the AFFO beat holds up, but the GAAP picture looks worse and deserves explanation. GAAP net income fell to $0.71 per share from $0.85, and NAREIT FFO dropped to $0.92 from $1.08. Most of that gap came from a swing in credit-loss provisions: a $36.2 million charge this quarter compared with a $37.4 million benefit a year ago. That item is non-cash and excluded from AFFO, but it is not meaningless. The call noted operating expenses rose roughly $65 million year over year on those provisions, reversing declines in prior quarters, and the provision reflects tenant outlooks. Per-share growth also trailed dollar growth. AFFO rose 10.5% to $311.7 million, but the diluted share and unit count climbed to 299.6 million from 291.8 million after the June forward-equity settlement.
Beneath the surface, the top line is still accelerating in dollar terms. According to the call, year-over-year growth in real estate income reached about $38 million, up from roughly $35 million in Q2, $24 million in Q1 and $17 million in Q4. Cash income from acquisitions and escalators rose $47 million. Management also cited cash income from the Bally's Chicago lease of about $12 million, compared with $9 million in Q2 and $5.5 million in Q1. Full-year AFFO guidance was narrowed to $4.11-$4.12 per share from $4.10-$4.12, continuing a steady upward creep in the low end since the start of the year. The release puts the dollar range at $1.222 billion to $1.225 billion, while the call summary cites a $1.220 billion low end. Either way, the change is modest, and the guidance excludes new deals.
The risks are new and specific. Bally's added going-concern language to its 10-Q and slowed construction of the Chicago hotel and amenities, which delays the property's full ramp. Management said GLPI's rent is not directly affected, but tenant liquidity is now a live question for a landlord whose Bally's exposure includes 16 facilities plus the Chicago development. Bally's still owes a further roughly $300 million of that $940 million construction commitment. Rent coverage also weakened year over year at the Bally's, Caesars and Cordish leases. The low end of the coverage range sits at 1.61x, slightly better than last quarter's 1.58x but below 1.69x at year-end. Percentage rent is expected to decline by $3.3 million in 2027. Regional gaming revenue is running up only 2-3%, with management flagging high gas prices and Chicago-area video gaming terminal competition.
There are offsetting catalysts. Bally's Chicago is about two-thirds complete, and management reaffirmed a first-half 2027 opening. Funding for the $467 million Cordish Live! Virginia project has begun. The Prologis joint venture turns idle Joliet land into a roughly 20% stake in a planned industrial park. Cap rates have widened about 75 basis points, and management said deals now price at no lower than 8%. Combined with an expected wave of regional asset sales, that improves acquisition spreads. The problem is funding. Management effectively took equity issuance off the table at current prices, a reversal from Q2, and fielded questions about buybacks and joint ventures instead. Leverage of 4.8x leaves some room within the 5-5.5x target, but less than the 4.6x at year-end.
The market has already priced in much of this caution. Shares have fallen 10.7% since the open after the July report, to $39.49, and sit 11.4% below the 200-day moving average of $44.56. The period-end dividend yield was 8.6%, up from 6.7% a year earlier. The Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment remains clearly negative but improved modestly, from -0.494 to -0.436, which suggests expectations have stopped deteriorating rather than turned constructive.
The bottom line is that GLPI's operating engine is intact, and the AFFO line continues to grind higher with little drama. What changed is the external setup. A key tenant now carries a going-concern flag, coverage has softened, and the equity currency that funded past growth is impaired. Until Chicago opens and Bally's balance sheet stabilizes, the stock's discount looks less like a mispricing of a steady earnings stream and more like a fair debate over tenant risk and growth funding.
Read our earnings preview for Gaming and Leisure Properties, Inc.: https://www.earningswhispers.com/article/GLPI/21201
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-21 | |
| Sep-21 | |
| Sep-11 | |
| Sep-10 | |
| Sep-01 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-01 | |
| May-20 |
