CubeSmart's Same-Store Inflection Arrives Behind A Narrow Beat, But Sentiment Has Cooled
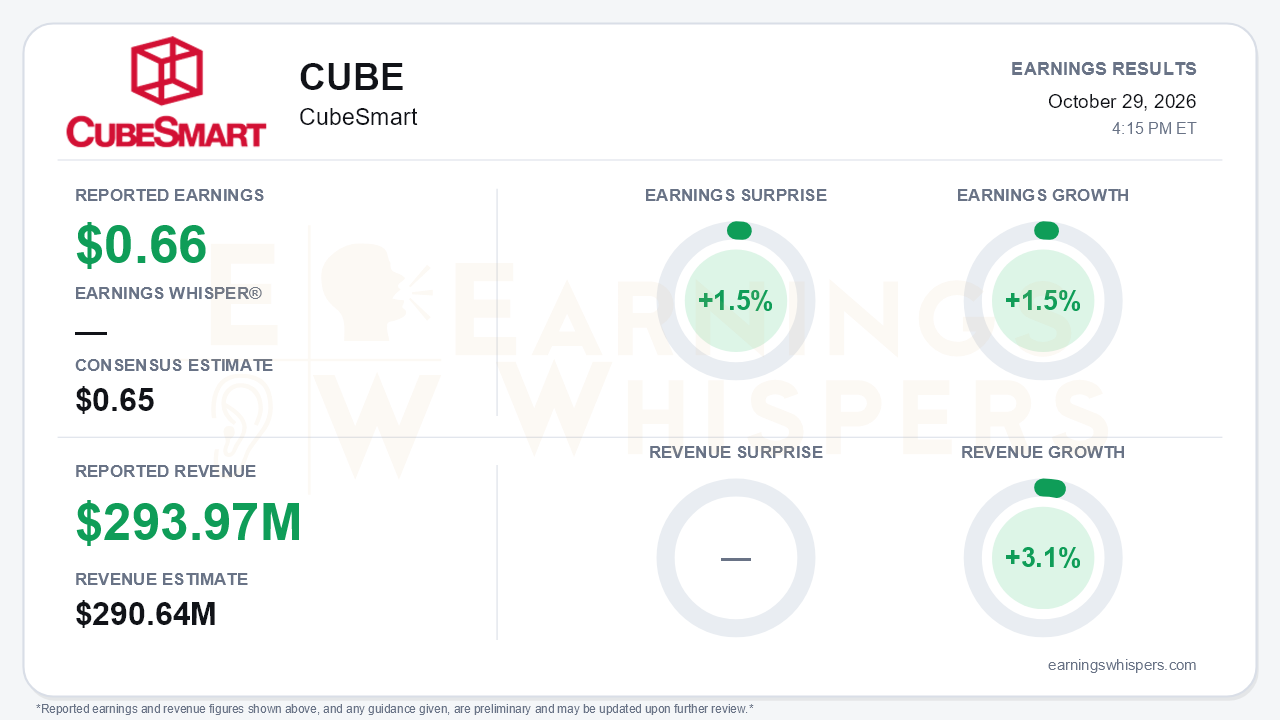
CubeSmart (NYSE: CUBE) produced only a modest headline beat in the third quarter. FFO as adjusted was $0.66 per share, 1.5% above the $0.65 consensus and up 1.5% from a year ago. Revenue of $293.97 million topped expectations by 1.1% and grew 3.1% year over year. The more important development sits beneath that narrow margin. After quarters of flat-to-negative same-store trends, the inflection management had been forecasting showed up in the numbers. Same-store NOI rose 2.1%, after declines of 0.7% in the second quarter and 1.5% in the first. Management raised every full-year same-store and FFO range, and full-year NOI and FFO are now positive at the midpoint. Investors did not appear to be positioned for that.
The quality of the quarter deserves some scrutiny, because the NOI swing owes as much to expenses as to revenue. Same-store revenue growth stepped up to 1.9% from 0.8% in the second quarter and 0.6% in the first. That is genuine acceleration. Even so, realized rent per occupied square foot rose only 0.5%, and fee-driven other property income growth of 16.8% did a lot of the lifting. Management acknowledged that this other-income growth will moderate once the fee changes are lapped in 2027. On the cost side, same-store expense growth slowed to 1.3% from 4.4% in the second quarter and 5.8% in the first. Part of that came from a 10.7% drop in advertising, which management characterized as mostly timing rather than a durable saving, and a 10.9% decline in property insurance. Property taxes and personnel costs still rose about 4%. GAAP EPS climbed to $0.42 from $0.36, but much of that gain reflects a roughly $10.7 million decline in depreciation and amortization rather than operating improvement. The year-over-year FFO gain is the cleaner read.
The call preserved a credible demand story. Same-store occupancy went from flat year over year at the end of June to up 90 basis points at the end of September, ending at 89.9%. Revenue per available foot growth improved to 1.2% from 0.5%. Management said 17 of its top 20 markets are accelerating, with Sunbelt and West Coast markets improving as new supply is absorbed. The trade-off is that the system prioritized volume in July, which left third-quarter move-in rates modestly negative year over year. Those rates turned positive by the end of September and were up low single digits in October, the key datapoint suggesting the occupancy gains are not simply being bought with price. Tucson and some other supply-heavy markets are still decelerating, and management described the recovery as slow and steady rather than a hockey stick, with no housing-market catalyst yet.
The guidance raise was real but measured. Same-store revenue growth is now expected at 1.0% to 1.4%, up from 0.5% to 1.25%. Expense growth improved to 2.8% to 3.8%, and NOI growth moved to 0.0% to 0.8% from a range that was negative at the midpoint. FFO guidance narrowed upward to $2.58 to $2.60 from $2.54 to $2.60. However, the implied fourth-quarter same-store revenue midpoint of about 1.5% is a slight deceleration from the third quarter's 1.9%. Year-to-date FFO as adjusted of $1.92 also still trails last year's $1.94.
Capital allocation is the other moving piece. CubeSmart repurchased $83.9 million of stock at an average of $39.09, bringing year-to-date buybacks to $159.8 million. It funded the redemption of $300 million in senior notes with its revolver, leaving $850 million drawn at quarter end. After the quarter, a $300 million term loan at SOFR plus 80 basis points refinanced part of that balance. The Heitman joint venture, expected to generate roughly $170 million in net proceeds, remains on track for the fourth quarter. The next maturity is not until December 2028, but bond refinancing has been deferred to 2027. Management also flagged rate volatility as a complication for matching buyback timing to joint-venture proceeds. On the other hand, it was more optimistic that the same volatility could sideline levered buyers and open acquisition opportunities.
The market setup is more complicated than the improving fundamentals imply. Earnings Whispers investor sentiment slipped from mildly positive (0.12) to mildly negative (-0.09), a meaningful swing in direction though not an extreme reading. Shares at $41.08 are down 2.3% since the open following the July report, but they remain about 3.8% above the 200-day moving average of $39.56. The trend readings are mixed, with price trend negative while AVWAP remains positive. The stock has gone sideways even as the operating picture improved.
The bottom line is that CubeSmart delivered the inflection it promised. Revenue is accelerating, occupancy is building, October move-in rates are positive, and guidance moved higher across the board. Bears still have legitimate ammunition: a beat leaning partly on timing-related expense relief and fee income, a modest fourth-quarter slowdown, and heavier revolver reliance. Whether pricing power follows the occupancy gains will decide if this recovery is durable.
Read our earnings preview for CubeSmart: https://www.earningswhispers.com/article/CUBE/21178
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-06 | |
| Oct-01 | |
| Sep-25 | |
| Aug-01 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 | |
| Jul-10 | |
| Jul-10 | |
| Jul-06 |
