CNO Financial Crushes Estimates And Raises Guidance Again, But Cooling Sales Growth And One-Time Tailwinds Complicate The Setup
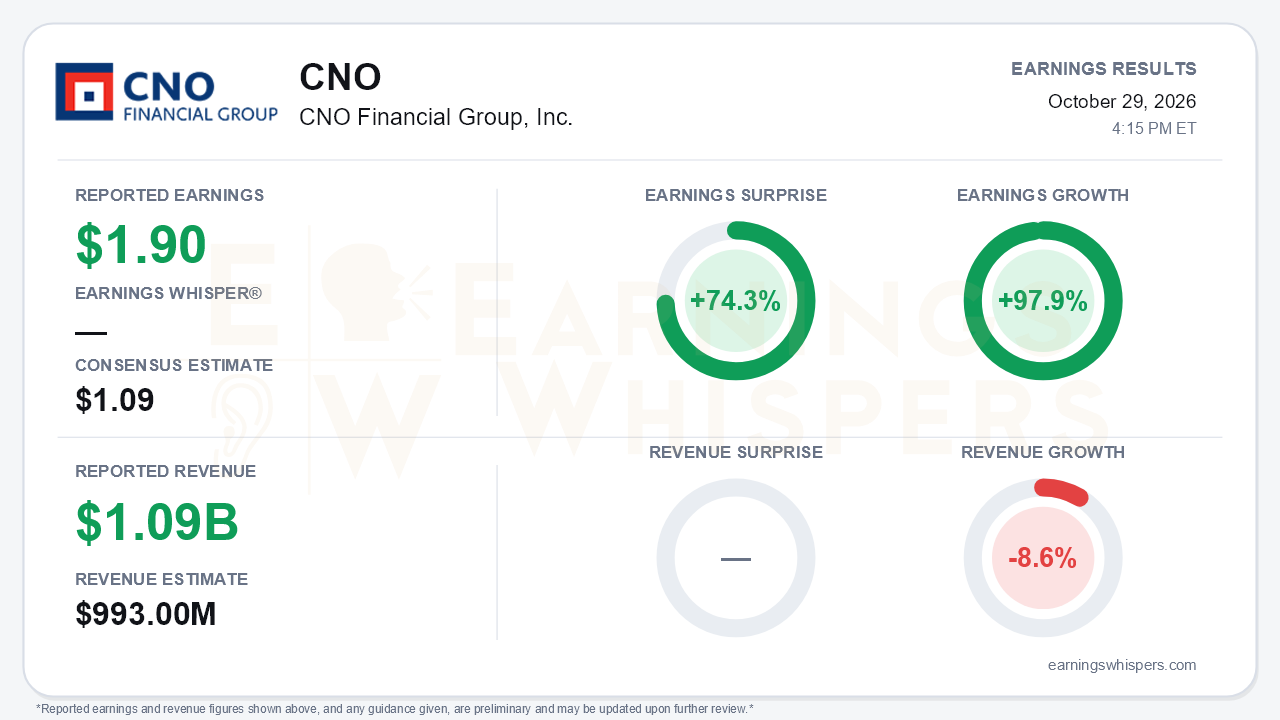
CNO Financial Group delivered one of its strongest quarters in years. Third-quarter operating earnings were $1.90 per share, 74.3% above the $1.09 consensus. Revenue of $1.086 billion beat the $993.0 million estimate by 9.4%. Earnings Whispers measures year-over-year EPS growth at 97.9%, while management cites 47% operating EPS growth; the gap reflects differing treatment of the actuarial-review benefits that inflated both the current and year-ago quarters. Management also raised full-year operating EPS guidance for a second straight quarter, to $5.05-$5.15 from $4.60-$4.80, a 9% lift at the midpoint. The central question is how much of this is durable earnings power and how much is favorable accounting and investment timing. The answer is more durable than skeptics might assume, though not entirely.
The quality of the beat deserves scrutiny. The annual actuarial review contributed $44.9 million, or $0.48 per share, to operating income. Excluding those significant items, operating EPS was $1.42, up from $0.96 a year earlier and still comfortably above consensus. That underlying figure is the more important number, and it shows genuine progress:
- Annuity margin ex-items rose to $67.4 million from $56.3 million.
- Health margin ex-items improved to $141.3 million from $135.9 million.
- Investment income not allocated to product lines jumped to $68.1 million from $39.5 million.
The 8.6% revenue decline is largely noise. It stems from a collapse in policyholder-portfolio income ($6.1 million vs. $116.8 million) and $64.7 million of investment losses. Core insurance policy income actually grew to $688.2 million from $658.4 million. GAAP net income surged to $161 million from $23.1 million, even after $48.3 million of realized losses and a $22.1 million deferred-tax valuation allowance tied to asset sales ahead of the Bermuda reinsurance deal.
The call reinforced an improving profitability story. Net investment income growth accelerated from 6% in the first quarter to 8% in the second and 13% in the third, helped by a 6.24% new money rate. Expense ratio guidance fell to 18.6%-18.8%, and management dropped its earlier "timing" framing, now calling the ratio sustainable with room to improve. The operating tax rate guide fell to roughly 20.5%. Trailing operating ROE ex-items climbed to 14.1%, already past the 12% target set for 2027, and new top-quartile ROE targets are due in February.
Bears have legitimate ammunition beneath that surface:
- **Decelerating sales:** total health NAP growth slowed from 20% to 17% to just 7%, Worksite NAP growth cooled from 29% to 18%, and consumer life NAP fell 9% for a second straight quarter (though management noted it rose 20% excluding a discontinued pilot).
- **Non-recurring investment income:** management acknowledged that about $12 million of unallocated investment income, worth roughly 50 basis points of ROE, ran above long-term expectations and should not persist.
- **Margin and morbidity risks:** management flagged possible mean reversion in product margins, and Medicare Supplement morbidity remains elevated.
- **Cash flow and capital:** the top end of free cash flow guidance was trimmed to $240 million as the larger FHLB program consumed capital. Holding-company liquidity fell to $230.7 million from $351.4 million at year-end. Reported book value per share slipped to $25.34 as rising rates widened the AOCI loss, even as book value ex-AOCI rose 8% to $41.29.
The forward catalysts are real but more incremental. The third Bermuda treaty ceded roughly $270 million of Colonial Penn reserves, and 2027 will focus on optimizing Bermuda assets and capital, subject to regulatory approval. No further in-force blocks are planned, however. Medicare Advantage disruption, with more than 3 million members needing new coverage for 2027, offers a tailwind for MedSupp sales, which rose 41%. The actuarial review also adds roughly $4.5 million per quarter of run-rate earnings. Meanwhile, buybacks of $60 million at an average $54.52 continue to shrink the share count.
Investor sentiment is the notable disconnect. It remained positive but weakened meaningfully into the report, falling from 0.43 to 0.19. That suggests enthusiasm had cooled even as fundamentals kept improving. The stock reflects the same ambivalence. At $55.17, shares are down 4.2% since the open after the July report, though they sit about 14% above the 200-day moving average of $48.40. The longer-term uptrend therefore remains intact while the stock has stalled over the past quarter. The AVWAP reading remains positive, consistent with that intact longer-term trend.
The bottom line is that CNO's quarter was better than the actuarial-inflated headline might suggest, because core operating EPS of $1.42 also cleared expectations. Expense, tax, investment-income and ROE trends are all moving the right way. Still, decelerating sales growth, a trimmed cash flow ceiling and management's own warnings about non-recurring investment income and margin normalization mean the next leg of the story depends on proving these elevated returns can hold. That is a question a cooling investor base appears unwilling to answer on faith.
Read our earnings preview for CNO Financial Group, Inc.: https://www.earningswhispers.com/article/CNO/21174
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Sep-11 | |
| Sep-10 | |
| Aug-27 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
