Methanex Beats Handily As Cash Flow Surges, But Earnings Slipped Sequentially And The Call Added Little New
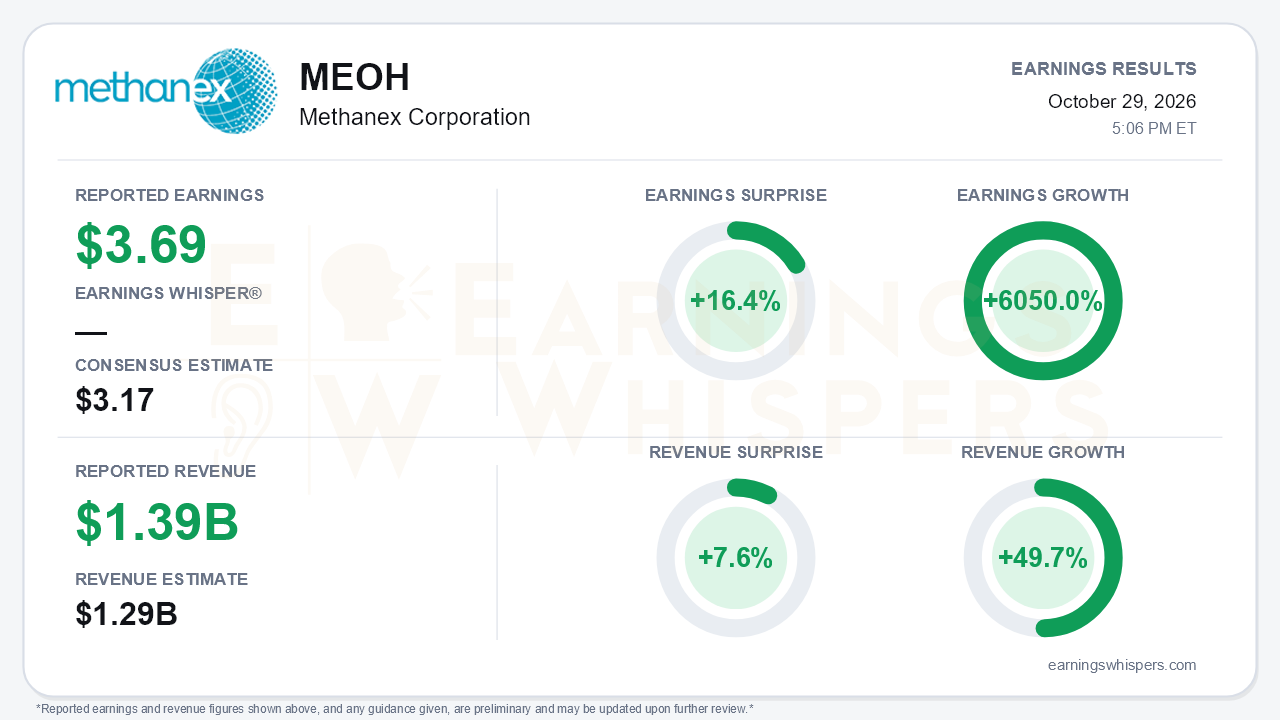
Methanex delivered a clean beat against expectations in the third quarter, even as its earnings momentum cooled from the second quarter. Adjusted earnings of $3.69 per share topped the $3.17 consensus by 16.4%, and revenue of $1.388 billion beat the $1.29 billion estimate by 7.6%. Year-over-year comparisons are extraordinary. Earnings grew 6050.0% and revenue rose 49.7%, but that reflects a nearly breakeven base: adjusted EPS was just $0.06 a year ago, when the realized methanol price was $345 per tonne. The more relevant comparison is sequential, and there the trend softened. Adjusted EPS fell from $3.87, Adjusted EBITDA slipped from $577 million to $543 million, and revenue was essentially flat. That is the central tension. Methanex beat the Street at what may prove to be a modest pause in the earnings cycle rather than at an acceleration point.
The softness came from price, not volume. Average realized price eased to $510 per tonne from $529, while total sales volume edged up to 2.595 million tonnes. Sales of Methanex-produced methanol climbed to 2.279 million tonnes from 2.151 million. Production dipped to 2.143 million tonnes from 2.213 million. Chile ran a single plant for most of the quarter because of seasonal Argentine gas constraints, and Trinidad's Titan plant was indefinitely idled. Record North American output offset part of that shortfall, with Beaumont recovering from its June cooling-tower outage and Natgasoline improving.
On a GAAP basis, diluted EPS rose to $3.42 from $2.45. That gain mostly reflects the absence of the second quarter's $115 million after-tax impairment tied to Titan and Atlas, not better operations. The gap between realized and posted prices also remains wide: $510 realized against a $987 average non-discounted posted price. That spread limits how much of the industry's headline pricing strength reaches Methanex's income statement.
The quality of the quarter shows most clearly in cash generation. Operating cash flow jumped to $646 million from $439 million, and Adjusted free cash flow nearly doubled to $520 million from $298 million. Methanex ended the quarter with $912 million in cash. Management is using that cash to repair the balance sheet. It redeemed $300 million of its October 2027 bonds and expects to retire the remaining $400 million in the fourth quarter. It also authorized a buyback of up to 5% of shares outstanding. With the dividend still only $0.185 per quarter, the buyback marks a meaningful shift toward returning capital.
The outlook points to a sequential rebound. Management expects October-November realized prices of roughly $525 to $550 per tonne. Citing higher pricing and similar produced-methanol sales, it expects higher fourth-quarter Adjusted EBITDA. Full-year production guidance of about 9.0 million tonnes implies a firmer fourth quarter as Chile returns to two-plant operation. The footprint is shrinking, however. Titan is idle, and the agreement to sell New Zealand gas entitlements means those facilities should go idle in early 2027. The deal monetizes declining gas but removes capacity. Pricing also rests heavily on the Middle East conflict, which CEO Rich Sumner credited with a significant loss of industry supply. If that disruption eases, the pricing tailwind could fade. Egypt still faces potential summer gas curtailments.
The conference call offers no help in weighing those risks. The call material available for this review appears to repeat earlier transcripts largely verbatim, built around a years-old Geismar 3 restart update. As a result, it provides no reliable fresh commentary on demand, margins, or guidance. Open questions from earlier in the year remain unaddressed in that material, including Middle East-driven price volatility, New Zealand gas declines, Egypt supply, and the pace of OCI integration synergies. Investors are left leaning almost entirely on the press release.
Investor sentiment improved but stayed negative, moving from -0.134 to -0.075. That reading suggests lingering skepticism about how durable the price cycle is. The stock has run ahead of that caution. Shares are up 19.3% since the open after the July report, and at $62.76 they sit about 11.5% above the 200-day moving average. The Earnings Whispers price and AVWAP trend readings are both positive, consistent with a stock the market has been rewarding.
The bottom line is that Methanex posted a high-quality beat powered by surging free cash flow, rapid debt reduction, and a new buyback. Its sequential earnings trend dipped, however, and future gains depend on geopolitically driven pricing. Fourth-quarter guidance points back up, but a shrinking asset base and an uninformative call leave bears with legitimate questions about durability.
Read our earnings preview for Methanex Corporation: https://www.earningswhispers.com/article/MEOH/21214
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Sep-25 | |
| Sep-21 | |
| Sep-16 | |
| Sep-02 | |
| Sep-01 | |
| Aug-20 | |
| Jul-28 | |
| Jul-28 | |
| Jul-15 | |
| Jun-29 |
