Kite Realty Hits Core FFO Target And Raises Its Outlook, But A Shrinking Portfolio And 2027 Headwinds Temper The Leasing Story
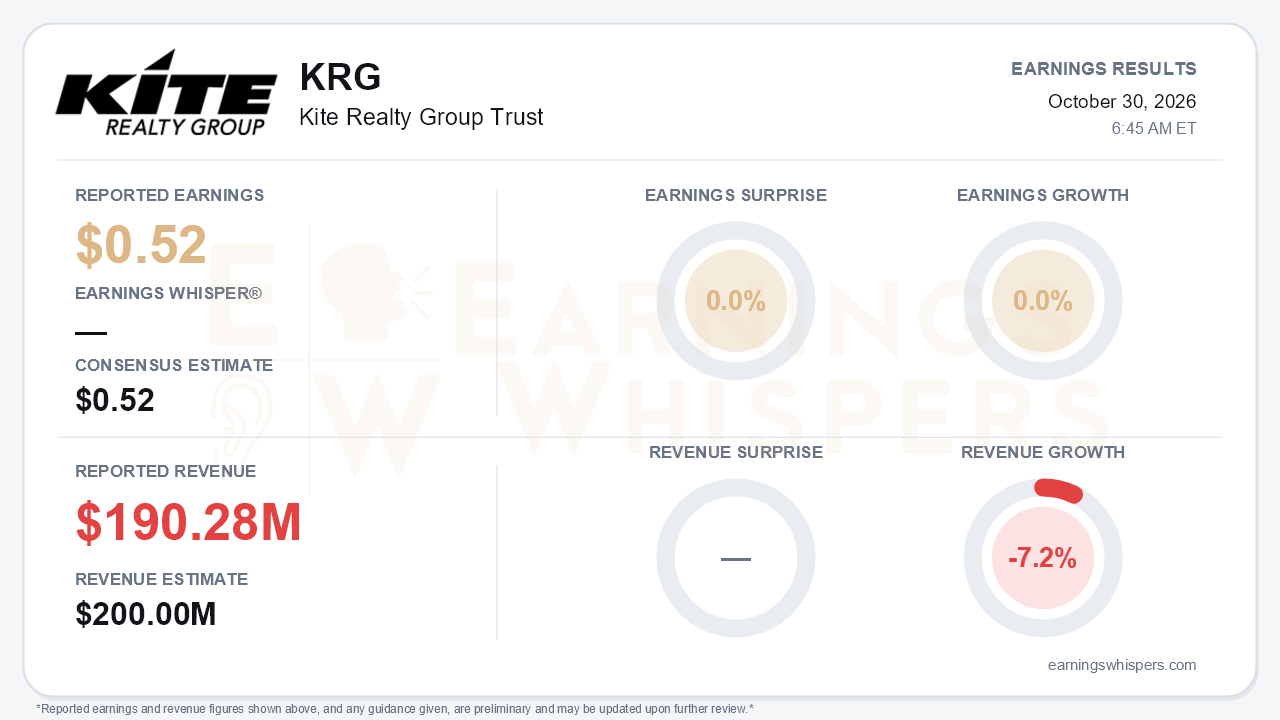
Kite Realty Group delivered exactly what Wall Street expected on earnings and less than expected on revenue. That gap captures the quarter well. Core FFO of $0.52 per share matched the $0.52 consensus and was unchanged from a year ago, a 0.0% surprise and 0.0% growth. Revenue of $190.28 million missed the $200.0 million consensus by 4.9% and fell 7.2% year over year. The central tension is that KRG's leasing engine is running at its strongest pace of the year while the company itself is getting smaller. The flat per-share result owes as much to the shrinking share count as to operating growth.
The quality of the in-line print deserves scrutiny. Total Core FFO dollars fell to $107.0 million from $116.4 million a year earlier. NOI from sold properties dropped from $18.7 million to just $0.2 million as Project Elevate dispositions rolled through. Per-share Core FFO held steady only because weighted diluted shares and units fell roughly 9%, to about 204.5 million from 224.4 million. Cumulative buybacks now total about 22.0 million shares for $539.1 million. On a GAAP basis, KRG posted a net loss of $0.07 per share, the same as last year, driven largely by a $30.7 million impairment charge. Beneath the portfolio reshaping, the core real estate is healthy. Same Property NOI rose 3.6%, and minimum rent in the same-property pool grew to $139.2 million from $135.6 million.
The call made the strongest case on leasing. New-lease cash spreads reached 33.7%, up from 28.4% in Q2. Non-option renewal spreads climbed to 18.3%, and blended spreads were 14.6%. The retail leased rate improved to 95.3% from 94.8% in Q2, and the shop leased rate hit a record 92.7%. Embedded rent bumps have edged up every quarter, from 180bp in Q4 to 188bp now. The leased-to-occupied spread widened to a record 360 basis points, representing $38.8 million of signed-not-open NOI, up from $37 million in Q2. Management expects about $24 million of that to come online in 2027. The tone shifted from describing the heavy lifting as behind the company to calling the reshaping 'nearly complete,' with a platform built to grow. A Fitch upgrade to BBB+ adds credibility to that framing.
The guidance change reads two ways. KRG lifted the low end of its Core FFO range to $2.08 from $2.06 and held the top at $2.12. That is a narrowing, but also the first midpoint increase of 2026 after the range was held for three straight updates. Same Property NOI guidance moved to 3.40%-3.90%, its third raise of the year. The raise is modest, however, and part of the fourth-quarter step-up depends on a roughly one-cent one-time land-sale gain. Q3 same-property growth also ticked down slightly from 3.7% in Q2.
Bears have legitimate ammunition on 2027. Management flagged several headwinds:
- Interest income from 1031 escrow balances will not repeat.
- About three cents of non-cash drag will continue.
- Recurring-but-unpredictable income, about $14 million in 2026 versus $21 million in 2025, will likely decline.
Higher rates are compressing the gap between acquisition yields and debt costs. Planned 1031 acquisitions were cut to $52 million from $110 million, and about $70 million of sales slipped into Q1 2027. That leaves residual special-dividend exposure if those sales slip further. Leverage edged up to 5.2x from 5.1x, and liquidity eased to about $1.1 billion. Management also signaled a preference for balance-sheet conservatism over further buybacks, despite what it framed as a roughly 8% FFO yield. The expected $230 million excess of sources over uses provides optionality, but the per-share lever that sustained 2026 results may be pulled less aggressively.
The market had already grown skeptical heading into the report. Shares opened at $29.33 after the July report, which marked the inter-earnings high, and have since fallen 14.7% to $25.03. That price is about 4% below the 200-day moving average of $26.08 and 5.5% above the October 8 low of $23.72. KRG repurchased shares in the quarter at an average of $26.61, above where the stock now trades. Investor sentiment deteriorated meaningfully, falling from -0.16 to -0.46. The Earnings Whispers price and AVWAP trend readings remain negative, although momentum is positive.
The bottom line is that KRG's leasing data, guidance raise and credit upgrade support a credible organic growth story, with a record signed-not-open pipeline set to convert in 2027. But the quarter did not show earnings growth. It showed a smaller company holding per-share results flat through buybacks, missing on revenue and pointing to non-operating headwinds next year. Until that pipeline visibly outruns the 2027 drags, the gap between improving property fundamentals and sour investor sentiment is likely to remain the defining feature of the stock.
Read our earnings preview for Kite Realty Group Trust: https://www.earningswhispers.com/article/KRG/21287
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 12 hours | |
| 12 hours | |
| Oct-22 | |
| Oct-05 | |
| Sep-14 | |
| Sep-11 | |
| Aug-19 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-02 | |
| Jul-02 | |
| Jun-30 | |
| Jun-29 |
