IRadimed's 3870 Ramp Lifts Revenue To A Record, But A Penny Miss And Low-End Guidance Show Production Is The Constraint
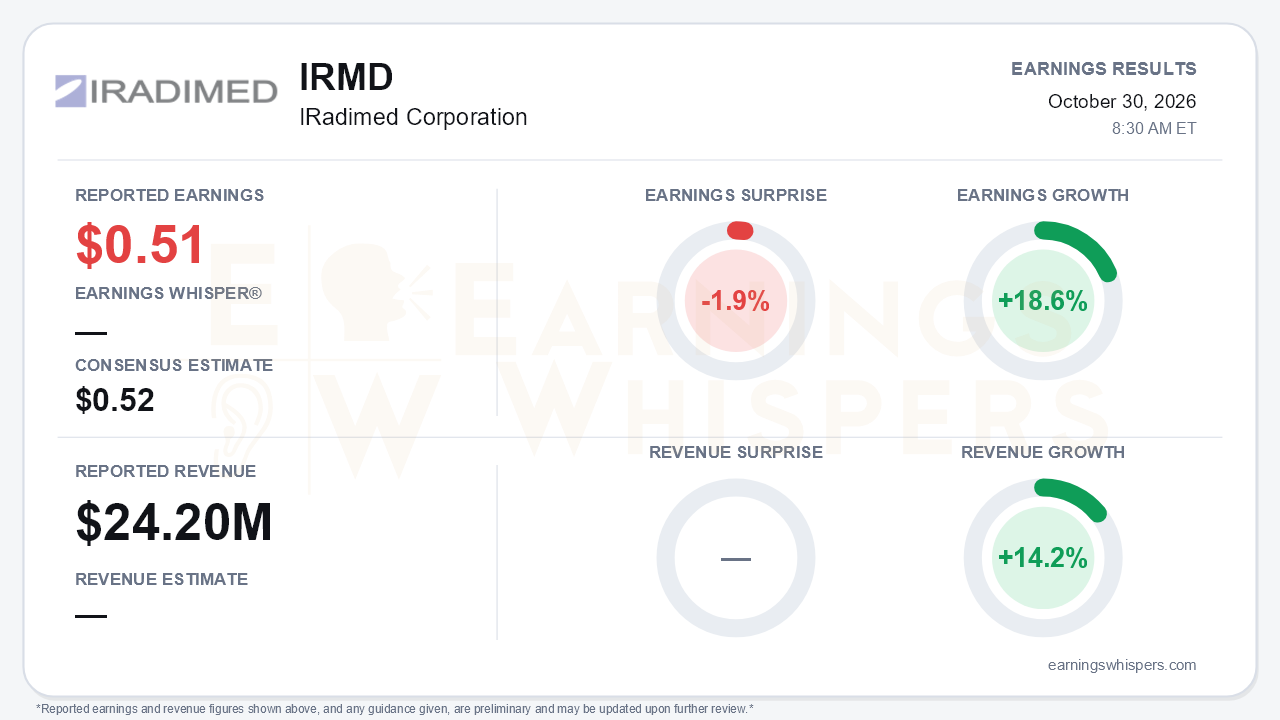
IRadimed (NASDAQ: IRMD) reported third-quarter earnings of $0.51 per share, a penny short of the $0.52 consensus estimate, a 1.9% miss. Revenue reached a record $24.2 million. The miss is less important than the trajectory behind it. Earnings grew 18.6% year over year and revenue rose 14.2%, a clear acceleration from the 9% revenue growth the company posted through the first nine months. Sequentially, revenue jumped 18% from about $20.5 million in the second quarter. That is the central tension: demand for the new 3870 MRI-compatible infusion pump is plainly strong, but the company is deliberately building pumps more slowly than customers are ordering them, and full-year guidance now reflects that limit.
The quality of the quarter is better than the penny miss suggests, though it is not flawless. Non-GAAP EPS was $0.55, up from $0.47 a year ago and $0.47 in the second quarter. Operating income rose to $8.1 million from $6.8 million, and management cited a 34% operating margin, up from 31% in the second quarter. The weaker spot is gross margin. It recovered to 76% from 74% in the second quarter but remains below the 78% of a year ago because of lingering 3870 manufacturing inefficiencies and a heavier international mix carrying distributor discounts. A 24-25% tax rate, the result of smaller windfall deductions, also took a bite out of the bottom line. R&D rose about 30% on lower software capitalization. The balance sheet keeps strengthening. Nine-month free cash flow was $20.1 million versus $11.0 million a year earlier, which was weighed down by facility construction, and cash climbed to $63.3 million.
The segment mix shows where the 3870 story stands. Pump revenue grew only 4% to $8.7 million, a muted figure for a product launch management called very successful. Monitors rose to $8.0 million from $6.9 million, disposables grew 21%, and international revenue rose 45%. The call explained the gap in pumps:
- 3870 production rose more than 125% sequentially to over 400 systems built, with more than 300 shipped, versus 130-135 in the second quarter.
- Management is targeting another 50%-plus step-up in the fourth quarter.
- Pricing is running near $25,000 per channel, a 23-25% premium to the 3860, up from the roughly 20% cited on earlier calls.
- About 70% of bookings were for the four-pump "quad stack," which doubles the channels available at each MRI.
- Bookings set records for both pumps and monitors, and domestic pump channels booked rose 45%.
- Greenfield wins appeared for the first time, including sites that had previously rejected the 3860.
Guidance is where bears have legitimate ammunition. Fourth-quarter guidance calls for revenue of $25.0 million to $26.5 million and GAAP EPS of $0.53 to $0.57, which reaches the $100 million run rate management has promised. Full-year expectations, however, moved toward the low end. The press release puts revenue at $91.6 million to $93.1 million, down from $91.0 million to $96.0 million. GAAP EPS is now $1.90 to $1.94, versus $1.90 to $2.05 previously. The release puts non-GAAP EPS at $2.07 to $2.11, while the call cited slightly different figures for revenue ($91.7-93.2 million) and non-GAAP EPS ($2.06-2.10, against $2.09-2.24 discussed on the second-quarter call). Either way, the top end of the revenue range fell by roughly $2.8 million, and the outlook sits below estimates. Management attributed the cut to throttling the ramp to protect quality rather than to softer demand. That explanation is credible given the bookings data, but it shifts some revenue into 2027 and leaves execution risk on the manufacturing floor.
The forward catalysts are substantive:
- Management offered a first look at 2027, calling for upper-teens revenue growth.
- It expects gross margin to return to 77-78% or better in early 2027.
- 3870 disposables pull-through has not yet begun. Management expects it to start late in the fourth quarter and compound through 2027.
If those pieces land, the current quarter's softness in pump revenue and margin looks like a timing issue rather than a structural one.
Investors entered the report deeply skeptical. Earnings Whispers sentiment collapsed from a roughly neutral 0.06 after the prior report to -0.83 heading into this one, a genuinely large deterioration. The stock has moved the same way. Shares were at $85.74 before the release, down 12.3% from the $97.74 open after the July report, which also marked the inter-earnings high. They trade 7.5% below the 200-day moving average and only 5.3% above the September 10 low of $81.41. The Earnings Whispers trend readings lean negative, with price and AVWAP trends negative while sequential growth and momentum are neutral.
The bottom line is that IRadimed delivered a quarter of accelerating growth, record bookings and recovering margins, wrapped in a penny miss and a full-year outlook pulled toward the low end. With sentiment already deeply negative and shares near the bottom of their range, the debate now centers on whether management can scale 3870 production without quality slippage. If it can, the backlog, pricing premium and coming disposables stream support the upper-teens growth story management laid out for 2027.
Read our earnings preview for IRadimed Corporation: https://www.earningswhispers.com/article/IRMD/21330
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 12 hours | |
| 12 hours | |
| Oct-23 | |
| Oct-23 | |
| Sep-23 | |
| Sep-21 | |
| Aug-03 | |
| Jul-31 | |
| Jul-31 | |
| Jul-24 | |
| May-20 | |
| May-02 | |
| May-01 | |
| May-01 |
