Capital Clean Energy Carriers Beats As Fleet Growth Drives Record Quarter, But LNG Market Softness Erodes The Forward Story
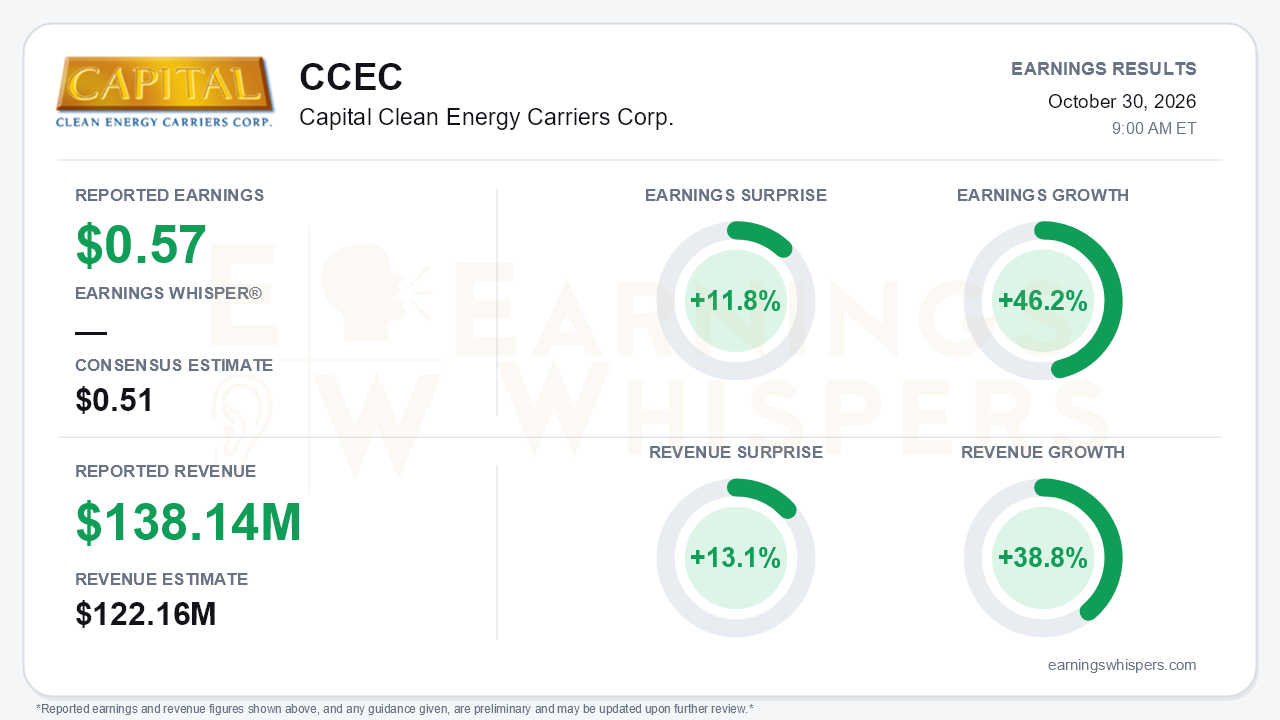
Capital Clean Energy Carriers (NASDAQ: CCEC) delivered a clean beat on the headline numbers. Third-quarter earnings of $0.57 per share topped the $0.51 consensus by 11.8%, and revenue of $138.14 million beat expectations by 13.1%. Earnings Whispers calculates year-over-year earnings growth of 46.2% and revenue growth of 38.8%. The company's own continuing-operations comparison shows revenue up 44% and net income up 52%, measured against a different prior-year base. Either way, the quarter is a sharp acceleration. Through the first nine months, continuing-operations EPS of $1.36 still trails last year's $1.45, so Q3 is the period where the newbuild program finally showed up in the results. That is the central tension: the income statement has never looked better, while the LNG shipping market that anchors the long-term story softened markedly during the quarter.
The beat is real, but it is overwhelmingly a volume story rather than a pricing one. The average fleet count rose to 19.7 vessels from 13.0 a year ago, following eight deliveries so far in 2026. LNG carrier TCE was essentially flat at $83,862 per day versus $84,123. Sequentially, revenue jumped from $104.9 million in Q2, and continuing net income climbed to $34.6 million from $29.0 million in Q2 and $18.3 million in Q1.
Underneath, costs grew roughly in line with the fleet:
- Depreciation rose to $30.4 million from $21.8 million.
- Interest expense rose to $33.7 million from $25.5 million as total debt swelled to $3.2 billion from $2.45 billion at year-end.
- Voyage expenses quadrupled to $9.0 million, reflecting positioning costs for newly delivered ships and ballast legs around special surveys.
- Off-hire for the Attalos and Asklipios surveys also clipped available days.
The quality is solid, but margin expansion was not the driver.
The call laid bare how quickly LNG conditions have turned. Atlantic two-stroke spot rates averaged about $51,000 per day in Q3. That compares with a year-to-date average near $93,000 cited on the prior call, and rates hit a trough around $10,000 in August. More consequential for CCEC, management acknowledged that the near-term tonnage imbalance is bleeding into long-term pricing. Benchmark term rates have eased to roughly $80,000 from about $90,000, and forward rates soften into 2027 as uncommitted newbuilds deliver. The backlog also slipped:
- Firm contracted revenue edged down to about $2.8 billion from $2.9 billion, or $4.2 billion with options versus $4.3 billion.
- The LNG book fell to $2.7 billion and 6.4 years of firm cover.
Five LNG newbuild positions remain open and will have to be marketed into this weaker term environment. Management's tone moved noticeably, from talk of a profound structural shift earlier in the year to a more defensive, volatility-focused framing. Scrapping has also stalled at seven vessels year to date, undercutting the earlier thesis of accelerating fleet renewal.
The gas segment is the bright spot and a genuine offset. All five 2026 gas newbuilds are delivered and employed, and the Gas Fleet earned $40,987 per day. Disruption at Hormuz, Panama Canal auction suspensions and record US LPG exports pushed MGC one-year rates to roughly $43,000 per day. Newbuilds due in early 2027 are already drawing firm term bids. On the LNG side, index-linked charters on Alcaios I and Athlos keep exposure to a potential winter squeeze, with European storage below normal and gas prices elevated. Management also highlighted a growing liquefaction FID pipeline as long-term support.
The balance-sheet calendar is the risk bulls cannot ignore. Scheduled capex reaches $640.7 million in Q1 2027 alone, against total cash of $286.6 million. Meanwhile, the fixed or hedged share of debt dipped to about 47% from 50%, and net leverage edged up to around 55%. The planned $230 million Amore Mio I sale to the BGN joint venture, slated for Q1 2027, is therefore an important piece of the funding picture.
The market had already been leaning skeptical. Shares entered the report at $19.73, down 14.2% from the open after the July release. That left the stock 16.2% below its August 3 inter-earnings high of $23.55 and 9.3% above its September 30 low. The company bought back stock in Q3 at an average of $22.57, well above where shares now trade. Investor sentiment remained positive but cooled modestly, slipping to 0.15 from 0.20. Earnings Whispers price and AVWAP trend readings are negative even as momentum reads positive.
The bottom line is that CCEC delivered exactly what its fleet expansion promised: record revenue, accelerating earnings and a comfortable beat. However, the forward story now hinges less on execution and more on the LNG rate cycle. A shrinking backlog, softer long-term rates, five open newbuilds and heavy 2027 capex give bears legitimate ammunition, while a strong gas market and winter-exposed index charters keep the upside case alive.
Read our earnings preview for Capital Clean Energy Carriers Corp.: https://www.earningswhispers.com/article/CCEC/21329
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 10 hours | |
| Oct-23 | |
| Oct-23 | |
| Oct-22 | |
| Sep-23 | |
| Sep-09 | |
| Aug-07 | |
| Aug-05 | |
| Aug-03 | |
| Jul-29 | |
| Jul-23 | |
| Jul-22 | |
| Jun-18 | |
| Jun-12 |
