COPT Defense Beats And Raises Again, But Slowing FFO Growth And A New Rate Headwind Complicate A Strong Defense-Demand Story
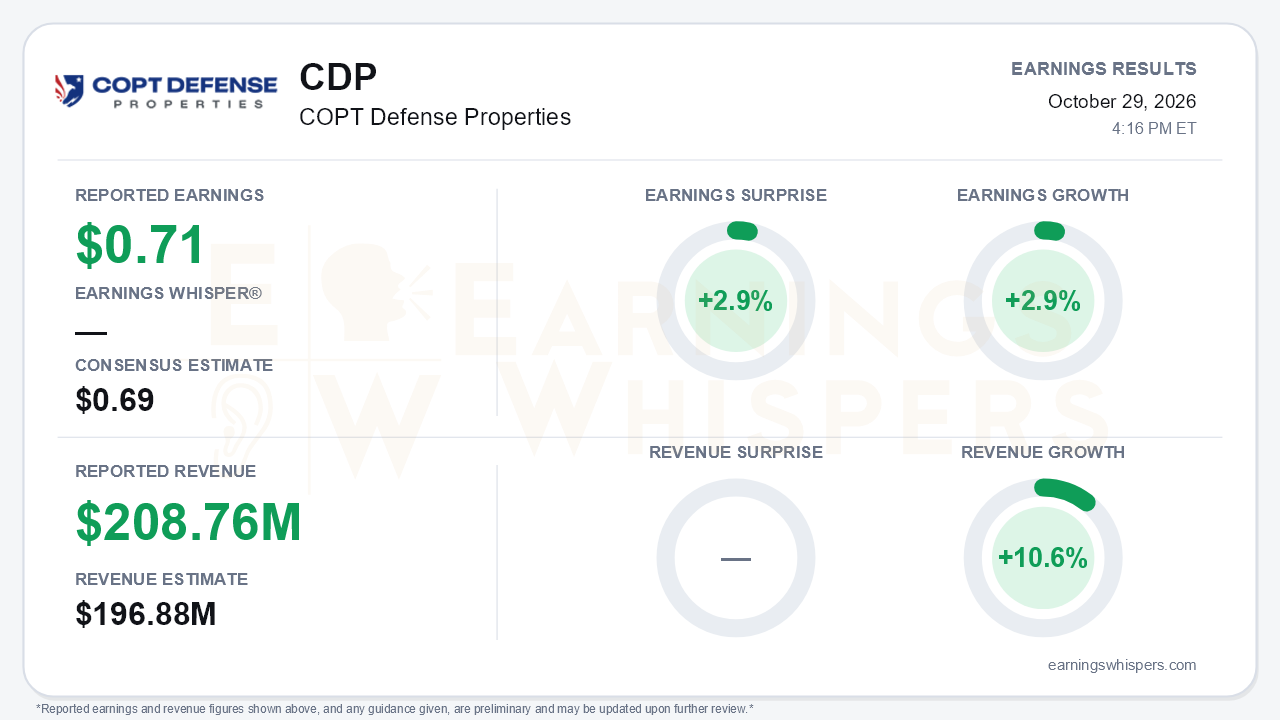
COPT Defense Properties delivered another beat-and-raise quarter. It also showed that strong demand is not translating into faster per-share growth. FFO per share, as adjusted for comparability, came in at $0.71. That beat the $0.69 consensus by 2.9%, topped the company's own guidance midpoint by two cents and rose 2.9% from a year ago. Revenue of $208.76 million beat expectations by 6.0% and grew 10.6%. Management lifted the full-year FFO midpoint to $2.80, the third consecutive increase from an initial $2.75. That is the central tension: the demand pipeline keeps getting larger while the earnings growth rate keeps getting smaller. Year-over-year FFO growth has stepped down from 6.2% in the first quarter to 4.4% in the second and 2.9% now, and the full-year guide implies only 2.9% growth.
The quality of the beat deserves some scrutiny. Part of the revenue upside came from construction contract and other service revenue, which jumped to $13.4 million from $8.5 million. That business runs at thin margins, with $12.8 million of corresponding expenses, so it adds little to earnings. The core story is better measured by lease revenue, which climbed to $193.5 million from $178.3 million. On the GAAP side, EPS of $0.41 compared with $0.37 a year ago, helped by $7.7 million of real estate sale gains versus $3.0 million last year. The bigger drag sits below the operating line. Interest expense rose to $24.4 million from $20.9 million, and adjusted EBITDA fixed charge coverage slipped to 4.4x from 4.8x. Same-property cash NOI growth slowed to 3.2% from 7.4% in the second quarter, a deceleration management had flagged in advance. Even so, the full-year same-property target rose to 4.25% from an initial 2.5%.
The call preserved a credible growth story, driven by defense demand and Huntsville in particular. Management described a "uniquely strong sense of urgency" among tenants. Three moves stood out:
- **Vacancy leasing target:** raised to 625,000 square feet from 475,000, well above the initial 400,000. About 710,000 square feet is already executed or in advanced negotiations, and the leasing activity ratio rose to 83% from 69%.
- **Redstone Gateway expansion:** the master plan grew by 500,000 square feet to 6.4 million square feet of capacity.
- **New development starts:** two inventory buildings totaling $88 million began, carrying roughly 340,000 square feet of prospects. Capital committed to new investments rose to $375 million, the highest since 2021.
Management also pointed to the proposed 28% increase in the FY2027 defense budget request and to priorities such as missile defense and Golden Dome as tailwinds.
Bears have legitimate ammunition, though. The retention guidance cut to 80% from 82.5% is framed as deliberate: the company is recapturing about 160,000 square feet from three weaker tenants, and roughly 145,000 square feet is already backfilled or expected to be, including a Lockheed Martin expansion. Third-quarter retention was still only 70%, and the total portfolio's leased rate fell 60 basis points to 95.0% after a law firm move-out and an early termination. Headline renewal spreads looked strong, at 8.5% on a cash basis, but excluding data center shells they were just +0.7%. The more consequential new disclosure was financial. The CFO quantified roughly $8 million, or about seven cents per share, of incremental 2027 interest expense implied by the SOFR forward curve. New long-term unsecured debt now prices at roughly 5.8% to 6.3%. Exchangeable-note dilution of about three cents this year and non-core dispositions pushed out "several years" add further friction. Midterm elections could also shift the timing of Golden Dome and FY27 budget funding, although management expects an FY27 appropriation by February.
The market has been treating the stock more cautiously than management's tone would suggest. Shares stood at $34.25 entering the report, down 11.9% from the $38.86 open after the July release. That sits awkwardly with the CEO's reference to a 20% share price gain over the first nine months, and it suggests much of that advance was surrendered during the quarter. The stock now sits just 2.1% above its 200-day moving average of $33.56, a thin cushion. Investor sentiment swung meaningfully, from slightly positive at 0.08 to clearly negative at -0.46. That shift likely reflects concern about rates and decelerating growth rather than doubts about demand. Supporting trend readings lean negative, with AVWAP negative and price trend only neutral.
The bottom line is that COPT Defense continues to execute and keeps raising the bar on leasing, development and capital deployment, underpinned by a defense spending backdrop few REITs can match. Per-share growth, however, is slowing toward the low single digits. A newly quantified 2027 interest-expense headwind means demand strength will need to translate into development yields quickly enough to offset financing costs. Until that conversion becomes visible in FFO growth, the gap between an improving operating story and a skeptical market is likely to persist.
Read our earnings preview for COPT Defense Properties: https://www.earningswhispers.com/article/CDP/21172
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-01 | |
| Sep-09 | |
| Aug-13 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-01 | |
| Jun-24 | |
| May-27 | |
| May-14 | |
| Apr-29 |
