Standard Motor Products Beats On Record Profitability And Early Deleveraging, But Slowing Sales And A Soft Temperature Control Outlook Cloud The Picture
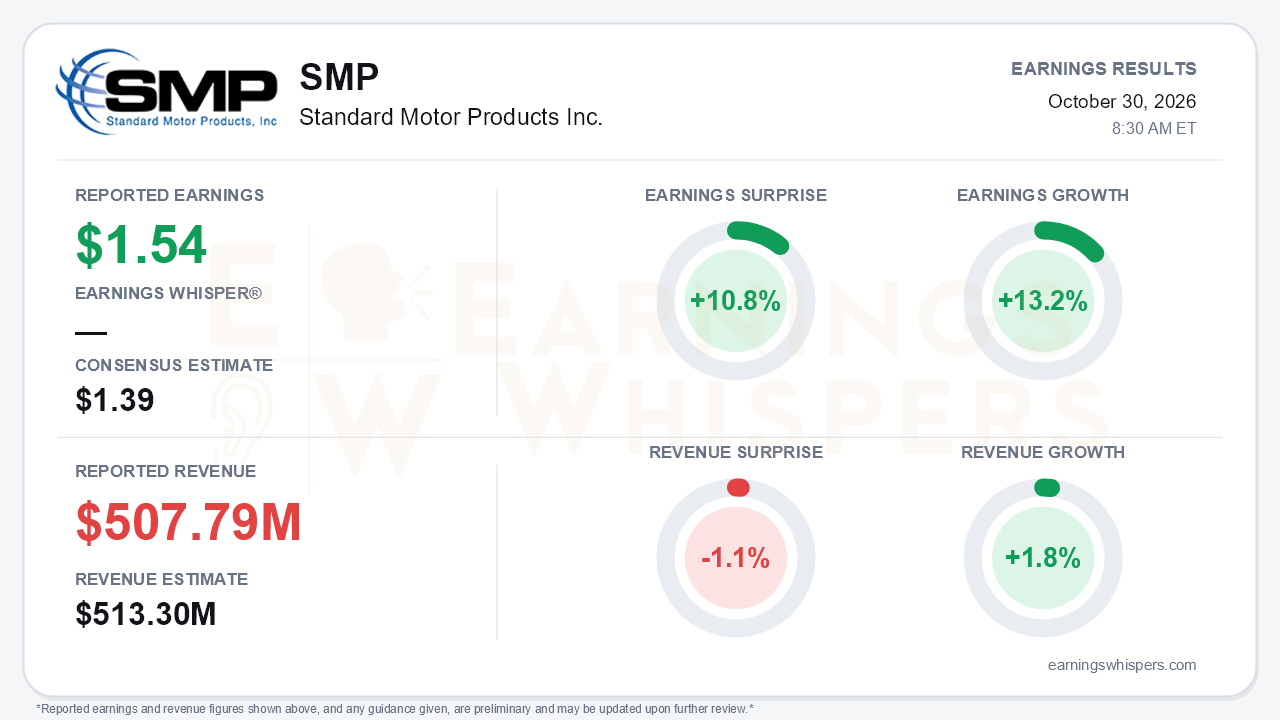
Standard Motor Products delivered a margin-driven beat. It reported adjusted earnings of $1.54 per share for the September quarter, 10.8% above the $1.39 consensus and 13.2% higher year over year. Earnings growth also accelerated: second-quarter adjusted EPS of $1.40 had grown 8.6%. Revenue was the weak spot. Sales of $507.79 million missed the $513.3 million consensus by 1.1% and grew just 1.8%. That is the central tension. Profitability, cash generation and the balance sheet are all moving in the right direction, while the top line keeps losing speed.
The quality of the beat is better than the revenue miss suggests, but it deserves some scrutiny. GAAP earnings from continuing operations rose to $1.42 from $1.32. The gap to the adjusted figure comes mainly from a $3.6 million litigation charge in the Nissens segment, worth $0.16 per share, which management excluded. Lower interest expense also helped, falling to $6.3 million from $7.4 million as debt came down. On the sales line, SMP reported adjusted net sales of $512.9 million, up 2.8%. That figure excludes $5.1 million tied to the accounting for IEEPA tariff refunds that the company estimates may be passed through to customers. Even the adjusted figure shows a clear deceleration, from 9.1% growth in the first quarter to 6.7% in the second and 2.8% now. Year-to-date growth has slipped to roughly 6% from about 8% at mid-year. Below the line, a $18.5 million loss from discontinued operations kept net earnings attributable to SMP at $14.1 million, though that was still a swing from a $4.3 million loss a year ago.
The segment detail shows the earnings mix shifting. Vehicle Control was the standout. Adjusted sales rose 6.0% and the adjusted EBITDA margin expanded to 13.6%, up from 10.3% a year ago and 8.6% in the second quarter. Management credited deeper customer assortments aimed at do-it-for-me repair demand, an easier comparison, and early benefits from optimizing its Shawnee, Kansas distribution center. Nissens accelerated to 7.6% growth, reaching $91.0 million, helped by record European heat, and its margin improved to 18.2%. Those gains carried consolidated adjusted EBITDA to a record $66.6 million, a 13.0% margin versus 12.4% last year.
The offsets are real.
- **Temperature Control:** Sales fell 4.1% against a record comparison, and AC system components dropped to $106.0 million from $114.0 million. The segment margin compressed to 14.9% from 19.7% a year ago, hurt by lower absorption and a stronger Mexican peso. On the call, management acknowledged that customer shelves are well stocked after heavy preseason buying. That raises the risk of softer 2027 preseason orders.
- **Engineered Solutions:** Growth slowed to 4.9% from 16.8% in the second quarter, and the margin slipped to 9.6%. Management now expects more normalized low-to-mid single-digit growth.
- **CFO departure:** CFO Nathan Iles left on the day of the call, with Jim Burke serving as interim CFO. The timing is unhelpful but does not change the operating picture.
The balance sheet is the cleanest positive. Net debt fell to $381.9 million from $510.2 million at the end of June, and leverage dropped to 1.8x. That beats the 2.0x year-end target a quarter early. Nine-month operating cash flow reached $207.2 million, up from $85.7 million last year. Part of that improvement came from working capital, including a $74.3 million reduction in inventory and a sharp build in accrued liabilities and rebates. Some of that benefit may not repeat at the same pace. Management also highlighted new catalysts:
- a premium AC condenser program in North America that draws on the Nissens supply base;
- a third new Nissens category in Europe, air door actuators;
- a Thailand sensor joint venture ramping production to reduce reliance on China.
Management said cross-selling launches are running ahead of expectations. Full-year guidance was reaffirmed for a fourth straight call: low-to-mid single-digit sales growth and an 11%-12% adjusted EBITDA margin. That guidance explicitly excludes further tariff changes, geopolitical inflation and higher interest rates affecting customer supply-chain financing.
Investor sentiment improved heading into the report but remains negative, rising to -0.30 from -0.42. The stock's action fits that cautious stance. Shares closed at $38.25 ahead of the release, 1.8% below the opening price after the August report and just under the 200-day moving average of $38.57. The stock peaked at $41.74 on the day of the prior report, sank to $34.67 in mid-October, and has since recovered about 10% off that low. Shares sit roughly in the middle of the post-August range. The trend readings are mixed: price trend negative, AVWAP positive.
The bottom line is that SMP is executing well on what it controls. It delivered record EBITDA, a sharp margin recovery in Vehicle Control, faster Nissens growth and deleveraging ahead of schedule. Still, the top line is decelerating, Temperature Control faces a potentially soft 2027 preseason, and Engineered Solutions is normalizing. Bulls get a credible margin and balance-sheet story. Skeptics have legitimate ammunition in the revenue miss and the slowing growth. The fourth quarter will need to show that profitability can keep improving even as sales growth cools.
Read our earnings preview for Standard Motor Products Inc.: https://www.earningswhispers.com/article/SMP/21301
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-27 | |
| Oct-22 | |
| Oct-09 | |
| Sep-10 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-07 | |
| May-26 | |
| May-11 | |
| Apr-30 |
