TOMI's Breakeven Bet Meets A $12 Million Target That Demands A Second-Half Surge
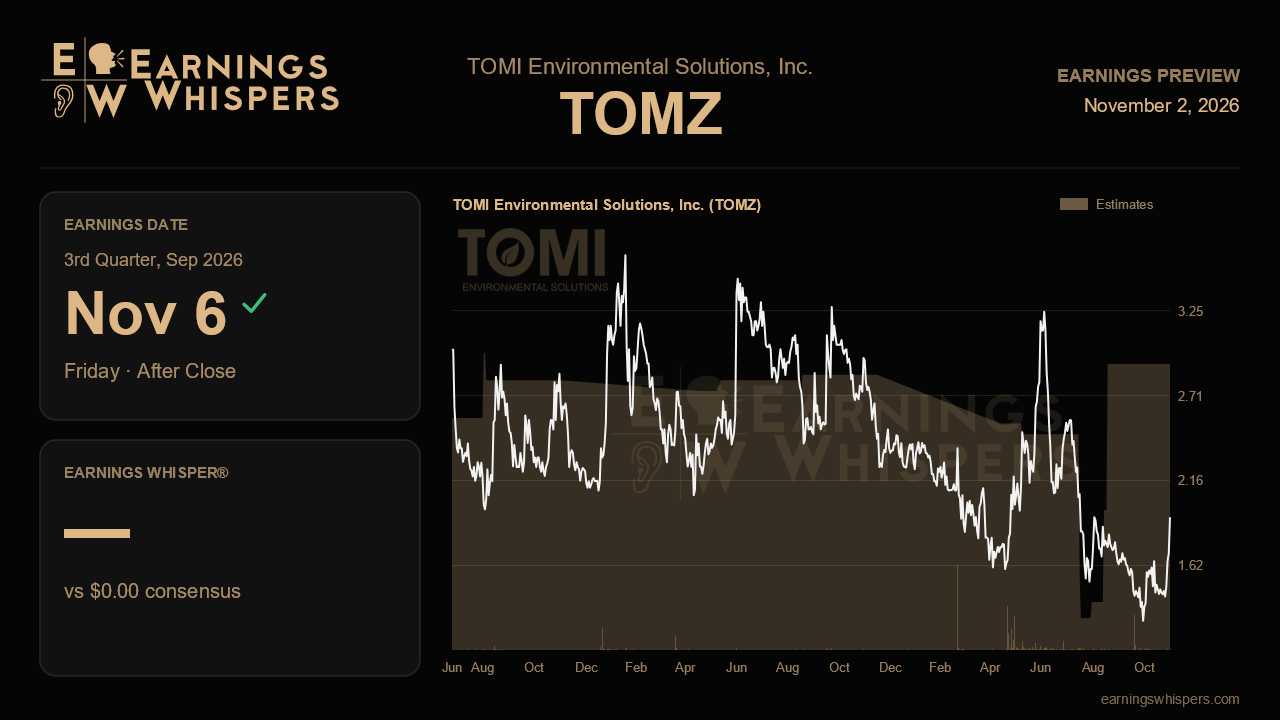
TOMI Environmental Solutions heads into its third-quarter report with a credibility problem of the pleasant kind. Last quarter's numbers were the strongest in years, but management kept its full-year revenue target at the same figure of at least $12 million it has cited since late last fiscal year. With roughly $3.9 million booked across the first two quarters, that target implies something close to $8 million in the back half, or about $4 million a quarter. That is nearly double the record $2.25 million TOMI just posted. The report due after the close on November 6 should show whether the second-half ramp is real or whether the guidance is quietly running out of road.
The Street is looking for breakeven earnings per share, which would mark a full swing from the 2-cent loss a year ago and an improvement from last quarter's 5-cent loss. No revenue consensus is available, so the year-ago figure of about $2.1 million is the practical yardstick. Breakeven this quarter would land a quarter ahead of management's own stated goal of reaching breakeven in the fiscal fourth quarter, so the earnings bar is arguably more aggressive than the company's roadmap. The July 1-for-3 reverse split and ongoing note conversions also muddy per-share comparisons, which makes operating loss a cleaner gauge than EPS.
The case for optimism rests on the operating evidence management laid out last time. Backlog climbed steadily from $1.6 million at year-end to $2.6 million by the time of the call, and the commercial pipeline swelled to roughly $35 million. Gross margin rebounded to 61.7% after a discount-driven dip to 50.3%, and operating expenses fell 10% year over year. Validation this quarter would look like revenue meaningfully above $2.25 million, backlog converting rather than merely accumulating, and gross margin pushing back toward the 65.7% level of a year earlier. The applicator business, which jumped to $355,000 from almost nothing a year ago, is the clearest test of whether the recurring, razor-blade model is building on itself. Another sequential gain there would matter more than any single equipment order.
There are specific swing factors to track. The roughly $1 million CES bid had slipped from a June decision to September, so the outcome should now be known; a win would go a long way toward closing the guidance gap, while another delay would raise doubts. The new healthcare customer won at Interfex, the Fortune 500 chamber delivery tied to an FDA 510(k) path, and fresh defense approvals all need to start appearing as revenue rather than press. Service revenue, up just 3% last quarter after a large customer stopped needing decontamination, remains the soft spot. On the balance sheet, further equity line draws and conversions would add dilution, and any update on raising the $10 million needed for the Carbonium Core merger will color how much management attention is drifting toward speculative ventures.
Sentiment has warmed noticeably, moving from slightly bearish before the last report to solidly bullish now, and the stock has gained about 3% since then while the S&P 500 slipped nearly 3%. Still, enthusiasm has limits. At $1.93 the shares sit just under their 200-day moving average and about 6% below the post-earnings high of $2.06, well off the $3.24 peak of the prior quarter. The market has rewarded the story modestly, not priced in a blowout.
The central question is simple: does the third quarter put TOMI on a credible path to $12 million and breakeven, or does it reveal that last quarter's inflection was a step rather than a staircase? A strong top line with margin recovery and growing applicator sales keeps the turnaround narrative intact. A flat quarter paired with reaffirmed guidance would force investors to start discounting the target, and the dilution behind it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 7 hours | |
| Oct-29 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-21 | |
| Sep-18 | |
| Sep-17 | |
| Aug-17 | |
| Aug-15 | |
| Aug-14 |
