Barrick's H2 Production Promise Faces Its First Test As Shares Sink Toward Range Lows
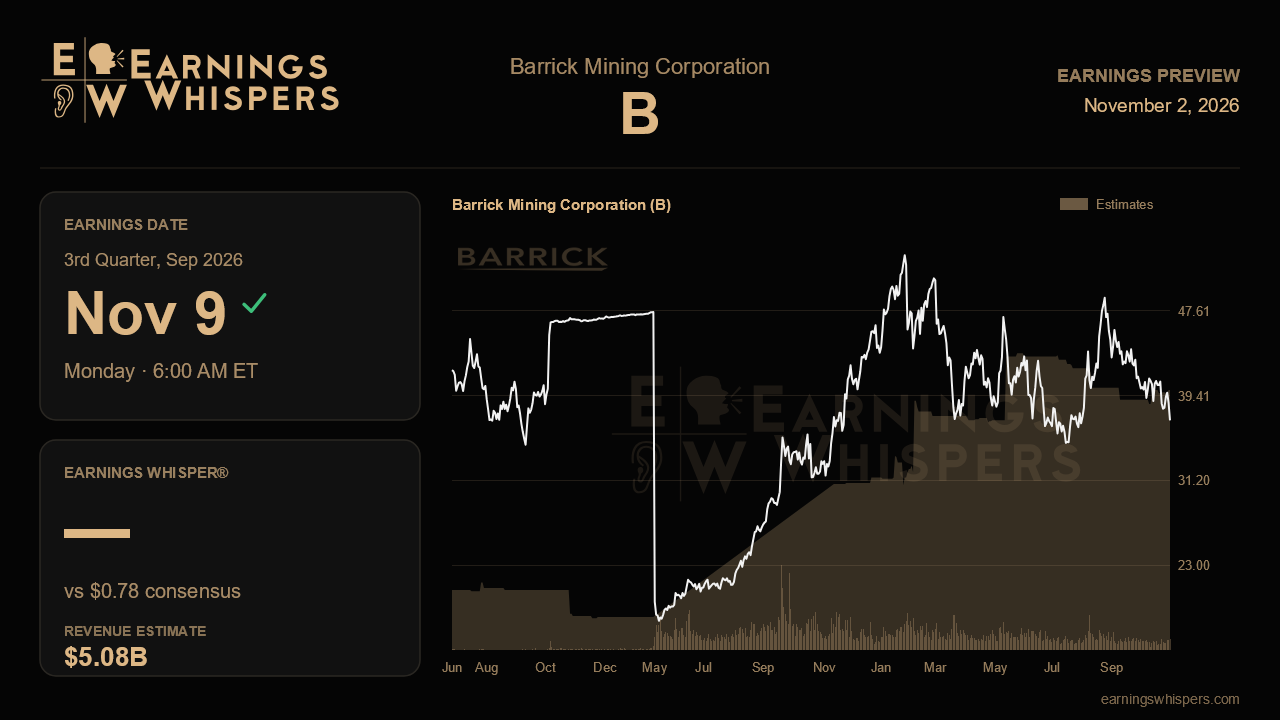
Barrick Mining heads into its third-quarter report with a gap between what management promised and what the market seems willing to believe. Last quarter the company beat production guidance for a third straight time, reaffirmed a 2026 plan weighted toward the back half, and signed a $4 billion settlement with Newmont that clears the way for its North American gold IPO. Since then the stock has fallen about 10%, trailing the S&P 500 by roughly 8 percentage points. The November 9 report, due before the open, is the first real chance to show whether the second-half ramp is arriving on schedule.
The Street expects adjusted EPS of $0.78 on revenue of about $5.08 billion. Compared with a year ago, that is strong growth: earnings up about 34.5% and revenue up 22.5%. Sequentially, though, both figures sit below the $0.82 and $5.29 billion reported last quarter. That is the tension to watch. If production is meant to climb in the second half, a quarter-over-quarter dip in estimates suggests analysts are allowing for softer pricing, higher costs, or a slower ramp than management's framing implies. A result that matches or beats the second quarter would support the back-half story. One that only clears a lowered sequential bar would leave questions open.
Production is the cleanest test. Output rose to 796,000 ounces in the second quarter from 719,000 in the first, and the stated plan points higher from here. The weather outages at Veladero and Porgera were described as temporary, so a clean recovery at both sites would help confirm that. Margins matter just as much. EBITDA margin at Nevada Gold Mines and Pueblo Viejo fell to roughly 61% from about 70%, and other regions slipped to 59% from 65%, partly because of cost mix. If margins return toward first-quarter levels, the dip looks like noise. If they stay in the low 60s or keep sliding, the market may decide that rising costs, including persistent turnover near 14% at Nevada, are eating into the gold-price tailwind.
Free cash flow is the third piece. Second-quarter attributable free cash flow fell 33% from a year earlier because of tax and interest timing plus a one-time $200 million retroactive royalty payment in Mali. Management said that without those items the figure would have risen about 60%. This quarter should test that claim, since the one-off should not repeat. Strong cash generation would also matter for capital returns, which more than doubled to $1.5 billion last quarter, including $1.2 billion of buybacks under the $3 billion authorization. Keeping that pace requires cash, not just reported earnings.
The strategic agenda adds another set of checkpoints. Investors will want updates on the IPO timeline, which management said is on track for the end of 2026, on folding the Marc and Fiberline assets into Nevada Gold Mines, and on the 4 Mile project. The lack of a filed economic study for 4 Mile drew sharp pushback on the last call and was cited as a factor in the post-earnings selloff. Any clarity on its economics, or on the possible $2.5 billion processing expansion, could help investors value the IPO vehicle. Further changes to the Reko Diq timeline, already pushed out through a capex cut, would be read closely too.
Sentiment has cooled, with the bullish reading slipping to 15.1% from 22.0% a quarter ago. At $37.01, the stock sits well below its 200-day moving average of $42.17 and within about 2% of its post-earnings low of $36.27, far from the $49.14 high. That leaves a modest bar for good news but little support if the report disappoints. The central question is simple: does the second half look like the stronger half management described? Higher production, recovering margins and clean cash flow would put the turnaround narrative back on track. A sequential stall would give skeptics more evidence that the momentum peaked in the spring.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-22 | |
| Oct-09 | |
| Oct-06 | |
| Sep-29 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-27 | |
| Sep-23 | |
| Sep-18 | |
| Sep-17 | |
| Sep-17 | |
| Sep-17 | |
| Sep-16 |
